Your debt-to-income ratio is the single most important number most borrowers have never calculated. Before a lender approves your mortgage, they divide your total monthly debt payments by your gross monthly income to determine whether you can realistically handle another obligation. A DTI of 35% means $35 of every $100 you earn is already committed to debt — and lenders have hard thresholds for how high that number can go before they decline your application. In 2026, with the Census median sales price of new U.S. homes at $410,700 (Q2 2026) and Freddie Mac's average 30-year fixed rate at 7.40% as of October 15, 2026, understanding and optimizing your DTI is more critical than ever.
Quick Answer
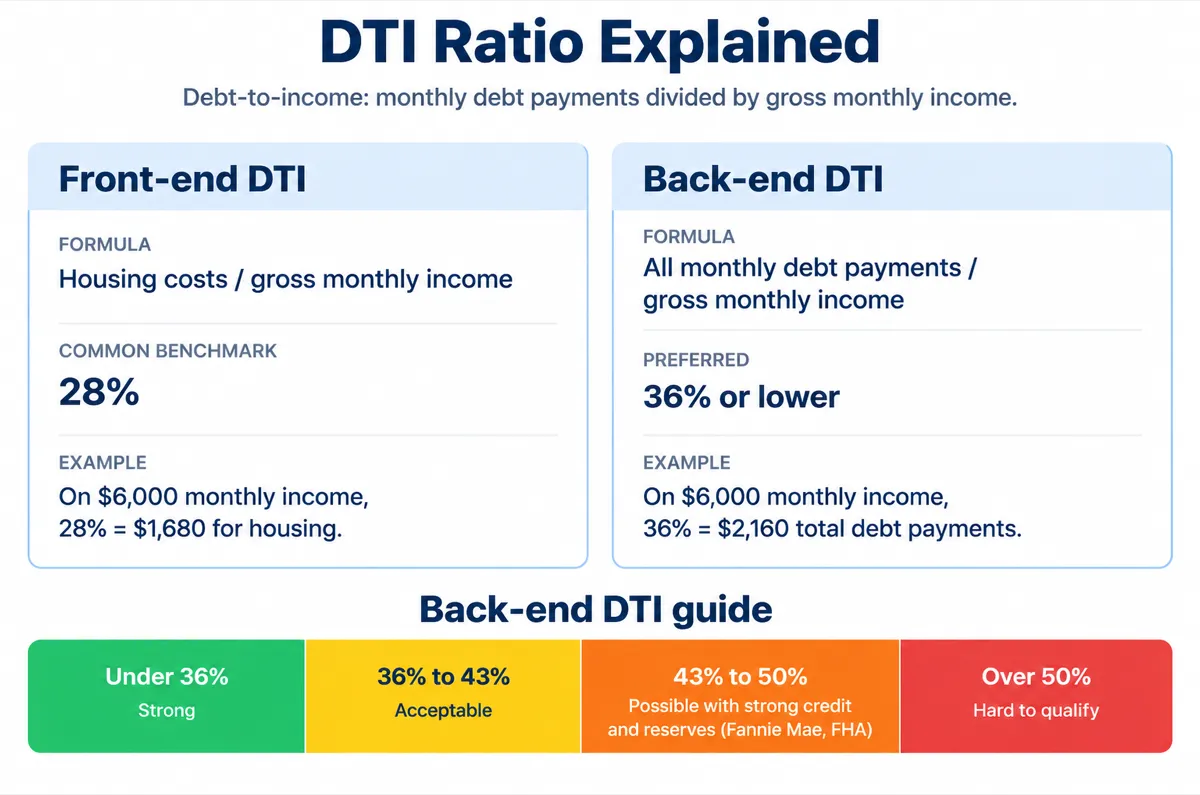
Your debt-to-income ratio equals total monthly debt payments divided by gross monthly income. Conventional guidelines often target 28% front-end and 36% back-end DTI; Fannie Mae allows up to 45% manual and 50% on DU-approved loans. FHA manual underwriting uses 31%/43% by default, up to 40%/50% with compensating factors.
Sources U.S. Census / HUD — median new home sales price Q2 2026 ($410,700), Freddie Mac — PMMS 30-year fixed 7.40% (Oct. 15, 2026). Checked October 2026.
What Is Debt-to-Income Ratio and How Is It Calculated?
Debt-to-income ratio (DTI) measures the percentage of your gross monthly income that goes toward paying recurring debts. Lenders use it as a primary gauge of your ability to manage new monthly payments. The formula is simple: DTI = (Total Monthly Debt Payments / Gross Monthly Income) x 100. If you earn $8,000/month before taxes and pay $2,400 in total debts, your back-end DTI is 30%.
Lenders evaluate two distinct versions of DTI. The front-end ratio (also called the housing ratio) includes only housing-related costs: mortgage principal and interest, property taxes, homeowners insurance, and HOA dues. Conventional lenders often use a 28% housing benchmark (Fannie Mae's published limits focus on total back-end DTI; see B3-6-02). The back-end ratio includes housing costs plus all other recurring obligations: car payments, student loans, credit card minimums, personal loans, child support, and alimony. The standard threshold for manually underwritten conventional loans is 36%, though Fannie Mae permits up to 45% with Eligibility Matrix credit and reserves, and up to 50% on DU-approved loans.
The critical detail most borrowers miss: lenders use gross income (before taxes and deductions), not net take-home pay. A person earning $72,000 annually has a gross monthly income of $6,000, even if their paycheck after taxes, retirement contributions, and insurance premiums is only $4,200. This distinction means your DTI may be lower than you think if you have been mentally calculating with net pay. Use our Debt-to-Income Ratio Calculator to see your exact front-end and back-end ratios instantly.
What Counts as Debt (and What Does Not)
Not every monthly expense counts toward DTI. Lenders include fixed monthly obligations that appear on your credit report, plus housing costs. Here is the full breakdown:
| Included in DTI | NOT Included in DTI |
|---|---|
| Mortgage / Rent payment | Groceries and food |
| Property taxes and insurance | Utility bills (electric, gas, water) |
| Car loan payments | Streaming subscriptions |
| Student loan payments | Cell phone bills |
| Credit card minimum payments | Gasoline and transportation |
| Personal loan payments | Health / auto / life insurance |
| Child support / Alimony | Gym memberships |
| Co-signed loan obligations | Daycare / tuition expenses |
Two common traps: credit card minimums are counted at the minimum payment due on your statement, not the full balance or the amount you actually pay. If your minimum is $35 but you pay $500/month, lenders count $35. Second, deferred student loans still count — Fannie Mae requires 1% of the outstanding balance (or a fully amortizing payment) when no payment appears on the credit report; Freddie Mac uses the greater of the reported payment or 0.5% of the balance. A $45,000 deferred balance adds $225 to $450/month depending on investor guidelines.
Sources Fannie Mae Selling Guide B3-6-05 — deferred/forbearance student loans, Freddie Mac Bulletin 2017-23 — student loan payment in DTI. Checked October 2026.
DTI Thresholds by Loan Program
Different mortgage programs set different DTI limits. The table below shows the standard guidelines lenders follow in 2026:
| Loan Program | Front-End Max | Back-End Max | Exceptions |
|---|---|---|---|
| Conventional | 28% | 36% | Up to 45% manual; up to 50% DU (Fannie Mae B3-6-02) |
| FHA | 31% | 43% | Up to 40%/50% with compensating factors (HUD 4000.1 manual) |
| VA | No limit | 41% | Residual income test used; no hard front-end cap |
| USDA | 29% | 41% | Eligible rural properties; income limits apply |
| General QM (ATR/QM) | N/A | No fixed cap | Price-based APR test vs APOR; lender must still consider DTI (CFPB, effective 2021) |
Sources Fannie Mae Selling Guide B3-6-02 — max DTI 36%/45%/50% (May 2026), HUD FHA Handbook 4000.1 — manual ratios 31%/43% and compensating factors, 38 CFR § 36.4340 — VA 41% DTI standard, USDA HB-1-3555 Ch. 11 — 29% PITI / 41% total debt, CFPB — General QM final rule (Dec. 29, 2020). Checked October 2026.
These thresholds are guidelines, not absolute ceilings. Lenders can make exceptions when you have compensating factors: large cash reserves (6+ months of payments), excellent credit above 740, a substantial down payment (20%+), or stable employment history of 5+ years. However, staying within these ranges ensures you qualify for the most competitive rates and widest range of products. Check your Mortgage Calculator to model payments at different price points that keep you within your DTI limits.
Case Study: Adriana and Kevin Apply for Their First Home
Adriana, a 31-year-old registered nurse in Charlotte, NC, earns $5,500/month gross. Her fiance Kevin, a high school teacher, earns $4,000/month. Their combined gross monthly income is $9,500. They want to buy a home priced at $375,000 with 10% down ($37,500), financing $337,500 at 7.40% interest over 30 years (Freddie Mac PMMS average as of October 15, 2026).
Their estimated monthly housing payment (PITI): $2,337 for principal and interest (7.40% on $337,500 over 30 years per Freddie Mac PMMS as of Oct. 15, 2026), $312 for property taxes, $125 for homeowners insurance, and $95 for PMI (since they are putting less than 20% down). Total housing cost: $2,869/month.
Their existing monthly debts:
| Debt | Monthly Payment | Balance |
|---|---|---|
| Adriana's car payment | $385 | $14,200 |
| Kevin's student loans | $290 | $28,000 |
| Credit card minimums (combined) | $175 | $6,800 |
| Total non-housing debt | $850 |
Front-end DTI: $2,869 / $9,500 = 30.2% — above the common 28% conventional housing guideline but within FHA's 31% manual limit.
Back-end DTI: ($2,869 + $850) / $9,500 = $3,719 / $9,500 = 39.1% — above the 36% manual conventional limit and closer to FHA's 43% ceiling.
With a conventional loan, Adriana and Kevin exceed the 36% manual back-end threshold but might still qualify up to 45% with strong credit and reserves under Fannie Mae's Eligibility Matrix. Assume their file includes a 0.25 percentage-point loan-level pricing adjustment versus a cleaner 32% DTI profile — on this loan size that adds about $20,800 in interest over 30 years (CalcWise estimate at 7.40% vs 7.65% note rate).
If they pay off the $6,800 credit card balance before applying — eliminating $175/month — their back-end DTI drops to 37.3%, moving them closer to the standard manual tier and avoiding that pricing hit. The $6,800 payoff yields about a 3x return in avoided mortgage interest in this scenario. This is why reducing small debts before a mortgage application can have an outsized financial impact. Use our Home Affordability Calculator to see exactly how debt reduction changes your maximum qualifying home price.
Sources Freddie Mac — PMMS 30-year fixed 7.40% (Oct. 15, 2026), Fannie Mae Selling Guide B3-6-02 — manual/DU DTI limits. Checked October 2026. Case study PITI uses the PMMS note rate; your rate and LLPAs will differ.
Maximum Debt Capacity by Income Level
The following table shows how much monthly debt you can carry at each DTI threshold for different gross income levels. These numbers represent total capacity — subtract your existing non-housing debts to find your available housing budget:
| Gross Monthly Income | Max Housing at 28% | Max Total Debt at 36% | Max Total Debt at 43% | Max Total Debt at 50% |
|---|---|---|---|---|
| $4,000 | $1,120 | $1,440 | $1,720 | $2,000 |
| $6,000 | $1,680 | $2,160 | $2,580 | $3,000 |
| $8,000 | $2,240 | $2,880 | $3,440 | $4,000 |
| $10,000 | $2,800 | $3,600 | $4,300 | $5,000 |
| $12,500 | $3,500 | $4,500 | $5,375 | $6,250 |
| $15,000 | $4,200 | $5,400 | $6,450 | $7,500 |
The gap between 36% and 43% widens at higher incomes. At $10,000/month, that 7-percentage-point spread represents $700/month in additional debt capacity — enough to cover a car payment and student loans. However, stretching to 43% leaves far less cushion for emergencies, lifestyle expenses, and retirement savings. Financial advisors generally recommend keeping back-end DTI below 35% for long-term financial health, even if lenders will approve higher. See how your budget breaks down with our 50/30/20 Budget Calculator to understand whether stretching your DTI leaves enough for savings and discretionary spending.
6 Strategies to Lower Your DTI Before a Mortgage Application
1. Pay off high-minimum debts first. Target debts with the largest monthly payments relative to their balance. Paying off a $3,500 credit card with a $150/month minimum has the same DTI impact as earning $417 more per month (at 36% threshold). A $400/month car payment with 8 months remaining can be eliminated for $3,200, freeing significant DTI capacity. Prioritize by monthly payment size, not by interest rate or balance, when your immediate goal is mortgage qualification.
2. Increase your documented income. Overtime, bonuses, commissions, and side income count if you can demonstrate 2 years of consistent earning history. A documented side income of $600/month increases your gross income from $6,000 to $6,600, dropping a 38% DTI to 34.5%. Ask your employer about overtime opportunities 12 to 24 months before you plan to apply. For freelance income, ensure it appears on your last two tax returns.
3. Avoid new debt in the 6-12 months before applying. Every new loan or credit card balance adds to your monthly obligations. Do not finance furniture, a new car, or make large purchases on credit. Even a $5,000 personal loan at $150/month can push you from 35% to 37.5% DTI on a $6,000 income.
4. Consolidate debts to lower monthly payments. Refinancing a car loan from a 4-year term to a 6-year term reduces the monthly payment, though it increases total interest. If the priority is qualifying for a mortgage, the reduced monthly payment may be worth the trade-off. A $20,000 auto loan at 6.5% drops from $475/month (4-year) to $337/month (6-year), freeing $138/month in DTI.
5. Add a co-borrower. A spouse or partner's income increases the denominator in the DTI formula. A couple earning $4,500 and $5,500 individually has DTI calculated on $10,000 combined, giving them substantially more borrowing power than either person alone. However, the co-borrower's debts are also included, so this strategy works best when the co-borrower has minimal existing obligations.
6. Request a credit card minimum payment reduction. Some credit card issuers will lower your minimum payment if you have a strong payment history. Reducing a minimum from $200 to $125 on a $6,000 balance saves $75/month in DTI — a small change that can be the difference between approval and denial. This does not affect your balance or interest rate.
DTI vs. Credit Score: How Lenders Weigh Each Factor
Both DTI and credit score are critical, but they measure fundamentally different things. Your credit score is backward-looking — it reflects how reliably you have repaid debts in the past based on payment history, utilization, length of credit history, and credit mix. Your DTI is forward-looking — it measures how much of your current income is committed to debt, indicating your capacity to take on more.
You can have a 780 credit score and be denied a mortgage if your DTI is 55%. Conversely, a borrower with a 680 credit score and 25% DTI may qualify more easily than someone with 750 credit and 44% DTI. In practice, lenders use both together in a matrix: strong credit can compensate for slightly elevated DTI (up to 3-5 percentage points above standard thresholds), and low DTI can partially offset a lower credit score.
The most competitive mortgage terms go to borrowers with both a credit score above 740 and a back-end DTI below 36%. This combination qualifies you for the best rates, lowest PMI premiums, and widest selection of loan products. Use our Mortgage Calculator to model the rate you are likely to receive at different DTI levels and see the total cost difference over your loan term.
Common DTI Calculation Mistakes to Avoid
- Using net income instead of gross — Lenders always calculate with pre-tax income. Using take-home pay inflates your apparent DTI. An $85,000 annual salary is $7,083/month gross, not the $5,200 that may hit your bank account after taxes, 401(k), and insurance.
- Forgetting co-signed loans — If you co-signed a family member's car loan or student loan, that payment appears on your credit report and counts toward your DTI, even if the other person makes every payment. The only way to remove it is to refinance the loan in the other person's name alone.
- Ignoring deferred student loans — Many borrowers assume deferred loans do not count. Fannie Mae generally imputes 1% of the outstanding balance (Freddie Mac uses 0.5% or more depending on the credit report). A $50,000 deferred balance adds $250 to $500/month to your DTI.
- Counting non-debt expenses — Utilities, groceries, subscriptions, gas, and childcare are not debts. Only fixed monthly obligations that appear on your credit report (plus proposed housing costs) count toward DTI.
- Using the wrong credit card number — Lenders use the minimum payment due from your credit report, not your full balance or what you actually pay. Check your credit report to see the reported minimum.
Check Your Debt-to-Income Ratio
Use our free calculator to see your front-end and back-end DTI, lender qualification thresholds, and how much room you have to borrow.
Open Debt-to-Income CalculatorFrequently Asked Questions
What is a good debt-to-income ratio for a mortgage?
A back-end debt-to-income ratio of 36% or lower is the standard benchmark for manually underwritten conventional loans (Fannie Mae). Desktop Underwriter (DU) conventional loans may go up to 50% when the automated risk assessment approves. A front-end DTI of 28% or less for housing costs alone is a common conventional guideline. Below 20% back-end DTI is excellent and gives you the most loan options. FHA manual underwriting allows 31%/43% by default, and up to 40%/50% with documented compensating factors per HUD Handbook 4000.1.
What debts are included in the DTI calculation?
Lenders include all recurring monthly obligations that appear on your credit report plus housing costs. This covers mortgage or rent payments, property taxes, homeowners insurance, car loan payments, student loan payments, credit card minimum payments, personal loans, child support, alimony, and co-signed loan obligations. Utilities, groceries, streaming subscriptions, gas, and insurance premiums other than homeowners are not included. For credit cards, lenders use the minimum payment due, not your full balance or the amount you actually pay each month.
How do I calculate my debt-to-income ratio?
Divide your total monthly debt payments by your gross monthly income (before taxes) and multiply by 100 to get a percentage. For example, if you earn $7,000 per month gross and pay $2,100 in total monthly debts including housing, your DTI is $2,100 divided by $7,000 times 100, which equals 30%. Lenders calculate two versions: front-end DTI uses only housing costs, and back-end DTI uses all debt payments. Always use pre-tax income, not take-home pay.
Can I get a mortgage with a 45% debt-to-income ratio?
It depends on the program. Fannie Mae allows up to 45% back-end DTI on manually underwritten conventional loans when you meet Eligibility Matrix credit and reserve requirements, and up to 50% on DU-approved loans. FHA manual underwriting tops out at 43% back-end (50% with compensating factors). VA uses a 41% DTI guideline but weighs residual income heavily. A 45% DTI leaves minimal cushion, so reducing debt before applying is still wise.
Does my DTI affect my interest rate?
Yes, indirectly. DTI is primarily a qualification metric, but higher ratios limit you to programs with tighter automated approvals and can pair with other risk factors in loan-level price adjustments. A borrower who barely exceeds Fannie Mae's 36% manual threshold may still qualify at 45% but with less rate flexibility than someone at 30% back-end DTI. On a $337,500 loan at Freddie Mac's 7.40% PMMS average (Oct. 15, 2026), even a 0.25 percentage-point rate increase adds roughly $20,800 in interest over 30 years — one reason paying down small debts before applying can pay off.