How This Debt Payoff Calculator Works
Enter your current debt balance, interest rate, and monthly payment to see when you'll be debt-free. Then add an extra payment amount to see how much faster you could eliminate your debt and how much interest you'd save.
Debt Payoff Strategies
Two popular approaches to paying off multiple debts:
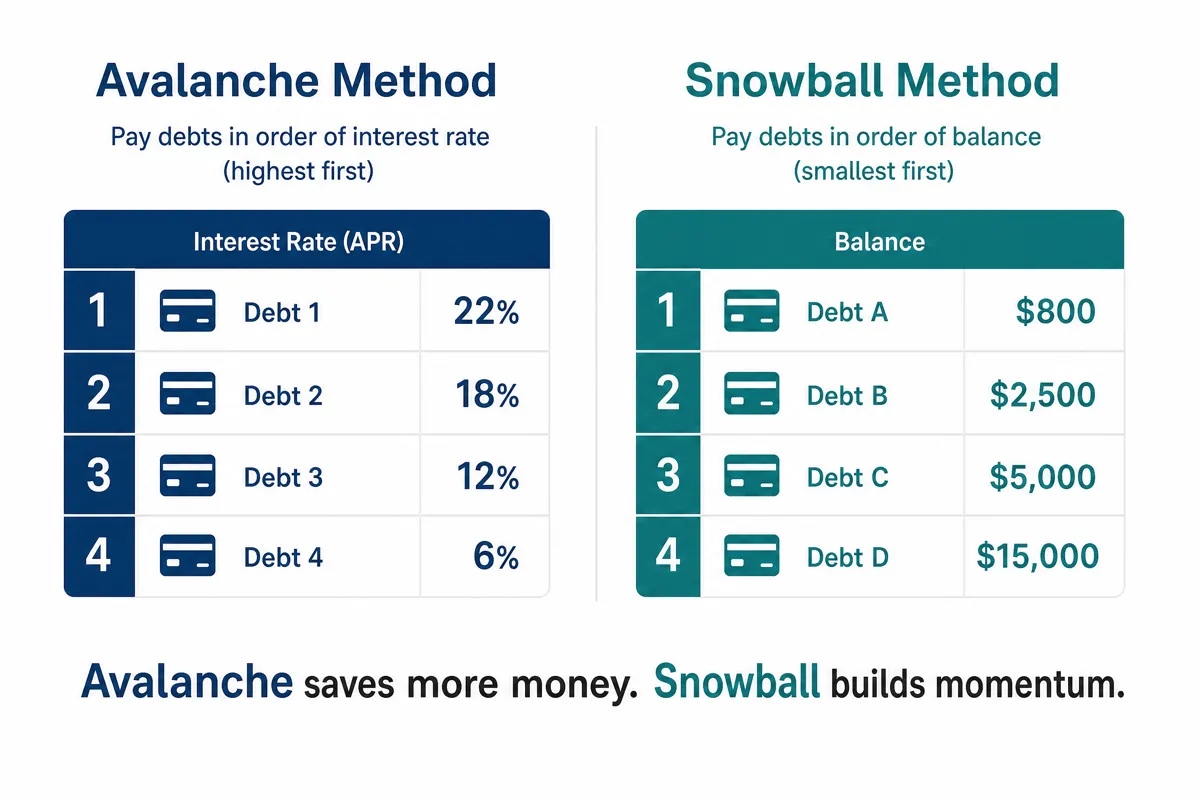
The Avalanche Method (Saves the Most Money)
Pay minimums on all debts, then put every extra dollar toward the debt with the highest interest rate. Once that's paid off, move to the next highest rate. This method minimizes total interest paid and is mathematically optimal.
The Snowball Method (Best for Motivation)
Pay minimums on all debts, then put extra money toward the smallest balance first. Clearing a small balance frees its minimum payment for the next target, which can keep you motivated when the math-heavy avalanche method feels slow.
Learn the full comparison in our guide: Debt Avalanche vs Snowball: Which Gets You Debt-Free Faster?
Case Study: Avalanche vs Snowball on $28,000 of Debt
James, a 35-year-old engineer, owes $28,000 across three accounts: a $12,000 credit card at 22.36% APR (near the Fed G.19 assessed-interest average, $240 minimum at 2%), a $6,000 store card at 19.99% APR ($120 minimum), and a $10,000 auto loan at 7.54% APR (near the G.19 60-month new-car bank average, $198 minimum). His total minimums are about $558 per month. After trimming dining and subscriptions, he frees $400 extra and commits $958 per month to debt payoff.
Source Federal Reserve G.19 Consumer Credit (Aug. 2026 data, released Oct. 7, 2026). Checked October 2026. Credit card APR uses G.19 accounts assessed interest (22.36%, August 2026). Auto rate is illustrative near the G.19 commercial-bank 60-month new-car average (7.54%, August 2026).
Using the avalanche method, James attacks the highest-APR card first while paying minimums elsewhere, then rolls freed payments down the rate ladder. That approach minimizes total interest versus snowball order on the same $958 monthly pool. Either structured method beats paying minimums only on revolving debt at 22.36% APR, where interest-plus-1% minimums can keep balances for decades. Run your own balances in this calculator, or compare consolidation offers with our Loan Comparison Calculator.
The True Cost of Minimum Payments
Credit card minimums are set low relative to the debt. A common formula, printed in cardmember agreements, is the larger of $25 or 1% of the balance plus that month's interest, so little of each payment reduces principal and the debt lasts longer.
Example: A $10,000 credit card balance at 22.36% APR with interest-plus-1% minimums (a $286 first payment) takes about 300 months (25 years) to pay off and costs about $17,558 in interest. Increasing to a fixed $300/month payment clears the same balance in 53 months with about $5,771 in total interest.
For credit card-specific strategies, try our Credit Card Payoff Calculator which models minimum payments vs. fixed payments, and read How to Pay Off Credit Card Debt Fast for a month-by-month action plan.
How Extra Payments Reduce Interest
Every extra dollar goes directly to reducing your principal balance. With less principal, the next month's interest charge is lower, which means more of your regular payment goes to principal too. This creates an accelerating payoff effect:
- Lower balance → less interest accrues
- Less interest → more of your payment reduces balance
- Faster balance reduction → even less interest next month
Even $50 or $100 extra per month can save thousands in interest and years off your debt timeline.
Where to Find Extra Money for Debt Payoff
- Audit subscriptions: cancel unused streaming, gym, or app charges — even $75/month redirected to debt cuts interest on a 22% balance.
- Side income: freelancing, selling unused items, or a part-time gig. Direct 100% of extra income to debt.
- Tax refund or bonus: a single $2,000 lump sum on a $15,000 balance at 22.36% APR can shave several months off a fixed $400/month plan.
- Negotiate rates: call your credit card company and ask for a lower APR. A 3-point drop on a $10,000 balance saves hundreds per year in interest.
- Balance transfer: a 0% APR promotional card gives you 12-21 months of interest-free payoff time (watch for transfer fees).
Frequently Asked Questions
Should I save or pay off debt?
If your debt interest rate exceeds your savings rate (which it almost always does for credit cards), prioritize debt payoff. Every dollar of debt at 20% costs you more than a dollar saved at 5% earns. The exception: maintain a small emergency fund ($1,000-$2,000) so unexpected expenses don't force you back into debt.
Once you're debt-free, start building wealth with our Savings Goal Calculator.
Does paying off debt improve my credit score?
Yes, significantly. Reducing your credit utilization ratio (how much of your available credit you're using) is one of the fastest ways to boost your score. Going from 80% utilization to 30% can improve your score by 50-100 points within a billing cycle.
What about debt consolidation?
Consolidation loans make sense if you can get a significantly lower interest rate and you're committed to not accumulating new debt. They simplify multiple payments into one and can reduce total interest. However, they don't solve the spending habits that created the debt.
Which debts should I pay off first if rates are similar?
When two debts sit within 1-2 percentage points of each other (for example, 18.9% vs 19.5%), the dollar difference in interest is small. In that case, snowball order — smallest balance first — often finishes one account 2-3 months sooner and frees a minimum payment you can roll into the next debt. If one rate is 5+ points higher (22% vs 7% on a car loan), avalanche almost always wins by hundreds of dollars.
How do I stay motivated during a long payoff?
Set milestone targets every $2,500-$5,000 of progress and track your "interest saved to date" in this calculator each month. James in our case study above celebrated each paid-off statement with a $20 coffee, not a $200 dinner — small rewards that do not add new balances. Pair that habit with automating the extra $400 on payday so the money never sits in checking where it is easy to spend.