Guides / Debt Strategy
Debt Avalanche vs Snowball Method: Which Gets You Debt-Free Faster?
You owe $38,000 across three loans and can spare $400 a month beyond minimum payments. Two proven strategies — avalanche and snowball — will get you to zero, but they take different routes, cost different amounts in interest, and feel very different along the way. This guide runs the exact numbers so you can choose the method that actually works for your situation.
Last updated: October 2026
TL;DR - Quick Answer
- Debt avalanche (highest rate first): Saves about $108 in interest on a typical $38,000 portfolio — the math winner whenever high-rate debts dominate
- Debt snowball (smallest balance first): Costs slightly more but delivers faster visible wins, which helps people who have quit debt plans before
- The real gap: On $38,000 with $400/month extra, avalanche takes 44 months and costs $6,267 in interest; snowball takes 44 months and costs $6,375
- Best hybrid: Avalanche for anything above 15% APR, snowball for balances under $3,000
Use our Debt Payoff Calculator and Credit Card Payoff Calculator to model your exact debts.
How the Debt Avalanche and Snowball Methods Work
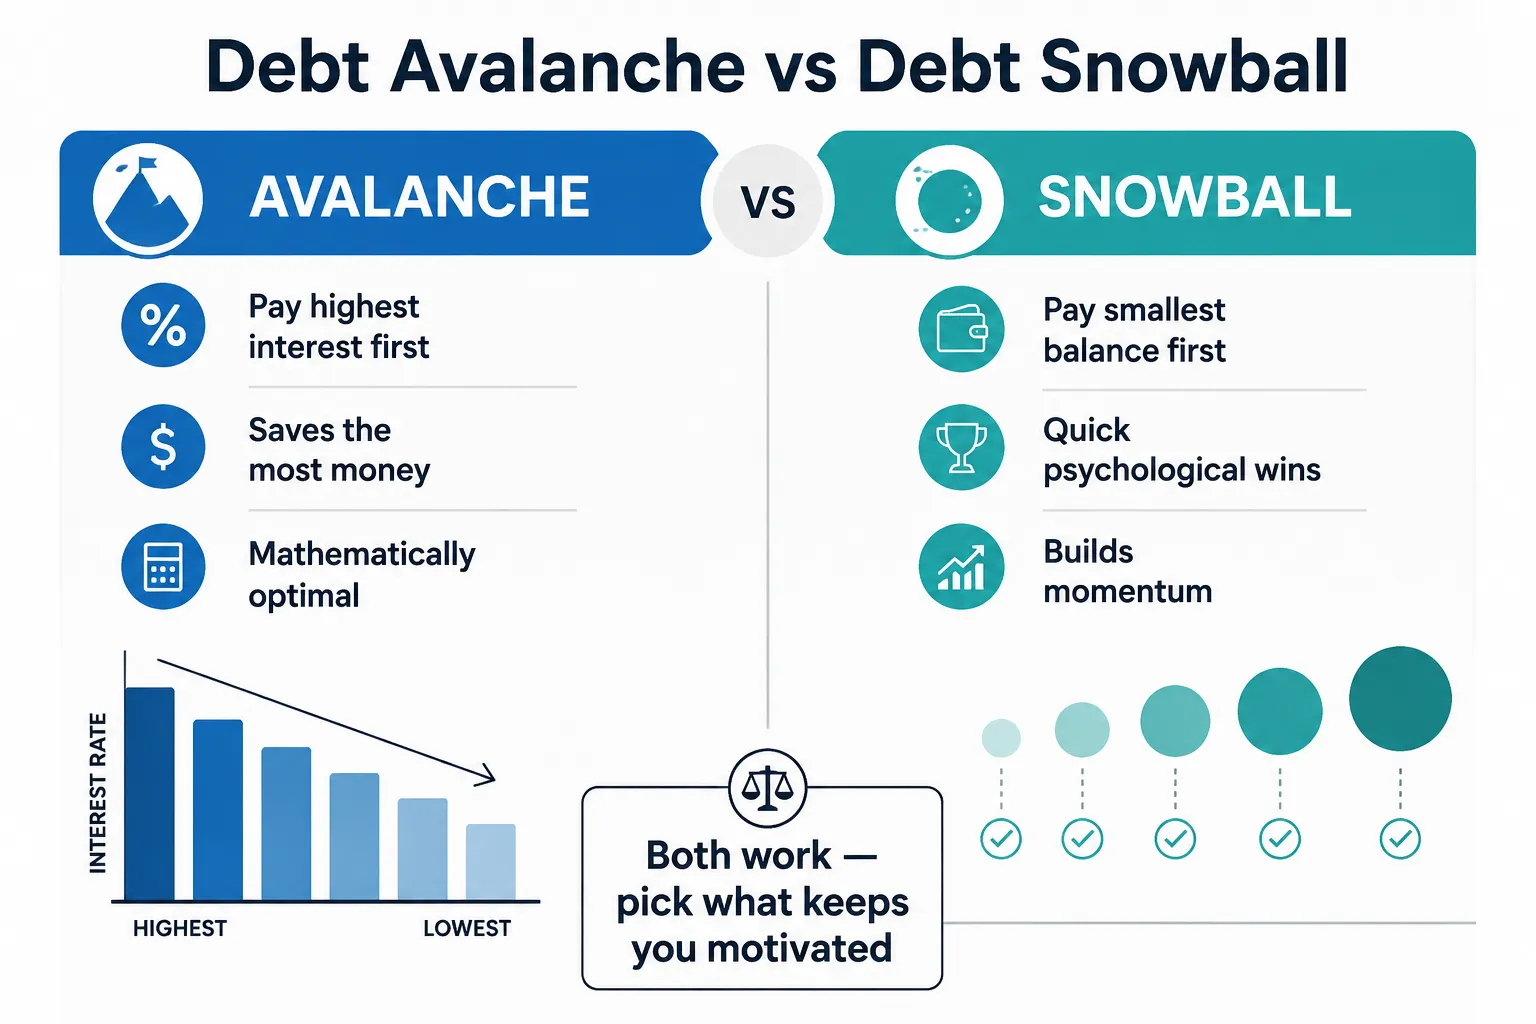
Both methods share the same foundation: pay the minimum on every debt, then throw every extra dollar at one target debt until it is gone. When a debt is eliminated, roll its payment into the next target. The only difference is which debt you target first — and that single choice changes your timeline, total interest, and day-to-day motivation.
The Debt Avalanche Method
Avalanche prioritizes the debt with the highest interest rate, regardless of balance size. The logic is straightforward: every dollar applied to a 22.36% credit card (the Federal Reserve G.19 average for accounts assessed interest as of August 2026) saves you $0.224 per year in future interest, while a dollar on a 6.52% undergraduate federal student loan saves only $0.065. You always attack the most expensive debt first.
The formula for monthly interest on any debt is:
On an $8,500 credit card at 22.36% APR, monthly interest is $158.38. On a $14,500 student loan at 6.52%, it is $78.78. Avalanche sends your extra $400/month to the credit card first, eliminating $158.38 in monthly interest charges as fast as possible.
The Debt Snowball Method
Snowball prioritizes the smallest balance, regardless of interest rate. You pay minimums on everything, then direct all extra money to the debt with the lowest dollar amount. When that balance hits $0, you roll its entire payment — minimum plus extra — into the next-smallest debt.
The snowball payment escalation works like this:
If your smallest debt has a $170 minimum and you add $400 extra, you pay $570/month until it is gone. When eliminated, that entire $570 rolls to the next-smallest debt, on top of its existing minimum. Each elimination creates a larger payment snowball rolling downhill toward the final debt.
Head-to-Head: $38,000 Debt Portfolio
Here is a realistic three-debt portfolio totaling $38,000, with $614/month in minimum payments and $400/month in extra cash ($1,014 total monthly budget). Both methods use identical total payments — only the order changes.
| Debt | Balance | Rate | Min Payment |
|---|---|---|---|
| Credit card | $8,500 | 22.36% | $170 |
| Car loan | $15,000 | 7.54% | $294 |
| Student loan | $14,500 | 6.52% | $150 |
| Total | $38,000 | — | $614 |
| Metric | Avalanche | Snowball |
|---|---|---|
| Payoff order | Credit card (22.36%) → Car (7.54%) → Student (6.52%) | Credit card ($8,500) → Student ($14,500) → Car ($15,000) |
| First debt eliminated | Month 18 (credit card) | Month 18 (credit card) |
| Second debt eliminated | Month 32 (car loan) | Month 37 (student loan) |
| Debt-free date | Month 44 | Month 44 |
| Total interest paid | $6,267 | $6,375 |
| Interest difference | Saves $108 | Costs $108 more |
| Total amount paid | $44,267 | $44,375 |
*Assumes $400/month extra on top of $614 in minimum payments ($1,014 total). Credit card APR reflects the 22.36% G.19 average for accounts assessed interest (August 2026, release Oct. 7, 2026); car and student rates reflect G.19 and 2026-27 federal undergraduate loan rates. Calculations use standard monthly compounding with rolled minimum payments. Payoff table figures recomputed October 2026 — use our calculators for your exact debts.
Sources Federal Reserve — G.19 Consumer Credit terms of credit (Aug. 2026, Oct. 7, 2026 release), Federal Student Aid — Direct Loan rates 2026-27 (June 4, 2026). Checked October 2026.
Key Insight
Both methods eliminate the $8,500 credit card in month 18 because it is both the highest-rate and smallest-balance debt. The divergence happens next: avalanche targets the 7.54% car loan while snowball targets the 6.52% student loan. That rate-order difference on similar $14,500-$15,000 balances accounts for the $108 interest gap even though both portfolios become debt-free in month 44.
Case Study: Maria, 31, $70K Salary in Chicago
Her Situation
- Gross salary: $70,000/year ($4,375/month take-home)
- Total debt: $24,000 across 4 accounts
- Minimum payments: $490/month
- Extra available: $350/month
- Total debt budget: $840/month (19.2% of take-home)
- No employer 401(k) match (already contributing 4%)
Her 4 Debts
- Store credit card: $3,200 at 26.49% ($64 min)
- Visa card: $1,800 at 21.99% ($36 min)
- Personal loan: $6,600 at 11.9% ($145 min)
- Car loan: $12,400 at 7.8% ($245 min)
Avalanche: First 6 Months (Highest Rate First)
Maria targets the 26.49% store card first, paying $64 minimum + $350 extra = $414/month.
| Month | Store CC | Visa | Personal | Car | Total Debt |
|---|---|---|---|---|---|
| Start | $3,200 | $1,800 | $6,600 | $12,400 | $24,000 |
| 1 | $2,857 | $1,797 | $6,520 | $12,236 | $23,410 |
| 2 | $2,506 | $1,794 | $6,440 | $12,070 | $22,810 |
| 3 | $2,147 | $1,791 | $6,359 | $11,904 | $22,201 |
| 4 | $1,780 | $1,788 | $6,277 | $11,736 | $21,581 |
| 5 | $1,406 | $1,784 | $6,194 | $11,567 | $20,951 |
| 6 | $1,023 | $1,781 | $6,111 | $11,397 | $20,312 |
After 6 months: $3,688 paid down (15.4% of total debt). Store card on track to clear by month 9. Total interest paid so far: approximately $1,350.
Snowball: First 6 Months (Smallest Balance First)
Maria targets the $1,800 Visa first ($36 min + $350 extra = $386/month), even though the store card has a higher rate.
| Month | Visa | Store CC | Personal | Car | Total Debt |
|---|---|---|---|---|---|
| Start | $1,800 | $3,200 | $6,600 | $12,400 | $24,000 |
| 1 | $1,447 | $3,207 | $6,520 | $12,236 | $23,410 |
| 2 | $1,088 | $3,213 | $6,440 | $12,070 | $22,811 |
| 3 | $721 | $3,220 | $6,359 | $11,904 | $22,204 |
| 4 | $349 | $3,227 | $6,277 | $11,736 | $21,589 |
| 5 | $0 | $3,204 | $6,194 | $11,567 | $20,965 |
| 6 | — | $2,824 | $6,111 | $11,397 | $20,332 |
After 6 months: $3,668 paid down (15.3% of total debt). Visa eliminated in month 5 — Maria gets her first zero-balance win. Payment snowball increases to $450/month on store card (month 6). Total interest paid so far: approximately $1,370 ($20 more than avalanche).
Maria's Outcome
Avalanche clears all $24,000 in 33 months with $3,642 in total interest. Snowball also takes 33 months but costs $3,715 — about $73 more. Maria still chose snowball because she had abandoned two previous debt plans. Eliminating the $1,800 Visa in month 5 gave her the momentum to stay on track even though avalanche would have saved $73 in interest over the same timeline.
When to Use Avalanche vs Snowball
The right method depends less on the math and more on how you behave with money. Here is how to match the strategy to your personality and debt profile.
Choose Avalanche If You Are...
- Data-driven and disciplined. You track spreadsheets, check balances weekly, and stay motivated by watching interest charges shrink — not by closing accounts.
- Carrying high-rate credit card debt. If any debt exceeds 18% APR, avalanche savings become significant. On $15,000 at 22% or higher, avalanche vs snowball can differ by hundreds of dollars depending on your other balances.
- Already tried and stuck with a debt plan. If you have successfully paid off debt before, you do not need snowball's psychological crutch — take the mathematically optimal path.
- Facing a large rate spread. When your highest and lowest rates differ by 10+ points (for example, a store card above 24% APR versus a federal student loan near 6.5%), avalanche's advantage is largest.
Choose Snowball If You Are...
- Someone who has quit debt plans before. If willpower failed you in the past, the quick win of eliminating a $1,800 or $2,400 balance in 4-5 months can be the difference between finishing and giving up.
- Juggling 5+ small debts. Multiple accounts under $3,000 create decision fatigue. Snowball gives you a clear, simple rule: smallest first, always.
- Needing visible progress fast. Closing an account in month 5 (like Maria's Visa) feels dramatically different from watching a $3,200 balance slowly shrink on a single card.
- Dealing with similar interest rates. If all debts are within 2-3 percentage points of each other, the math difference between methods shrinks to $50-$100 — not worth sacrificing motivation over.
The Math vs Motivation Test
Ask yourself one question: "Have I started and abandoned a debt payoff plan in the last 3 years?" If yes, use snowball — the $100-$300 in extra interest is cheaper than another failed attempt that leaves you $24,000 in debt. If no, use avalanche and keep every dollar working for you.
Step-by-Step: How to Implement Each Method
Setting Up the Debt Avalanche
List every debt with balance, APR, and minimum payment
Include credit cards, car loans, personal loans, medical bills, and student loans. For $38,000 across 3 debts, your list might show $8,500 at 22.36%, $15,000 at 7.54%, and $14,500 at 6.52%.
Sort by interest rate, highest to lowest
Your avalanche order: 22.36% credit card first, 7.54% car loan second, 6.52% student loan last. Rate beats balance every time.
Pay minimums on all debts, extra on the top of the list
With $614 in minimums and $400 extra, send $570 to the credit card ($170 min + $400), $294 to the car, and $150 to the student loan. Total outflow: $1,014/month.
Roll payments forward when a debt is eliminated
When the credit card clears in month 18, redirect the full $570 to the car loan ($570 + $294 = $864/month). When the car clears, send $864 + $150 = $1,014 to the student loan until everything is zero.
Setting Up the Debt Snowball
List every debt with balance, APR, and minimum payment
Same starting list as avalanche — you need identical information. Do not skip any account, even a $400 medical bill at 0% interest.
Sort by balance, smallest to largest
Your snowball order: $8,500 credit card first, $14,500 student loan second, $15,000 car loan last. Balance beats rate every time.
Pay minimums on all debts, extra on the smallest balance
Same $1,014/month budget. Send $570 to the credit card, $150 to the student loan, and $294 to the car. The payment distribution looks identical to avalanche in month 1 — the difference appears when the first debt clears.
Celebrate each elimination and roll the snowball forward
When the credit card clears in month 18, roll $570 to the student loan ($570 + $150 = $720/month). When the student loan clears in month 37, roll $720 to the car ($720 + $294 = $1,014/month) until the final balance hits $0.
4 Mistakes That Derail Both Methods
Adding new debt while paying off old debt
Putting $400/month toward payoff while charging $300/month in new purchases on the same card is running on a treadmill. Cut up the card or freeze it in a block of ice. Use a debit card or cash for all spending until every balance reads $0.00.
Ignoring the emergency fund entirely
Sending 100% of savings to debt with $0 in the bank means one $800 car repair goes right back on a credit card at 22%+. Save $1,500-$2,500 first, then redirect the full $400/month to debt. The 2-month delay costs roughly $35 in extra interest — far less than an $800 relapse.
Paying only minimums on the target debt
The method only works if you add extra beyond the minimum. On an $8,500 credit card at 22.36%, paying just the $170 minimum takes about 12 years and costs roughly $16,200 in interest. Adding $570/month on that card ($170 minimum plus $400 extra) cuts that to 18 months and about $1,550 in interest. The extra payment is the entire strategy.
Switching methods mid-stream
Pick one method and commit for at least 6 months. Switching from avalanche to snowball in month 4 resets your mental accounting and often leads to abandoning the plan entirely. Run both scenarios in a calculator first, choose one, and execute.
Source Gal & McShane (Kellogg) — debt snowball account-closure study (JMR, 2012). Checked October 2026. Cited for snowball motivation research in the FAQ; payoff timelines above are CalcWise illustrations.
Run Your Debt Payoff Numbers
Every debt portfolio is different. Enter your exact balances, rates, and monthly budget to see whether avalanche or snowball gets you debt-free faster — and how much each method costs in interest.
Frequently Asked Questions
Which saves more money: debt avalanche or debt snowball?
The debt avalanche saves more money in virtually every scenario because you eliminate high-interest debt first. In a typical $38,000 portfolio with $400/month in extra payments, avalanche saves about $108 in total interest versus snowball (both methods share the same 44-month debt-free timeline when the highest-rate debt is also the smallest balance). The gap widens as interest rate spreads increase — a portfolio with a 24% credit card and a 4% student loan can see avalanche save hundreds of dollars over snowball.
Is the debt snowball method ever better than avalanche?
The snowball method can be better psychologically, not mathematically. If you have multiple small debts under $2,000 and need quick wins to stay motivated, snowball delivers visible progress faster. Research from Northwestern Kellogg found that consumers who paid off smaller balances first were more likely to eliminate their entire debt load, even though they paid slightly more interest. If you've quit debt payoff plans before, snowball's momentum may outweigh avalanche's math.
How much extra should I pay toward debt each month?
Aim for at least $200-$400 above minimum payments, or 10-15% of your take-home pay dedicated to debt elimination. On a $70,000 salary ($4,375/month take-home), that means $438-$656/month toward debt. Even $150/month extra cuts a 5-year payoff timeline to roughly 3.5 years on $38,000 of debt. Use our Debt Payoff Calculator to find the exact amount that hits your target date.
Should I pay off debt or build an emergency fund first?
Build a starter emergency fund of $1,500-$2,500 first, then attack debt aggressively. Without any buffer, one car repair or medical bill sends you right back to credit cards. Once you have that cushion, redirect every extra dollar to debt while maintaining minimum payments. After becoming debt-free, grow the emergency fund to 3-6 months of expenses ($13,000-$26,000 for most households).
Can I combine avalanche and snowball into a hybrid method?
Yes, and many financial coaches recommend it. One approach: use snowball for debts under $3,000 (quick wins), then switch to avalanche for everything above that threshold. Another hybrid: avalanche for all debts above 15% APR (credit cards), snowball order for debts under 8%. This captures avalanche's savings on expensive debt while keeping snowball's motivational wins on manageable balances.
Should I use a debt consolidation loan instead of avalanche or snowball?
It depends on the rate you qualify for. If you can consolidate $38,000 in mixed-rate debt into a single personal loan at 9-11% APR, you simplify payments and potentially lower your blended rate. However, as of mid-October 2026 the latest Federal Reserve G.19 release (August 2026 data) shows the average bank rate on 24-month personal loans at 11.90%, which only helps if your current blended rate exceeds that. Also budget for origination fees (often 1-8% of the loan amount on marketplace personal loans) — a 5% fee on $38,000 adds $1,900 in costs upfront. Run both scenarios in our Debt Payoff Calculator before committing.
Related Guides
How to Pay Off $10,000 in Credit Card Debt: 5 Proven Strategies
Pay off $10,000 in credit card debt with 5 proven strategies. Compare timelines, total interest, and see which approach fits your situation best.
The 50/30/20 Budget Rule Explained with Real Examples
Learn the 50/30/20 budget rule with real examples at $50K, $75K, and $100K income. Includes a case study, category breakdowns, and when the rule doesn't work.