Guides / Investing Basics
Compound Interest: 5 Real-Life Examples That Show Its Power
Compound interest is the reason a modest monthly contribution can turn into a seven-figure retirement account — and the reason a $5,000 credit card balance can cost you nearly $9,000 to repay at today's average APR. These five compound interest examples from real life show exactly how the math plays out with specific dollar amounts, so you can see where compounding helps you and where it works against you.
Last updated: October 2026
TL;DR - Quick Answer
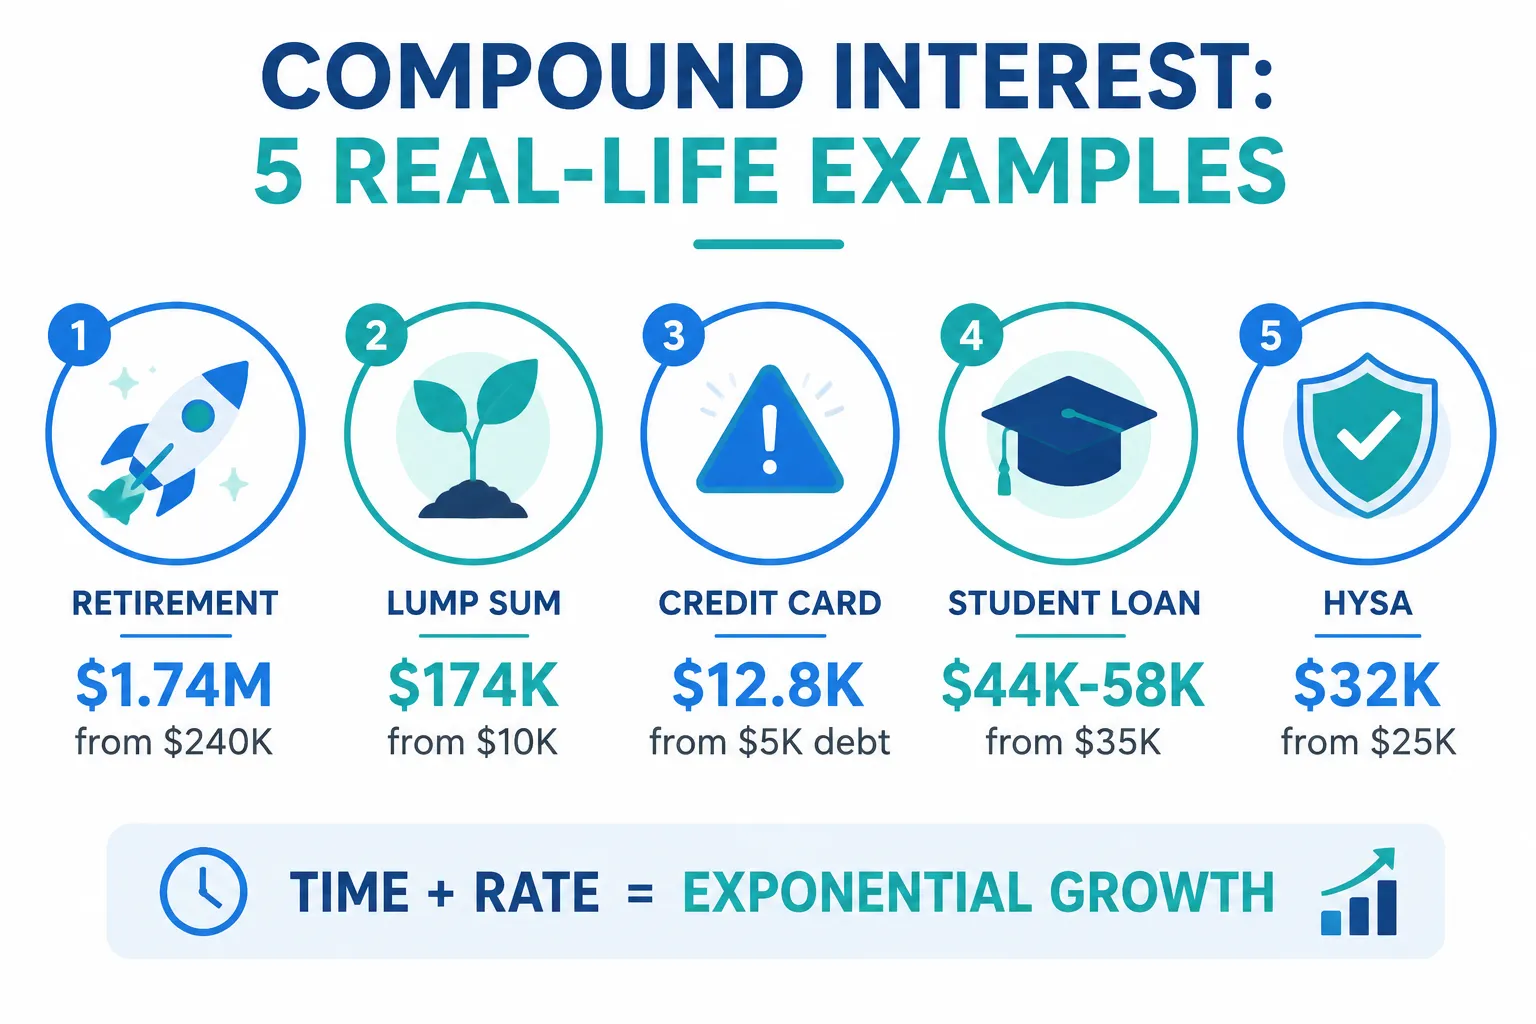
- Retirement: $500/month from age 25 to 65 at 8% grows to $1.74 million on $240,000 contributed
- Lump sum: $10,000 invested once at 10% for 30 years becomes $174,494
- Credit card debt: $5,000 at 22.36% with $130/month payments costs about $8,840 total — compound interest in reverse
- Student loans: Repayment plan choice changes total interest from about $10,600 to about $31,100 on the same $35,000 balance
- High-yield savings: $25,000 at 4.25% APY for 5 years grows to about $30,908 with FDIC insurance
Model your own scenarios with our Compound Interest Calculator, Retirement Calculator, and Savings Goal Calculator.
The Compound Interest Formula Explained
Every example in this guide uses the same underlying formula. Compound interest means you earn returns not just on your original principal, but on the accumulated interest from prior periods. The standard formula is:
A = P(1 + r/n)nt
- A = final amount (what you end up with)
- P = principal (starting balance)
- r = annual interest rate (as a decimal, so 8% = 0.08)
- n = number of times interest compounds per year (12 for monthly, 365 for daily)
- t = time in years
For recurring monthly contributions — like the retirement example below — the formula extends to include a payment stream. But the core idea is identical: each period's growth becomes part of the base for the next period. Over decades, that snowball effect dominates the outcome far more than the original deposit amount.
Albert Einstein reportedly called compound interest the eighth wonder of the world. Whether or not he actually said it, the math is undeniable — and the five examples below show why.
Example 1: Monthly Retirement Contributions ($500/Month, Age 25 to 65)
This is the compound interest example that personal finance advisors cite most often — and for good reason. A 25-year-old who invests $500 every month into a tax-advantaged account (401(k) or IRA) earning an average 8% annual return builds substantial wealth without ever needing a large lump sum.
The Inputs
- Monthly contribution: $500
- Starting age: 25
- Retirement age: 65 (40 years)
- Average annual return: 8%
- Compounding: monthly
The Outcome
- Total contributed: $240,000
- Investment growth: $1,500,504
- Final balance: $1,745,504
- Growth multiplier: 7.3x your contributions
Notice what happened: you deposited $240,000 over 40 years — roughly $6,000 per year — and compound growth added $1.5 million on top. More than 86% of the final balance came from returns, not from money you saved out of pocket. That is the power of compound interest over a long timeline.
The 8% return assumption is a round planning figure — not a forecast. Historically, the S&P 500 returned about 10% per year (geometric mean, nominal, with dividends reinvested) from 1928 through 2024 in NYU Stern's Damodaran dataset (Tier-2 historical data — about $100 grew to $982,818 over that span). Calendar years vary widely — for example −36.6% in 2008 and +32.2% in 2013 in that series. Use our Retirement Calculator to adjust the contribution amount, return rate, and timeline for your situation.
Source NYU Stern (Damodaran), S&P 500 historical returns incl. dividends, 1928–2024 (Jan. 2026 table). Checked October 2026. Past performance is not a guarantee of future results.
Example 2: One-Time $10,000 Investment at 10% for 30 Years
Not everyone can commit to monthly contributions from day one. Sometimes you receive a windfall — an inheritance, a bonus, or proceeds from selling a home — and invest it once. Here is what happens when you leave that money alone to compound.
The Inputs
- Initial investment: $10,000
- Annual return: 10%
- Time horizon: 30 years
- Additional contributions: $0
The Outcome
- Total contributed: $10,000
- Investment growth: $164,494
- Final balance: $174,494
- Growth multiplier: 17.4x your original deposit
Using the formula directly: A = $10,000 × (1.10)30 = $174,494. Your $10,000 doubles to $20,000 in about 7.2 years (Rule of 72), doubles again to $40,000 around year 14, and keeps accelerating from there. By year 30, the annual growth on the portfolio alone ($17,449 in the final year) exceeds the entire original investment.
This example illustrates why financial advisors emphasize investing windfalls rather than spending them. A $10,000 vacation today versus $174,494 at retirement is one of the starkest trade-offs in personal finance — and compound interest is the engine behind it.
Example 3: Credit Card Debt — $5,000 at 22.36% APR With $130/Month Payments
Compound interest is not always your friend. When you carry credit card debt, the bank applies the same compounding math — but the interest accrues against you. As of mid-October 2026, the Federal Reserve's latest G.19 release (August 2026 data) puts the average APR at 22.36% for accounts assessed interest and 21.19% for all accounts — up from about 21% in 2024. This is one of the most painful compound interest examples in real life because the rates are so high and minimum payments are designed to keep you in debt.
The Inputs
- Starting balance: $5,000
- APR: 22.36% (Fed avg., accounts assessed interest, Aug. 2026)
- Payment: $130/month (fixed for this illustration)
- Compounding: daily (standard for credit cards)
The Outcome
- Original balance: $5,000
- Total interest paid: about $3,840
- Total amount paid: about $8,840
- Time to pay off: approximately 5.7 years (68 months)
At 22.36% APR, your debt doubles in roughly 3.2 years if you make no payments (72 ÷ 22.36 ≈ 3.2). In the first month alone, $5,000 with daily compounding at 22.36% accrues about $93 in interest. A $130 payment sends roughly $37 toward principal that month; the cycle continues until the balance is gone.
The lesson is stark: every dollar you put toward this balance avoids compounding at 22.36% — a guaranteed return that few investments match after tax. If you have credit card debt and are also investing, you are effectively borrowing at 22%+ to earn single-digit stock returns. The math almost always favors paying the debt first. Use our Credit Card Payoff Calculator to see how much faster a fixed payment of $300 or $500 per month would eliminate this balance.
Source Federal Reserve, Consumer Credit G.19 — credit card plan rates (Aug. 2026 data, release Oct. 7, 2026). Checked October 2026. Payoff math assumes daily compounding and a fixed $130 monthly payment.
Example 4: Student Loans — $35,000 at 5.5% (Standard vs Income-Driven)
This example uses a 5.5% fixed APR — the federal Direct Loan rate for undergraduate loans first disbursed in 2023–24. New undergraduate loans first disbursed between July 1, 2026 and June 30, 2027 carry 6.52%, which on the same $35,000 and 10-year plan means $397.77 a month and $12,733 of interest (about $2,152 more than at 5.5%); run your own balance in the student loan calculator. Student loans demonstrate how the same principal and interest rate can produce wildly different total costs depending on your repayment plan. Compound interest still applies — but the timeline and payment structure determine whether you pay about $10,600 or about $31,100 in interest charges on the same $35,000 borrowed.
| Plan | Term | Monthly Payment | Total Interest | Total Paid |
|---|---|---|---|---|
| Standard Repayment | 10 years | $380/month | $10,581 | $45,581 |
| Income-Driven (20 years) | 20 years | $198/month (avg.) | $31,147* | $47,520 |
*Based on $35,000 at 5.5% fixed APR with monthly compounding. Standard plan uses the level payment that retires the loan in 10 years ($379.84/month, rounded to $380). Income-driven row assumes $198/month for 20 years; about $31,147 of that total flows to interest and roughly $18,600 in principal may remain for forgiveness programs such as PSLF. Actual IDR payments vary by income and plan.
The standard 10-year plan attacks the principal aggressively. Each month, a larger share of your $380 payment reduces the balance, which means less interest accrues in the next period — compound interest working in your favor when you pay down fast.
The income-driven plan lowers monthly payments to $198 on average, but the balance shrinks slowly. Interest continues compounding on a larger remaining balance for twice as long. You pay about $20,500 more in interest within your payments — even though the monthly payment feels more manageable. For borrowers who qualify for Public Service Loan Forgiveness (PSLF), the extended timeline may still make sense. For everyone else, the standard plan's lower total cost is compelling if the monthly payment fits your budget.
Source Federal Student Aid (June 4, 2026), GENERAL-26-33: Direct Loan rates for 2026–27 (6.52% undergraduate). Checked October 2026. Table math uses 5.5% to illustrate a fixed-rate borrower cohort; 2023–24 undergraduate Direct Loans were 5.50%. The 6.52% comparison is a level 10-year payment on $35,000.
Example 5: High-Yield Savings — $25,000 at 4.25% APY for 5 Years
Compound interest is not limited to the stock market. High-yield savings accounts (HYSAs) compound daily or monthly. As of mid-October 2026, Bankrate's top listed FDIC-insured HYSAs paid up to about 4.27% APY (Tier-2 survey), while the FDIC national average savings rate was 0.38% — and brick-and-mortar accounts often pay far less. This example uses 4.25% APY to show what a competitive online rate does to a lump sum.
The Inputs
- Initial deposit: $25,000
- APY: 4.25% (illustrative top-tier online rate)
- Time horizon: 5 years
- Compounding: monthly
- Additional contributions: $0
The Outcome
- Total deposited: $25,000
- Interest earned: $5,908
- Final balance: $30,908
- Effective annual gain: about $1,182/year
Compare that to a traditional brick-and-mortar savings account paying 0.01% APY: the same $25,000 earns about $13 over five years. The HYSA earns $5,908 — more than 450 times as much — because compound interest at a meaningful rate actually has room to work. This is why emergency funds and short-term savings goals belong in HYSAs, not checking accounts or under the mattress. See our High-Yield Savings vs CD Guide for a detailed comparison of where to park your cash in the current rate environment.
The trade-off is lower returns than the stock market. That same $25,000 at 8% over 5 years would reach approximately $36,734 — but with volatility and no guarantee. For money you need within 3-5 years (emergency fund, down payment, vacation fund), the HYSA's guaranteed $5,908 in interest is the right tool.
Sources FDIC, National Rates and Rate Caps — October 2026 (0.38% savings), Bankrate, Best high-yield savings accounts — October 2026 (Tier-2; up to 4.27% APY). Checked October 2026. Example growth assumes 4.25% APY with monthly compounding.
Side-by-Side Comparison: All Five Examples
This table summarizes every compound interest example from real life covered in this guide. Notice the pattern: longer timelines and higher rates amplify the gap between what you put in and what you end up with.
| Example | Rate | Time | You Put In | Final Value / Total Paid | Compounding Effect |
|---|---|---|---|---|---|
| Retirement ($500/mo) | 8% | 40 years | $240,000 | $1,745,504 | +$1,505,504 growth |
| Lump sum ($10,000) | 10% | 30 years | $10,000 | $174,494 | +$164,494 growth |
| Credit card debt | 22.36% | ~5.7 years | $5,000 borrowed | ~$8,840 paid | ~+$3,840 interest cost |
| Student loans (standard) | 5.5% | 10 years | $35,000 borrowed | $45,581 paid | +$10,581 interest cost |
| Student loans (IDR) | 5.5% | 20 years | $35,000 borrowed | $47,520 paid | ~+$31,147 interest cost |
| High-yield savings | 4.25% | 5 years | $25,000 | $30,908 | +$5,908 growth |
The Early Start Advantage: Age 25 vs Age 35
The single most important variable in compound interest is time. Waiting 10 years to start investing is not just 10 years of missed contributions — it is 10 years of lost compounding on every dollar you would have invested. Here is what happens when two people contribute the same $500 per month at 8%, but one starts at 25 and the other waits until 35.
| Starting Age | Years Investing | Total Contributed | Final Balance at 65 | Growth from Compounding |
|---|---|---|---|---|
| Age 25 | 40 years | $240,000 | $1,745,504 | $1,505,504 |
| Age 35 | 30 years | $180,000 | $745,180 | $565,180 |
| Difference | 10 years | $60,000 more | $1,000,324 more | $940,324 more |
The 25-year-old contributes only $60,000 more over those extra 10 years — but ends up with over $1 million more at retirement. The 35-year-old would need to contribute approximately $1,170 per month (more than double) to reach the same $1.74 million by age 65. Time is the one input you cannot buy back.
Key Insight
The first $120,000 the 25-year-old contributes (Years 1-20) grows to approximately $1.45 million by age 65 — about 12x. The last $120,000 contributed (Years 21-40) only reaches about $295,000 at 65 — about 2.5x. Early dollars have more time to compound, which is why starting now with any amount beats waiting for the "perfect" time to invest a larger sum.
The Rule of 72: Quick Mental Math for Doubling Time
You do not need a calculator to estimate how long compound interest takes to double your money. The Rule of 72 is a shortcut used by financial professionals for decades: divide 72 by the annual interest rate to get the approximate doubling time in years.
Doubling Time (years) = 72 ÷ Annual Interest Rate
| Interest Rate | Rule of 72 Estimate | Real-Life Context | $10,000 Becomes |
|---|---|---|---|
| 5% (HYSA) | 14.4 years | Emergency fund doubling | $20,000 |
| 8% (index fund) | 9 years | Retirement account growth | $20,000 |
| 10% (aggressive portfolio) | 7.2 years | Lump-sum investing | $20,000 |
| 22.36% (credit card) | 3.2 years | Debt doubling if unpaid | $20,000 owed |
Apply the rule to Example 2: $10,000 at 10% doubles to $20,000 in 7.2 years, doubles again to $40,000 in 14.4 years, and reaches $80,000 around year 21.6. Three doublings in roughly 22 years — and one more doubling in the remaining 8 years pushes the total to $174,494. The Rule of 72 is not perfectly precise (actual doubling at 10% takes 7.27 years), but it is close enough for planning and far faster than running the full compound interest formula.
Growth by Starting Amount
The five examples above cover different financial situations — but they all raise the same question: how much does your starting balance actually matter? The answer is less than most people think. With the same monthly contribution rate and return, a larger lump sum gives you a head start, but consistent contributions over 20-30 years drive the majority of the final balance in every scenario below.
$1,000 Start
Starting with just $1,000 and adding $100 per month at a 7% annual return for 30 years grows to approximately $130,000. Of that total, you contributed $37,000 out of pocket — the remaining $93,000 came entirely from compound growth. That is a 3.5x multiplier on money you actually saved, built from a modest four-figure starting point and a contribution smaller than most car payments.
The starting amount matters less than consistency. By year 10, the same account is worth roughly $19,000 — only $13,000 of which came from your contributions. The first decade establishes the compounding base; the last two decades are where growth accelerates. Someone who waits to save a $10,000 lump sum before investing would need nearly 8 years of $100/month contributions just to match what the $1,000 starter already accumulated — time that cannot be recovered.
$5,000 Start
A $5,000 starting balance with $200 per month at 7% over 20 years reaches approximately $124,000. You invested $53,000 total ($5,000 initial plus $48,000 in monthly contributions), and compound interest generated roughly $71,000 on top — more than the entire amount you put in. The $5,000 head start contributes meaningfully in the early years, but by year 15 the monthly deposits have outpaced the original lump sum in total dollars added.
This scenario mirrors a typical early-career investor: a small rollover from a previous 401(k), a signing bonus, or a year of aggressive saving before committing to regular contributions. The $200/month level is achievable on most household budgets and produces a six-figure portfolio in two decades without requiring exceptional returns or a large windfall to begin.
$10,000 Start
Investing $10,000 upfront and adding $500 per month at 7% for 20 years grows to approximately $301,000. Total out-of-pocket contributions reach $130,000 ($10,000 initial plus $120,000 in monthly deposits), with compound growth adding roughly $171,000. At this contribution level, the portfolio crosses $100,000 around year 9 and $200,000 around year 14 — milestones that feel distant at the start but arrive faster than linear math suggests.
By year 10, a critical tipping point arrives: annual investment growth on the portfolio (approximately $7,500) exceeds the $6,000 you contribute that year in monthly deposits. Your money is now working harder than you are. From this point forward, compound interest contributes more to the balance each year than your contributions — the hallmark of a mature compounding portfolio.
$100,000 Lump Sum
A $100,000 lump sum invested at 7% with $1,000 per month added for 20 years reaches approximately $925,000. You contribute $340,000 total ($100,000 initial plus $240,000 in monthly deposits), and compound interest accounts for roughly $585,000 — nearly twice what you put in. The large starting balance means compounding begins on six figures from day one, so even modest monthly additions amplify an already substantial base.
By year 10, the portfolio is worth approximately $374,000 and generates roughly $26,000 in annual growth — more than double the $12,000 you contribute that year. This scenario reflects someone who received an inheritance, sold a business, or rolled over a sizable retirement account and continues investing systematically. The lump sum provides immediate scale, but the $1,000/month discipline is what pushes the total toward seven figures.
| Starting Amount | Monthly Addition | Years | Final Balance | Total Contributed | Interest Earned |
|---|---|---|---|---|---|
| $1,000 | $100 | 30 | $130,114 | $37,000 | $93,114 |
| $5,000 | $200 | 20 | $124,379 | $53,000 | $71,379 |
| $10,000 | $500 | 20 | $300,851 | $130,000 | $170,851 |
| $100,000 | $1,000 | 20 | $924,801 | $340,000 | $584,801 |
*All scenarios assume 7% annual return with monthly compounding. Actual investment returns vary year to year.
How to Put Compound Interest to Work Today
Understanding compound interest is valuable, but the real payoff comes from acting on it. Here are three concrete steps you can take this week — each one leverages the compounding math covered above.
- Automate a $100/month investment. Even if you cannot start at $500/month, $100/month at 8% for 30 years grows to approximately $149,036. That is about $113,036 in compound growth on $36,000 contributed — a 4.1x multiplier. Open a brokerage account and set up auto-invest into a total market index fund. Read our Beginner's Guide to Investing with $1,000 for the exact steps.
- Move your emergency fund to a HYSA. If your $10,000 emergency fund is sitting in a checking account at 0.01%, moving it to a 4.25% HYSA (as of mid-October 2026 top-tier online rates) earns about $425 in the first year alone. Over 5 years, the HYSA produces about $2,363 in interest versus $5 in the checking account — a 470x difference for 15 minutes of setup.
- Attack high-APR debt before investing. If you owe $3,000 on a credit card at 22.36%, adding $200 above your minimum payment clears the balance in about 15 months and avoids thousands in interest versus paying minimums for years. That payoff is a guaranteed return at the card's APR — no stock market investment offers that with zero risk.
For those looking to build passive income through compounding, our dividend investing guide explains how DRIP reinvestment plans compound your dividends automatically — turning a $10,000 dividend portfolio into $26,500+ over 10 years at a 3% yield with 7% growth.
Sources BLS, Consumer Price Index Summary — September 2026 (3.7% over 12 months), U.S. Treasury, Daily Treasury Par Yield Curve CSV (10-year 5.15% on Oct. 19, 2026). Checked October 2026. Treasury yields move daily; CPI is the all-items CPI-U unless noted.
Run Your Own Numbers
Every financial situation is different. Use our free calculators to model compound interest on your savings, investments, debt, and retirement timeline with your actual numbers.
Frequently Asked Questions
What is a real-life example of compound interest working in your favor?
The clearest positive example is monthly retirement investing. Contributing $500 per month from age 25 to 65 at an 8% average annual return grows to approximately $1.74 million — even though you only deposited $240,000 out of pocket. The remaining $1.5 million comes entirely from compound growth on both your contributions and the returns they generate.
How does compound interest hurt you with credit card debt?
Credit cards compound interest against you daily or monthly. A $5,000 balance at 22.36% APR (the Federal Reserve’s August 2026 average for accounts assessed interest) with fixed payments of roughly $130/month takes about 5.7 years (68 months) to clear — about $8,840 total, including roughly $3,840 in interest with daily compounding. Minimum payments that shrink as the balance falls take far longer. The debt grows faster than those payments reduce principal, which is why carrying a balance is one of the most expensive financial mistakes.
What is the Rule of 72 and how do you use it?
Divide 72 by your annual interest rate to estimate how many years it takes for money to double. At 8%, money doubles in about 9 years (72 ÷ 8 = 9). At 22.36% (Fed average credit card APR for accounts assessed interest, August 2026), debt doubles in roughly 3.2 years (72 ÷ 22.36). It is a quick mental math shortcut — not exact, but accurate within 1-2 years for rates between 4% and 15%.
How much difference does starting 10 years earlier really make?
Starting at 25 instead of 35 with the same $500/month contribution at 8% until age 65 produces $1.74 million versus approximately $745,000 — a difference of nearly $1 million on identical monthly deposits. The 25-year-old contributes $60,000 more over those extra 10 years, but earns roughly $935,000 more in compound growth because early dollars have decades longer to multiply.
Is compound interest the same for savings accounts and investments?
The math is identical — interest earns interest in both cases — but the rates and risk differ dramatically. Top FDIC-insured high-yield savings accounts paid about 4.0–4.3% APY in mid-October 2026 (Tier-2 market surveys), while the FDIC national average savings rate was 0.38%. Stock index funds have historically returned roughly 10% per year nominal with dividends reinvested over long periods (1928–2024, Tier-2 historical dataset) but fluctuate year to year. A $25,000 HYSA at 4.25% APY grows to about $30,908 in 5 years with bank insurance. The same $25,000 in an index fund at 8% could reach $36,734 — but might temporarily drop 20–30% along the way.
Does it matter how often interest compounds — daily, monthly, or annually?
Yes, but the difference is smaller than most people expect. On a $10,000 deposit at 5% for 10 years: annual compounding yields $16,289, monthly compounding yields $16,470, and daily compounding yields $16,487. The jump from annual to monthly adds $181, while monthly to daily adds just $17. For most savings and investment decisions, monthly versus daily compounding is negligible — the interest rate and time horizon matter far more than compounding frequency.
Related Guides
How to Save $50,000 in 3 Years: A Realistic Plan
A step-by-step plan to save $50,000 in 3 years on an average salary. Includes monthly targets, budget breakdowns, a real case study, and strategies that actually work.
How to Start Investing with $1,000: A Beginner's Step-by-Step Guide
Start investing with just $1,000. Learn which account to open, what to buy (VTI, VOO, VTSAX), and how $100/month grows to six figures over time.