Guides / Investing Basics
How to Start Investing with $1,000: A Beginner's Step-by-Step Guide
You do not need $10,000 or a finance degree to start building wealth. With $1,000, zero-commission brokerages, and fractional shares, you can own a piece of the entire U.S. stock market today. This guide walks through exactly where to put your money, what to buy, and how to set it up so investing becomes automatic.
Last updated: October 2026
TL;DR - Quick Answer
- Best account: Roth IRA at Fidelity, Schwab, or Vanguard — tax-free growth on every dollar
- Best investment: Broad market index fund like VTI (0.03% expense ratio) or FXAIX (0.015%) — one fund, hundreds to thousands of companies. VTSAX needs $3,000 at Vanguard, so VTI is the practical $1,000 choice
- Minimum needed: $1.00 — Fidelity, Schwab, and Vanguard all allow $1 fractional purchases (October 2026)
- 2026 Roth IRA limit: $7,500 ($625/month), up from $7,000 in 2025
- Next step: Set up $50-$100/month auto-invest and forget about it for 20 years
Model your growth with our Investment Return Calculator and Compound Interest Calculator.
Why $1,000 Is Enough to Start Investing
A decade ago, starting with $1,000 meant paying $7-$10 per trade, needing $3,000 minimums for mutual funds, and buying whole shares only. That world is gone. In 2026, the barriers to entry have effectively disappeared.
Fractional shares let you buy $50 of VTI instead of needing roughly $380 for a full share (it closed near $380 in late September 2026). $0 commissions mean Fidelity, Charles Schwab, and Vanguard charge nothing to buy or sell stocks and ETFs. No account minimums mean you can open a Roth IRA with $1 if you wanted to — though starting with $1,000 gives you meaningful diversification from day one.
| Brokerage | Account Minimum | Stock/ETF Commissions | Fractional Shares |
|---|---|---|---|
| Fidelity | $0 | $0 | Yes ($1 minimum) |
| Charles Schwab | $0 | $0 | Yes ($1 minimum; most U.S. stocks and ETFs) |
| Vanguard | $0 | $0 | Yes ($1 minimum; Vanguard ETFs only) |
Schwab raised its fractional-share coverage in 2026: the old Stock Slices program (S&P 500 stocks only, $5 minimum) is now simply "fractional shares" on most U.S. stocks and ETFs with a $1 minimum.
Sources Fidelity, Schwab, Vanguard. Checked October 2026.
The math favors starting now over waiting to save more. $1,000 invested at age 25 with an 8% average return grows to $10,063 by age 55 — even with zero additional contributions. Start the same $1,000 at age 30 instead and it reaches only $6,848 by 55, a 32% smaller result for five idle years. Waiting to build a bigger lump sum does not pay either: investing $1,000 now and adding $4,000 at age 30 ends at $37,457 by age 55, versus $34,242 if you hold everything in cash and invest $5,000 at 30. Starting now is worth $3,215 here, and every extra year of delay shrinks the final balance by about 7%.
Where to Invest Your First $1,000
Your first decision is not what stock to pick — it is what type of account to open. The account wrapper determines how your money is taxed, which directly affects how much you keep over 30 years.
| Account Type | Tax Benefit | 2026 Limit | Best For | Example Fund |
|---|---|---|---|---|
| Roth IRA | Tax-free growth and withdrawals in retirement | $7,500/year ($625/month) | Most beginners (best first choice) | VTI (0.03% ER) or FXAIX (0.015% ER) |
| Taxable Brokerage | None — pay taxes on dividends and gains | Unlimited | After maxing Roth IRA; mid-term goals (5-10 years) | VTI (0.03% ER); VTSAX (0.04%) once you reach $3,000 at Vanguard |
| Robo-Advisor | Same as underlying account (Roth or taxable) | Varies | Hands-off investors who want automatic rebalancing | Diversified ETF portfolio (+ 0.25% management fee, or $5/month at Betterment under $24,000) |
Our Recommendation
Open a Roth IRA at Fidelity and buy FXAIX (Fidelity 500 Index Fund, 0.015% expense ratio) or VTI if you prefer an ETF. The Roth IRA gives you decades of tax-free compounding on a $1,000 start. Skip robo-advisors until your balance exceeds $10,000 — the 0.25% fee costs you $25/year on $10,000 versus $3/year with VTI alone. Betterment's Digital plan is worse at this size: a flat $5 per month is $60 per year, or 6% of a $1,000 balance, unless you automate $200/month or reach $24,000.
Roth IRA vs Taxable vs Robo-Advisor: Cost Comparison on $1,000
| Option | Annual Fees on $1,000 | 30-Year Fee Drag on $1,000 (est.) | Effort Required |
|---|---|---|---|
| DIY Roth IRA + VTI | $0.30 (0.03% ER) | ~$84 | 15 minutes to set up |
| DIY Roth IRA + FXAIX | $0.15 (0.015% ER) | ~$42 | 15 minutes to set up |
| Wealthfront (0.25% + ~0.03% fund ER) | $2.80 | ~$754 | 5 minutes to set up |
| Betterment Digital (under $24,000, under $200/mo deposits) | $60.00 ($5/month, plus fund ER) | Flat fee = 6% of $1,000 per year | 5 minutes to set up |
| Actively managed fund (1.0% ER) | $10.00 | ~$2,450 | Varies |
*30-year fee drag = ending value at 8% gross return minus ending value at (8% minus the fee), for a single $1,000 deposit with no additions: $10,063 versus $9,979 for VTI, $10,021 for FXAIX, $9,309 for Wealthfront, and $7,612 for a 1.0% fund. Fee data as of October 2026.
Sources Wealthfront pricing, Betterment pricing, Fidelity FXAIX. Checked October 2026.
What to Buy: Index Funds That Work for Beginners
You need exactly one fund to start. Pick a broad, low-cost index fund that tracks the U.S. stock market (or the S&P 500 as a close proxy). Here are the best options for a $1,000 starter portfolio, plus a target-date fund if you want zero decisions. Returns below are trailing figures through September 30, 2026 and are context, not a forecast.
| Fund | Type | Expense Ratio | 10-Year Avg Return | Holdings |
|---|---|---|---|---|
| VOO | S&P 500 ETF | 0.03% | 15.29% | ~500 large U.S. companies |
| FXAIX | S&P 500 Mutual Fund (Fidelity) | 0.015% | 15.32% | ~500 large U.S. companies, $0 minimum |
| VTI | Total Market ETF | 0.03% | 14.70% | ~3,500 U.S. companies |
| VTSAX | Total Market Mutual Fund | 0.04% | 14.69% | Same as VTI (Admiral shares, $3,000 minimum) |
| VLXVX (2065) | Target Date Fund | 0.08% | 11.01%* (since July 2017) | Stocks + bonds, auto-rebalanced, $1,000 minimum |
Sources Vanguard Total Return Chart (Sept. 30, 2026), Fidelity FXAIX. Checked October 2026. *Annualized total returns through September 30, 2026. VLXVX launched in July 2017, so it has no 10-year record; its 5-year return was 10.22%. Vanguard renamed its CRSP-benchmarked funds in 2026 (for example, "Vanguard Morningstar Total Stock Market Index Fund"), but the tickers VTI and VTSAX did not change. Past performance does not guarantee future results.
Why the projections below use 8%, not 15%
The 10-year window ending September 2026 was unusually strong: $1,000 in VOO at 15.29% would have become about $4,149. Over the longer 20 years ending December 2025, J.P. Morgan Asset Management's data imply about 11.0% a year for the S&P 500 ($10,000 became $80,619). This guide plans with 8% so the numbers still work if the next decade is weaker; see the 6%, 8%, and 10% results in the case study.
VOO — Best if you want simplicity
Tracks the S&P 500 — the 500 largest U.S. companies including Apple, Microsoft, Nvidia, and Amazon. At 0.03% expense ratio, you pay $0.30 per year on every $1,000 invested. In the 10 years through September 30, 2026, VOO returned 15.29% annually, turning $1,000 into approximately $4,149 before any additional contributions. That stretch was unusually strong, so do not expect it to repeat.
VTI / VTSAX — Best for maximum diversification
Holds roughly 3,500 U.S. stocks — large, mid, and small cap. VTI is the ETF version (trade anytime, $1 minimum); VTSAX is the mutual fund version with the same holdings but a $3,000 minimum for Admiral shares at Vanguard. With $1,000, buy VTI now and consider VTSAX only if you are already a Vanguard mutual fund investor with $3,000 or more. The 0.03-0.04% expense ratio is among the lowest available anywhere.
Target Date Fund — Best if you want zero maintenance
Pick the fund closest to the year you turn 65. A 23-year-old in 2026 turns 65 in 2068, so Vanguard Target Retirement 2065 (VLXVX) or 2070 (VSVNX) both fit. It starts nearly 100% in stocks (check the fund's current allocation) and automatically shifts toward bonds as you age. The 0.08% fee is slightly higher than VTI (about $0.80 per year on $1,000), but you never need to rebalance or pick a bond fund. Vanguard's Target Retirement Investor shares have a $1,000 minimum, so your starting amount qualifies exactly.
Case Study: Jordan, 23, $48K First Job, $1,000 Saved
Starting Point
- Age: 23, first full-time job
- Gross salary: $48,000/year ($4,000/month)
- Take-home after taxes: ~$3,200/month
- Savings available: $1,000
- Employer 401(k): No match offered
- Debt: $0 credit card, $12,000 student loans at 5.2%
- Emergency fund: $2,400 (3 months expenses — already set)
What Jordan Did
- Opened a Fidelity Roth IRA (15 minutes online)
- Contributed full $1,000 as initial deposit
- Bought FXAIX (Fidelity 500 Index, 0.015% ER)
- Set up $100/month auto-transfer from checking
- Scheduled auto-invest into FXAIX on the 1st of each month
- Kept student loans at minimum ($128/month)
Projected Portfolio Value (8% Average Annual Return)
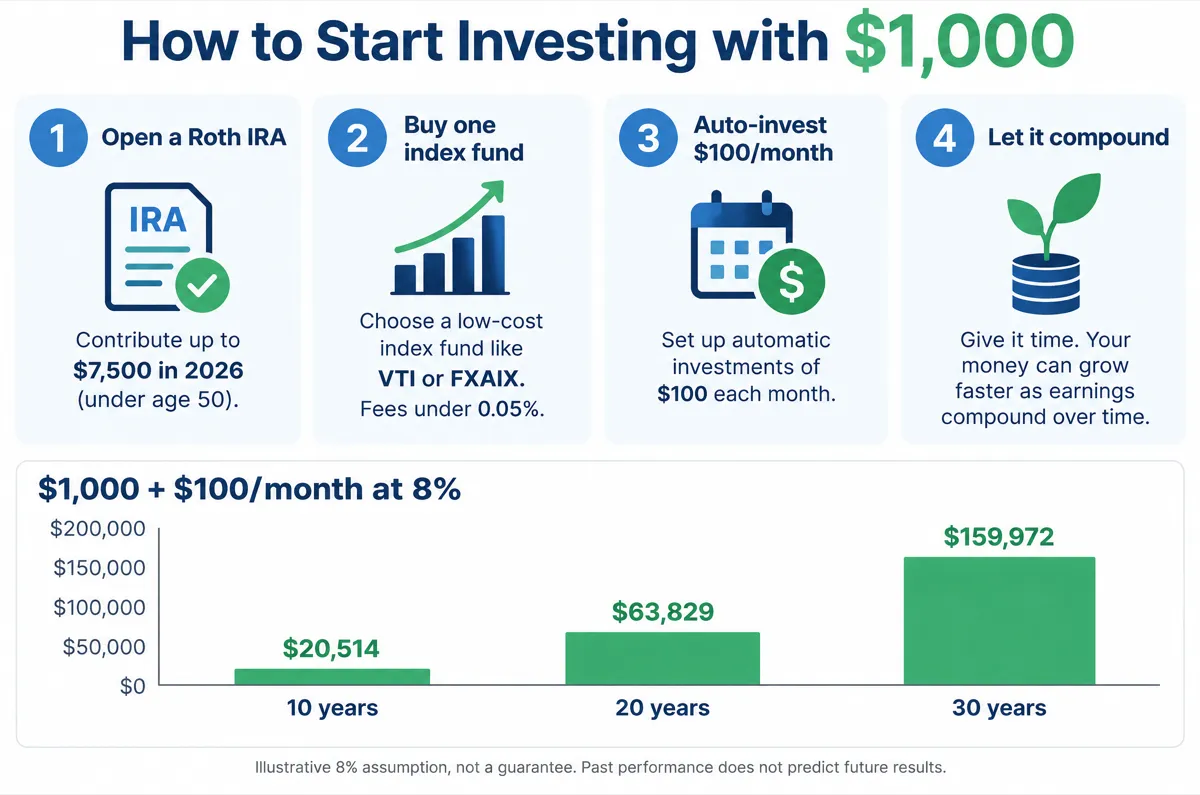
Starting with $1,000 plus $100/month contributions, compounded monthly at 8%:
After 10 Years (Age 33)
$20,514
$13,000 contributed + $7,514 growth
After 20 Years (Age 43)
$63,829
$25,000 contributed + $38,829 growth
After 30 Years (Age 53)
$159,972
$37,000 contributed + $122,972 growth
What If Returns Are Lower or Higher? (Same $1,000 + $100/month)
| Annual Return | 10 Years | 20 Years | 30 Years |
|---|---|---|---|
| 6% (cautious) | $18,207 | $49,514 | $106,474 |
| 8% (planning case) | $20,514 | $63,829 | $159,972 |
| 10% (optimistic) | $23,192 | $83,265 | $245,886 |
Monthly compounding, $100 added at the end of each month, no fees or taxes (Roth IRA), not adjusted for inflation. If inflation held at the 3.7% rate BLS reported for September 2026, the 30-year 8% result would buy roughly what $53,800 buys today; at 3% it would be about $65,900.
The Tax Advantage
Because Jordan used a Roth IRA, the entire $159,972 at age 53 is tax-free upon withdrawal in retirement. If the same portfolio were in a taxable brokerage account, roughly $122,972 in gains would be subject to a 15% long-term capital gains rate (a common rate for middle incomes) — about $18,446 owed to the IRS. The Roth IRA saved Jordan over $18,000 in taxes on the same investment strategy. Jordan's $100/month is also well under the 2026 Roth IRA limit of $7,500 per year ($625/month), so there is room to raise contributions with each raise.
4 Common Mistakes When Starting with $1,000
1. Buying individual stocks
Putting $1,000 into 3-5 individual stocks feels exciting but concentrates your risk. Enron, Lehman Brothers, and Blockbuster were all "sure things" until they were not. A single company can drop 50-100% — VTI dropped 34% in 2020 and recovered within months because it held hundreds of companies. With $1,000, diversification is not optional.
2. Trying to time the market
Waiting for a "correction" before investing $1,000 sounds prudent but costs you money. J.P. Morgan Asset Management found that $10,000 left fully invested in the S&P 500 from January 2006 through December 2025 grew to $80,619 (about 11.0% a year). Missing just the 10 best days cut that to $35,866 (about 6.6% a year). Six of the 10 best days came within two weeks of the 10 worst days, so you cannot dodge the bad ones without missing the good ones. Invest on a schedule regardless of headlines.
Source J.P. Morgan Asset Management. Checked October 2026.
3. Not investing at all
The most expensive mistake is leaving $1,000 in a checking account. The FDIC's September 2026 national average is 0.07% for interest checking and 0.37% for savings, while BLS reported consumer prices up 3.7% over the 12 months ending September 2026. After 10 years at 0.07%, $1,000 becomes $1,007 — but if inflation averaged 3.7%, its purchasing power drops to roughly $695 in today's dollars (about $744 at 3%). The same $1,000 in VTI at 8% becomes $2,159. Analysis paralysis costs real money every month you wait.
Sources FDIC national rates, BLS CPI release. Checked October 2026.
4. Choosing high-fee funds
A 1.0% expense ratio fund costs $10/year on $1,000 versus $0.30 for VTI. That gap widens as your balance grows. On a $50,000 portfolio over 30 years, the difference between a 1.0% fee fund and a 0.03% index fund is approximately $118,000 in lost compound growth ($498,957 versus $380,613 at an 8% gross return). Always check the expense ratio before buying — anything above 0.20% needs a specific justification.
Step-by-Step: Invest Your First $1,000 This Week
Open a Roth IRA (Day 1 — 15 minutes)
Go to fidelity.com, schwab.com, or vanguard.com and open a Roth IRA. You need your Social Security number, bank account info for linking, and employment details. Select "Individual Roth IRA" — not a managed account or robo-advisor unless you specifically want one. There is no minimum deposit to open.
Fund the account (Day 1-3)
Link your checking account and transfer $1,000. ACH transfers typically take 1-3 business days to settle. While waiting, research your fund choice: FXAIX at Fidelity, VTI/VOO at any brokerage, or a Target Retirement fund at Vanguard (VTSAX needs $3,000 there). Do not let the transfer time become an excuse to delay — initiate it today.
Buy your index fund (Day 3-4)
Once cash settles, search for your fund ticker (e.g., FXAIX or VTI) and click Buy. Enter $1,000 (or the full available balance). Select "Market order" for immediate execution. You now own a slice of the U.S. stock market. The entire purchase takes under 2 minutes.
Set up automatic monthly contributions (Day 4)
In your Roth IRA settings, enable automatic investments: transfer $50-$100/month from checking and auto-buy your index fund. Schedule it for 1-2 days after payday. Jordan chose $100/month — that is 3.1% of take-home pay on a $48,000 salary, a sustainable starting rate. Increase by $25 every time you get a raise.
See What Your $1,000 Could Become
Plug in your starting amount, monthly contribution, and expected return to see exactly how compound growth transforms a $1,000 start over 10, 20, or 30 years.
Frequently Asked Questions
Is $1,000 enough to start investing?
Yes. Fidelity, Charles Schwab, and Vanguard all have $0 account minimums and $0 online commissions on U.S. stock and ETF trades. As of October 2026, Fidelity, Schwab, and Vanguard each let you buy a fractional share for as little as $1 (at Vanguard this applies to Vanguard ETFs such as VTI and VOO). A $1,000 starting balance plus a steady monthly contribution is enough to own the entire U.S. market through a single fund.
Should I invest $1,000 in a Roth IRA or a taxable brokerage account?
For most beginners under age 50 with earned income, a Roth IRA is the better first choice. You contribute after-tax dollars, but all growth and qualified withdrawals in retirement are tax-free. The 2026 IRA contribution limit is $7,500 per year ($625/month), up from $7,000 in 2025, so your $1,000 fits easily. Use a taxable brokerage only after maxing your Roth IRA and any employer 401(k) match.
Is there an income limit for contributing to a Roth IRA in 2026?
Yes. For 2026 the Roth IRA contribution phase-out is $153,000-$168,000 of modified adjusted gross income for single filers and heads of household, and $242,000-$252,000 for married couples filing jointly (IRS Notice 2025-67). Below the lower number you can contribute the full $7,500; above the upper number you cannot contribute directly. Most people starting with $1,000 are well under these limits.
What is the best thing to buy with $1,000 as a beginner?
A broad market index fund or ETF. VTI (Vanguard Total Stock Market ETF) at 0.03% expense ratio gives you exposure to roughly 3,500 U.S. companies in one purchase. VOO (S&P 500 ETF) is a solid alternative with the same 0.03% cost. Avoid individual stocks, crypto, and actively managed funds with fees above 0.50% — a 1.0% fund costs $10 per year on $1,000 versus $0.30 for VTI, and that gap compounds to about $2,450 over 30 years at an 8% gross return.
How much will $1,000 grow if I invest it and add $100/month?
At an 8% average annual return compounded monthly, $1,000 invested today plus $100/month grows to approximately $20,514 in 10 years, $63,829 in 20 years, and $159,972 in 30 years. At 6%, those numbers are $18,207, $49,514, and $106,474; at 10%, $23,192, $83,265, and $245,886. Actual returns vary year to year — use our Investment Return Calculator to model different scenarios.
Do I need a financial advisor to start investing with $1,000?
No. For a simple index fund strategy, a self-directed account at Fidelity, Schwab, or Vanguard is sufficient. Wealthfront charges 0.25% annually ($2.50 per $1,000), and Betterment charges 0.25% or a flat $5 per month ($60 per year, or 6% of a $1,000 balance) unless you hold $24,000 or set up $200/month in recurring deposits. Human advisors typically charge about 1% ($10 per $1,000) and rarely make sense this early. At $1,000, DIY with a total market ETF or a target-date fund keeps your annual cost under $1.
Why did the 10-year returns in this guide look higher than the 8% used in projections?
Trailing 10-year returns through September 30, 2026 were 15.29% for VOO and 14.70% for VTI, which is unusually strong. Over the 20 years ending December 2025, J.P. Morgan Asset Management reports the S&P 500 returned about 11.0% annualized. We use 8% for the projections as a deliberately cautious planning number that leaves room for weaker decades, fees, and inflation. Treat past returns as context, not a forecast.
Sources IRS IR-2025-111, 2026 retirement plan limits (Nov. 13, 2025), Vanguard fund returns as of Sept. 30, 2026, Vanguard fund minimums. Checked October 2026. Educational content, not personalized investment advice.
Related Guides
Compound Interest: 5 Real-Life Examples That Show Its Power
See compound interest in action with 5 real examples: $500/month for 40 years, credit card debt traps, student loans, and the Rule of 72 explained.
401(k) vs Roth IRA: Which Retirement Account Is Better for You?
Compare 401(k) vs Roth IRA: contribution limits, tax treatment, income limits, and when each wins. Includes a case study and the optimal hybrid strategy.