Guides / Retirement Planning
401(k) vs Roth IRA: Which Retirement Account Is Better for You?
The 401(k) vs Roth IRA debate is not about picking one winner — it is about understanding how each account taxes your money differently and which fits your current income, career trajectory, and retirement timeline. This guide breaks down the 2026 IRS limits, runs the numbers on a real case study using the 2026 tax brackets, and shows you the hybrid strategy built around your employer match.
Last updated: October 2026
TL;DR - Quick Answer
- 401(k) in 2026: Contribute up to $24,500 pre-tax (up from $23,500); employer match is free money you should never leave on the table
- Roth IRA in 2026: Contribute up to $7,500 (up from $7,000) after-tax; all qualified withdrawals are tax-free in retirement
- 401(k) wins when: You are in a high tax bracket now, your employer offers a match, or you earn above Roth income limits (phase-out ends at $168K single / $252K married)
- Roth wins when: You are early in your career in a lower bracket, expect higher taxes in retirement, or want tax diversification and penalty-free access to contributions
- Best strategy for most people: Get the full 401(k) match, max the Roth IRA, then fill remaining capacity in the 401(k)
- The math in one line: At the same tax rate now and in retirement, Roth and traditional end up equal. The winner is whichever account taxes you at the lower rate
Model your retirement with our Retirement Calculator, Compound Interest Calculator, and Income Tax Calculator.
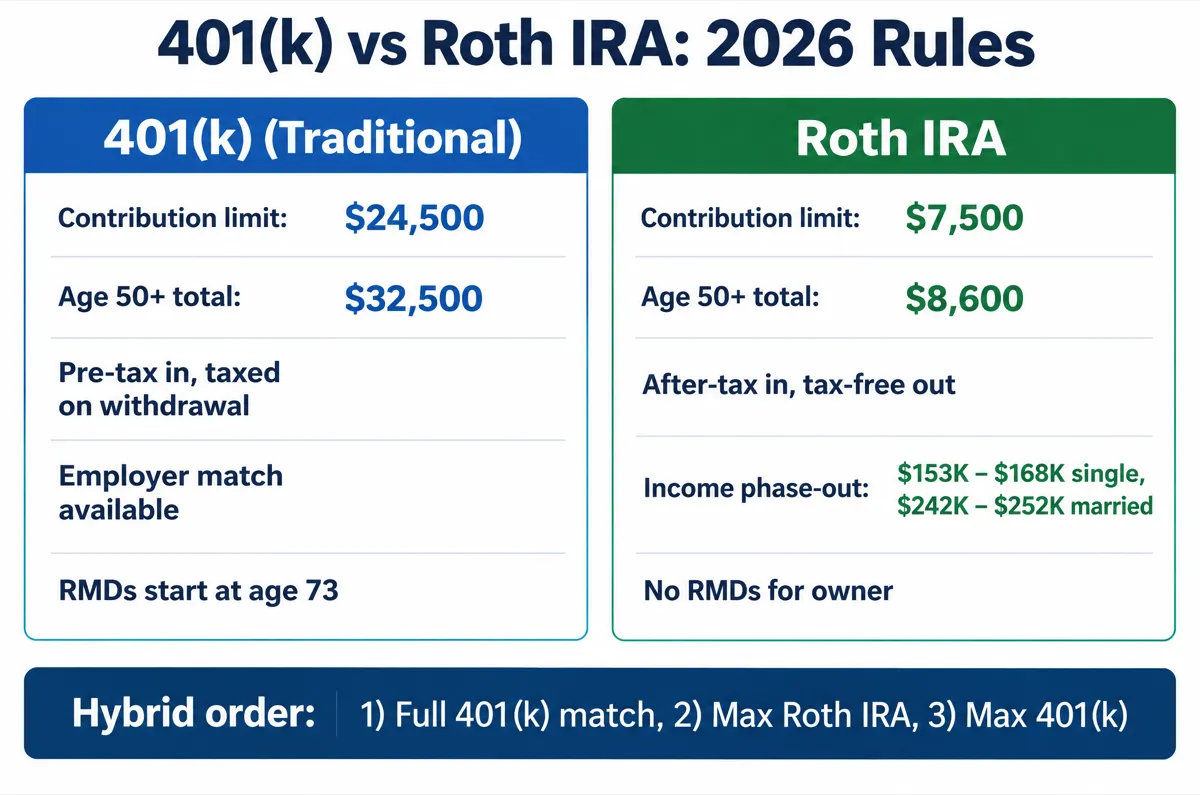
Key Differences: Pre-Tax vs After-Tax
The fundamental split between a 401(k) and a Roth IRA comes down to when you pay taxes. A traditional 401(k) reduces your taxable income today — you contribute pre-tax dollars, investments grow tax-deferred, and you pay ordinary income tax on every dollar you withdraw in retirement. A Roth IRA flips that timeline: you contribute after-tax dollars now, investments grow tax-free, and qualified withdrawals in retirement are completely tax-free.
That timing difference sounds abstract until you put real numbers on it. A $24,500 contribution to a traditional 401(k) for a single filer in the 22% federal bracket (taxable income of $50,400-$105,700 in 2026) saves $5,390 in taxes this year. The same person putting $7,500 into a Roth IRA gets no deduction — but every dollar of growth over the next 30 years comes out untaxed.
2026 Contribution Limits
The IRS sets separate limits for each account type. These limits apply to your employee contributions — employer matching dollars do not count against your personal cap.
401(k)
$24,500
Employee contribution limit (up $1,000 from 2025). Workers age 50+ can add an $8,000 catch-up for a total of $32,500; ages 60-63 can add $11,250 for a total of $35,750.
Roth IRA
$7,500
Combined limit for Roth and traditional IRA contributions (up $500 from 2025). Age 50+ catch-up adds $1,100 for a total of $8,600.
Combined, a worker under 50 can funnel up to $32,000 per year into tax-advantaged retirement accounts — plus whatever employer match their company adds on top. That is a meaningful gap from the Roth IRA alone, which is one reason the 401(k) remains the primary retirement vehicle for most Americans.
New in 2026: Roth-Only Catch-Up for Higher Earners
If you are 50 or older and your prior-year FICA wages from your employer exceeded $150,000 (up from $145,000), your 401(k) catch-up contributions must go in as Roth (after-tax) money. A 55-year-old who earned $180,000 in 2025 can still defer $24,500 pre-tax in 2026, but the extra $8,000 catch-up is after-tax, which removes a $1,920 deduction at the 24% bracket. The rule only applies if your plan offers a Roth option; if it does not, you cannot make catch-up contributions at all.
401(k) vs Roth IRA: Full Comparison
Use this table as a quick reference when deciding where to allocate your next retirement dollar. The right column is not always better — context determines the winner.
| Feature | 401(k) (Traditional) | Roth IRA |
|---|---|---|
| Contribution limit (2026) | $24,500 ($32,500 age 50+; $35,750 age 60-63) | $7,500 ($8,600 age 50+) |
| Tax treatment | Pre-tax in, taxed on withdrawal | After-tax in, tax-free out |
| Employer match | Yes, if the plan offers one (average promised match: 4.7% of pay) | No employer involvement |
| Income limits | None for participation | Phase-out $153K-$168K single / $242K-$252K married |
| Withdrawal rules | Penalty before age 59½ (10% + taxes) | Contributions anytime; earnings after 59½ + 5-year rule |
| Required minimum distributions | Yes — starting at age 73 (25% excise tax if missed) | No RMDs during owner's lifetime |
| Investment options | Limited to the plan menu chosen by your employer | Full brokerage choice (stocks, ETFs, bonds) |
| Loans | Some plans allow 401(k) loans | No loan provision |
Sources IRS IR-2025-111, 2026 retirement plan limits (Nov. 13, 2025), IRS RMD rules, IRS 2026 tax inflation adjustments (IR-2025-103). Checked October 2026. Employer match average from Vanguard's How America Saves 2026 (2025 plan data). Figures as of October 2026.
When a 401(k) Wins
A traditional 401(k) is the better choice in several specific situations. If any of these describe you, prioritize maxing your 401(k) before directing extra dollars to a Roth IRA.
You Are in a High Tax Bracket Now
A single filer with taxable income above $105,700 (2026) sits in the 24% bracket or higher, and above $201,775 in the 32% bracket. Every $10,000 of pre-tax 401(k) contributions saves $2,400-$3,200 in immediate federal tax, and a full $24,500 deferral saves $5,880-$7,840. If you expect to retire into a lower bracket — drawing $80,000/year from a paid-off home in a no-income-tax state puts a single filer in the 22% bracket after the $16,100 standard deduction — you are effectively prepaying taxes at a higher rate by choosing Roth over traditional. The 401(k) lets you defer that bill.
Your Employer Offers a Match
Employer matching is the single highest-return investment available to most workers. Vanguard's How America Saves 2026 report found the average promised match was 4.7% of pay (median 4.0%) across its plans, and the single most common formula was 50 cents per dollar on the first 6% of pay. On a $95,000 income that formula adds $2,850 per year in free money — an instant 50% return before any market growth. No Roth IRA contribution can replicate that. Always contribute at least enough to capture the full match before funding a Roth IRA.
The Match Math
On a $95,000 salary with a 50% match up to 6%: contributing 6% ($5,700) triggers a $2,850 employer deposit. Over 30 years at 7% average return (contributions at year-end), that match alone grows to approximately $269,200 — money you never would have had without the 401(k).
You Earn Above Roth IRA Income Limits
In 2026, direct Roth IRA contributions phase out for single filers with modified adjusted gross income above $153,000 begin to lose eligibility, and the door closes completely at $168,000. For married couples filing jointly the range is $242,000-$252,000. If you are above those thresholds, a Roth IRA is not an option without a backdoor conversion strategy. Your 401(k) becomes the primary tax-advantaged account by default — and its $24,500 limit is more than three times the Roth cap anyway.
You Need the Higher Contribution Ceiling
Aggressive savers who want to put away more than $7,500 per year in tax-advantaged accounts have no choice but the 401(k). Pair it with an HSA ($4,400 self-only / $8,750 family in 2026) and you can shelter $28,900 (self-only) or $33,250 (family coverage) per year before touching taxable accounts or a Roth IRA.
When a Roth IRA Wins
Roth accounts shine in the opposite scenarios — lower income today, higher expected taxes tomorrow, and when flexibility matters as much as raw contribution limits.
Early Career, Lower Tax Bracket
A 28-year-old earning $55,000 has $38,900 of taxable income after the $16,100 standard deduction, which sits in the 12% federal bracket (income up to $50,400 in 2026). Paying 12% tax on Roth contributions now — when they are likely at their lifetime tax low — is far cheaper than paying 22-24% on traditional 401(k) withdrawals decades later. Every year you are in the 12-22% bracket is a Roth opportunity. The tax you pay today is the lowest rate you will ever lock in on that money.
You Expect Higher Taxes in Retirement
If you believe tax rates will rise — due to national debt, policy changes, or your own income growth — paying taxes now at today's rates is a hedge. A single $7,500 Roth contribution today that grows to $57,100 over 30 years at 7% comes out entirely tax-free. Withdrawing that same $57,100 from a traditional account would trigger roughly $12,560-$18,270 in federal tax at a 22%-32% retirement bracket.
Tax Diversification
Retirees with only traditional 401(k) balances face a tax bill on every withdrawal — including Social Security, which becomes partially taxable once other income exceeds thresholds. A Roth IRA balance gives you a tax-free bucket to draw from strategically. You can pull Roth money to stay below a tax bracket threshold, reduce Medicare IRMAA surcharges, or qualify for ACA premium subsidies during early retirement before Medicare at 65.
Flexibility and No RMDs
Roth IRA contributions (not earnings) can be withdrawn at any time without penalty. And unlike a 401(k), there are no required minimum distributions — you can let a Roth compound untouched and pass it to heirs tax-free.
Case Study: Priya, 32, Product Manager in Austin
Priya earns $95,000 as a product manager at a tech company in Austin, Texas. Texas has no state income tax, so federal tax drives the analysis. After the $16,100 standard deduction her taxable income is $78,900 before any 401(k) deferral, which puts her in the 22% bracket ($50,400-$105,700 for single filers in 2026). Her employer matches 50% of contributions up to 6% of salary. She has $44,000 in her 401(k) and $9,000 in a Roth IRA, and she wants to put $19,500 of her own money into retirement each year ($1,625 per month), on top of the match.
Current Situation
- Age: 32 (target retirement: 62)
- Salary: $95,000/year, single filer
- 401(k) balance: $44,000
- Roth IRA balance: $9,000
- Employer match: 50% up to 6% ($2,850/year at full match)
- Federal tax with no deferral: $12,070 (22% marginal)
- Assumed return: 7% average annual, year-end contributions
Two Strategies Compared
- Strategy A (401(k) only): $21,600 to 401(k) + $2,850 match = $24,450/year pre-tax. The $4,752 tax saving brings her take-home cost to $16,848.
- Strategy B (Hybrid): $12,000 to 401(k) ($5,700 for the match + $6,300 more) + $7,500 Roth IRA + $2,850 match = $22,350/year. The $2,640 tax saving brings her take-home cost to $16,860.
Both strategies cost about the same out of pocket. Strategy A invests more dollars because pre-tax contributions are cheaper after the deduction than Roth contributions.
30-Year Projection at Age 62 (Nominal Dollars)
- Existing balances: $44,000 x 1.07^30 = $334,939 (401(k)) and $9,000 x 1.07^30 = $68,510 (Roth IRA), identical in both strategies
- Strategy A: $24,450/year grows to $2,309,566. Traditional balance: $2,644,505. Roth balance: $68,510. Total: ~$2,713,016
- Strategy B: $14,850/year to the 401(k) grows to $1,402,743 and $7,500/year to the Roth IRA grows to $708,456. Traditional balance: $1,737,682. Roth balance: $776,966 (31% of the total). Total: ~$2,514,648
After-Tax Spendable Wealth Depends on the Retirement Tax Rate
Traditional balances are taxed when withdrawn; Roth balances are not. The table applies one flat average tax rate to every traditional dollar to show how the winner flips.
| Tax rate on traditional withdrawals | Strategy A spendable | Strategy B spendable | Winner |
|---|---|---|---|
| 15% (lower than today) | $2,316,340 | $2,253,996 | A by $62,344 |
| 22% (same as today) | $2,131,225 | $2,132,358 | Tie (B by $1,133) |
| 28% (higher than today) | $1,972,554 | $2,028,097 | B by $55,543 |
What Priya Should Do
The table shows that Roth is not a free lunch: at the same 22% rate, the two strategies finish within about $1,100 of each other on $2.1 million. Roth wins only if her retirement tax rate ends up above her current one, and the traditional 401(k) wins if it ends up below. Either way the gap is about $55,000-$62,000, roughly 3% of the final balance. Because no one can forecast rates 30 years out, Priya picks Strategy B for tax diversification rather than a guaranteed higher balance: it costs her nothing at a 22% rate and gives her a $776,966 tax-free bucket for managing her tax bracket, ACA subsidies if she retires before 65, and no RMDs on the Roth portion. The 401(k) match remains non-negotiable in either scenario.
The Hybrid Strategy Most Experts Recommend
For the majority of workers, the answer to 401(k) vs Roth IRA is not either/or — it is a sequenced approach that captures the best features of both accounts. Follow this priority order with every paycheck:
Get the full 401(k) employer match
Contribute at least enough to trigger 100% of your employer match. On a $95,000 salary with a 50% match up to 6%, that means contributing $5,700 to receive $2,850 in free money. This step is non-negotiable regardless of your tax bracket or age.
Max your Roth IRA ($7,500 in 2026)
If your income is below the Roth phase-out ($153,000 single / $242,000 married), fund the full $7,500 Roth IRA next. You gain tax-free growth, flexible contribution access, and no RMDs. Open the account at a low-cost brokerage with broad index fund options.
Return to your 401(k) and max it out
After the match and Roth IRA are funded, direct remaining retirement savings back to your 401(k) until you hit the $24,500 limit. If you already contributed $5,700 for the match, you have $18,800 of remaining 401(k) capacity. This maximizes your total tax-advantaged savings at $32,000 per year.
Overflow into taxable brokerage or HSA
If you still have surplus savings after maxing both accounts, fund an HSA if you have a qualifying high-deductible health plan ($4,400 self-only / $8,750 family in 2026), then invest in a taxable brokerage with low-cost index funds. Taxable accounts provide the bridge for early retirement before age 59½.
Annual Savings Checklist
For a single filer earning $95,000 with a 50% match up to 6%: $5,700 (401k match) + $7,500 (Roth IRA) + $18,800 (remaining 401k) = $32,000 personal contributions + $2,850 employer match = $34,850 per year. At 7% over 30 years (year-end contributions), that totals roughly $3.29 million before taxes, of which $708,500 sits in the Roth IRA.
Most people cannot fund the full $32,000. Scale the same order down: a worker who can save $12,000 a year on a $95,000 salary still captures the $5,700 match first, then puts the remaining $6,300 into the Roth IRA.
How Your Tax Bracket Should Drive the Decision
The entire 401(k) vs Roth IRA calculation hinges on one comparison: your marginal tax rate today versus your expected marginal rate in retirement. When today's rate is higher, choose traditional. When tomorrow's rate is expected to be higher, choose Roth.
| Current Marginal Rate | Recommended Priority | Why |
|---|---|---|
| 10-12% (single taxable income up to $50,400) | Roth IRA first | Lock in the lowest rate you will ever pay |
| 22-24% (single $50,400-$201,775) | Hybrid (both) | Tax diversification; rates may rise by retirement |
| 32%+ (single above $201,775) | 401(k) first | Large immediate deduction; likely lower rate in retirement |
| Above Roth limits | 401(k) + backdoor Roth | Direct Roth unavailable; max 401(k) then convert |
Use our Income Tax Calculator to estimate your marginal rate and compare it to your expected retirement rate. If the gap is 5+ points, lean toward the lower-rate account.
Run Your Retirement Numbers
Compare 401(k) and Roth IRA growth side by side with your actual salary, contribution rate, and employer match. See how tax treatment changes your spendable balance at retirement.
Frequently Asked Questions
Should I contribute to a 401(k) or Roth IRA first?
Contribute enough to your 401(k) to capture your full employer match first — a 50% match is an immediate 50% return on those dollars. Then max a Roth IRA ($7,500 in 2026) if your income is below the phase-out ($153,000 single / $242,000 married filing jointly, with eligibility ending at $168,000 / $252,000). After that, return to your 401(k) and contribute up to the $24,500 limit. This hybrid approach captures free employer money, builds tax-free Roth assets, and maximizes total tax-advantaged savings.
Can I have both a 401(k) and a Roth IRA?
Yes, and most people should. A 401(k) and Roth IRA are separate accounts with separate contribution limits. In 2026 you can contribute up to $24,500 to a 401(k) and $7,500 to a Roth IRA — $32,000 total — as long as your income is below the Roth IRA phase-out thresholds. Having both gives you tax diversification: pre-tax 401(k) withdrawals and tax-free Roth withdrawals in retirement.
Is a Roth IRA better than a 401(k) for taxes?
It depends on your current versus expected future tax rate. A traditional 401(k) saves taxes now but you pay ordinary income tax on withdrawals. A Roth IRA offers no deduction now but all qualified withdrawals are tax-free. If you are in a low tax bracket early in your career (12-22%), Roth often wins. If you are in a high bracket now (32%+) and expect a lower bracket in retirement, the traditional 401(k) usually wins.
What happens if I earn too much for a Roth IRA?
In 2026, Roth IRA contributions phase out for single filers and heads of household with modified adjusted gross income between $153,000 and $168,000, and for married couples filing jointly between $242,000 and $252,000 (IRS Notice 2025-67). Above those ranges, direct Roth contributions are not allowed. High earners can use a backdoor Roth IRA (contribute to a traditional IRA, then convert to Roth), though the pro-rata rule applies if you hold existing traditional IRA balances.
Does a Roth IRA have required minimum distributions (RMDs)?
No. Roth IRAs have no RMDs during the original account owner's lifetime, which makes them powerful estate planning tools. Traditional 401(k) accounts require RMDs starting at age 73 under current law (SECURE 2.0), and missing one triggers a 25% excise tax on the amount not withdrawn (10% if corrected within 2 years). Roth 401(k) accounts also had RMDs, but starting in 2024 designated Roth balances are exempt while the owner is alive — though rolling to a Roth IRA remains a common strategy for flexibility.
What changed for 401(k) and Roth IRA savers in 2026?
Four numbers moved up. The 401(k) limit rose from $23,500 to $24,500, the IRA limit from $7,000 to $7,500, the 401(k) catch-up for age 50+ from $7,500 to $8,000 (total $32,500), and the IRA catch-up from $1,000 to $1,100 (total $8,600). Roth IRA phase-outs also rose to $153,000-$168,000 (single) and $242,000-$252,000 (married filing jointly). The biggest rule change is for higher earners: if your prior-year FICA wages from your employer exceeded $150,000, your 401(k) catch-up contributions must now be made as Roth (after-tax) contributions, so your plan needs a Roth option for you to keep making them.
Related Guides
How Much Do I Need to Retire at 55? A Complete Breakdown
Find out how much you need to retire at 55. Covers the 4% rule, healthcare costs before Medicare, portfolio targets by lifestyle, and a step-by-step plan.
How to Start Investing with $1,000: A Beginner's Step-by-Step Guide
Start investing with just $1,000. Learn which account to open, what to buy (VTI, VOO, VTSAX), and how $100/month grows to six figures over time.