Guides / Savings Strategy
How to Save $50,000 in 3 Years: A Realistic Plan
Saving $50,000 in 36 months means putting away $1,389 every single month. That sounds daunting — but with the right strategy, automation, and a high-yield savings account working in your favor, it breaks down into a system anyone earning $75,000+ can follow. This guide maps out exactly how to get there.
Last updated: October 2026
TL;DR - Quick Answer
- Monthly target: $1,389/month without interest, or ~$1,300/month with a 4.50% APY savings account
- Best vehicle: High-yield savings account (example top online rates about 4.25-4.75% APY as of mid-October 2026) — not stocks, not CDs
- The formula: 60% budget cuts + 30% income boost + 10% interest earnings
- Automate everything: Set up automatic transfers on payday — savings that require willpower fail
Use our Savings Goal Calculator and Compound Interest Calculator to build your personalized plan.
The Math Behind Saving $50,000 in 3 Years
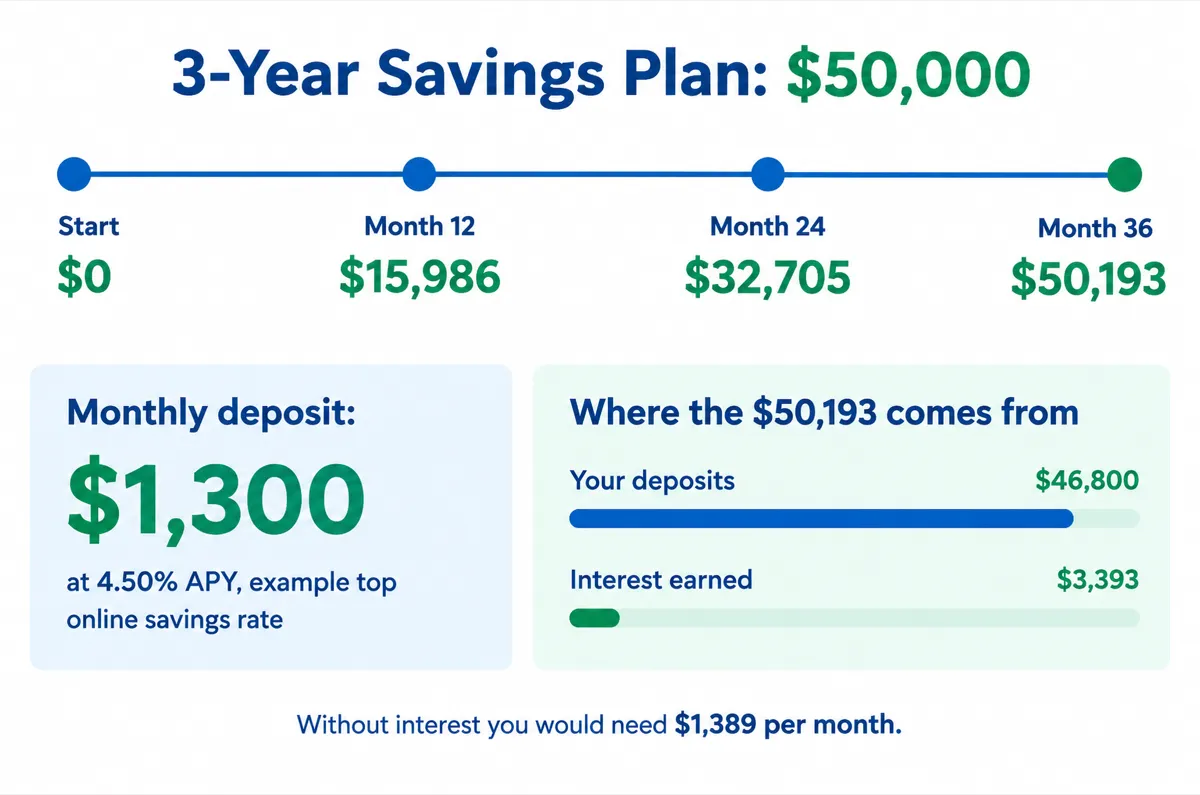
Before building a plan, you need to understand the raw numbers. $50,000 divided by 36 months equals $1,388.89 per month. That is your baseline target if you stuff cash under a mattress with zero interest.
But you are not going to use a mattress. A high-yield savings account paying 4.50% APY (example rates at top online banks as of mid-October 2026) means compound interest contributes roughly $3,400 of that $50,000 over three years. Your actual monthly contribution drops to approximately $1,295 ($1,300 rounded) — saving you about $89/month compared to the zero-interest baseline.
Here is how the money grows month by month at 4.50% APY:
| Milestone | Months | Total Deposited | Interest Earned | Balance |
|---|---|---|---|---|
| Month 6 | 6 | $7,800 | $103 | $7,903 |
| Year 1 | 12 | $15,600 | $386 | $15,986 |
| Month 18 | 18 | $23,400 | $852 | $24,252 |
| Year 2 | 24 | $31,200 | $1,505 | $32,705 |
| Month 30 | 30 | $39,000 | $2,351 | $41,351 |
| Year 3 (Goal) | 36 | $46,800 | $3,393 | $50,193 |
*Based on $1,300/month deposits into a 4.50% APY high-yield savings account with monthly compounding (exact $50,000 in 36 months requires about $1,295/month). Example HYSA rate as of mid-October 2026; actual interest may vary with rate changes.
Sources FDIC national deposit rates (Oct. 19, 2026), Federal Reserve, FOMC target range 3.75%-4.00% (Sept. 17, 2026). Checked October 2026. Milestone table uses a 4.50% example HYSA APY; FDIC national average savings was 0.38%.
The key insight: interest contributes $3,393 — nearly 2.6 full months of deposits you do not have to make. Every dollar saved earlier in the timeline earns more interest, which is why front-loading contributions (saving more in Year 1) accelerates the goal significantly.
What Income Do You Actually Need?
Saving $1,300/month requires a certain minimum take-home pay to remain realistic. Financial experts generally agree that saving more than 30-35% of take-home pay is unsustainable long-term without extreme lifestyle sacrifices. Here is the salary math:
| Gross Annual Salary | Monthly Take-Home (est.) | $1,300 as % of Take-Home | Feasibility |
|---|---|---|---|
| $50,000 | $3,530 | 36.8% | Very difficult |
| $65,000 | $4,534 | 28.7% | Challenging but doable |
| $75,000 | $5,133 | 25.3% | Realistic |
| $90,000 | $6,012 | 21.6% | Comfortable |
| $120,000 | $7,771 | 16.7% | Highly achievable |
*Take-home uses 2026 federal brackets, the $16,100 standard deduction (single), employee Social Security and Medicare, and no state income tax. Your actual take-home varies by state, filing status, and pre-tax deductions.
Sources IRS Rev. Proc. 2025-32 (tax year 2026 inflation adjustments), SSA contribution and benefit base. Checked October 20, 2026.
If your income puts you in the "very difficult" range, you have two options: extend the timeline (4 years requires only $1,000/month) or boost income through side work. A household earning $55,000 that adds $600/month in freelance income effectively matches the savings power of a $75,000 salary. We cover both strategies below.
Real Case Study: Jessica, $72,000 Salary in Austin, TX
Her Situation
- Age: 28, marketing manager
- Gross salary: $72,000/year ($6,000/month)
- Take-home after taxes/benefits: $4,480/month
- Goal: $50,000 for a house down payment in 3 years
- Current savings: $2,400 (essentially starting from zero)
- Debt: $8,200 student loans at 4.2% (minimum $145/month)
- Rent: $1,450/month (1BR apartment)
Her Strategy
- Moved to a $1,150/month apartment (saved $300)
- Cut subscriptions from $187 to $45 (saved $142)
- Meal prepped lunches — food from $680 to $420 (saved $260)
- Started freelance copywriting: $600-900/month
- Opened a 4.50% APY HYSA (example top online rate as of mid-October 2026)
- Automated $1,350 transfer every payday
- Kept student loan at minimum (4.2% < 4.50% savings rate)
Her Monthly Budget (Post-Optimization)
Housing
$1,150
Savings Transfer
$1,350
Food & Groceries
$420
Transportation
$280
Student Loan
$145
Everything Else
$535
Results After 18 Months
Jessica's HYSA balance reached about $27,750 from her $1,350 automated transfers alone by month 18 (starting from $2,400 at 4.50% APY). Freelance income averaging $750/month and a $3,200 tax refund in Year 1 pushed her further ahead of the milestone table. She adjusted her freelance hours down slightly and added back a $50/month gym membership she had canceled without feeling guilty.
Where to Find $1,300/Month: Budget Cuts That Actually Work
Most savings advice tells you to "cut lattes." That saves $150/month at best. To find $1,300+, you need to attack the three biggest expense categories — housing, transportation, and food — which typically consume 65-75% of take-home pay.
| Category | Strategy | Monthly Savings | Difficulty |
|---|---|---|---|
| Housing | Get a roommate or downsize | $300-800 | High impact, high effort |
| Transportation | Switch to a paid-off used car or bike commute | $200-500 | Moderate effort |
| Food | Meal prep + limit dining to 2x/month | $200-400 | Moderate effort |
| Subscriptions | Cancel all but 2-3 essentials | $80-200 | Easy |
| Insurance | Shop for quotes annually, raise deductibles | $50-150 | Easy |
| Shopping | 30-day rule + unsubscribe from retail emails | $100-300 | Moderate effort |
*Savings estimates based on national averages. Your actual savings will vary by location and current spending habits.
Key Insight
Housing is the single biggest lever. Reducing rent by $400/month accounts for 31% of your entire savings target. If you can negotiate a roommate situation or move to a cheaper area for 3 years, you are already one-third of the way to $50,000 from housing savings alone.
Boosting Income: The Faster Path to $50,000
There is a ceiling on how much you can cut expenses — you cannot reduce your food budget below zero. But there is no ceiling on income. Adding $500-1,000/month in side income reduces the pressure on your budget dramatically and often makes the difference between "possible" and "comfortable."
Freelancing Your Existing Skills ($500-3,000/month)
The highest ROI side income uses skills you already have. A marketing professional can freelance on Upwork for $50-100/hour. A developer can build small projects for $2,000-5,000 each. A teacher can tutor for $40-80/hour. Start with 5-10 hours/week and scale based on capacity. Platforms: Upwork, Fiverr Pro, Toptal, or direct outreach to small businesses.
Negotiate a Raise ($200-800/month)
The average raise request yields a 5-7% increase when backed by market data. On a $72,000 salary, that is $3,600-5,040 annually ($300-420/month). Time your ask after a strong performance review or completed major project. Research comparable salaries on Glassdoor, Levels.fyi, or Payscale and present a specific number, not a range.
Sell Unused Assets ($1,000-5,000 one-time)
The average American household has $3,000-5,000 in unused items. Old electronics ($200-800), furniture ($100-500), clothing ($200-600), collectibles, and sporting equipment all sell quickly on Facebook Marketplace, eBay, or Poshmark. A one-time $3,000 asset sale equals 2+ months of savings deposits.
Step-by-Step: Your 3-Year Savings Plan
Open a high-yield savings account (Day 1)
Choose a bank offering about 4.25%+ APY with no minimum balance and no monthly fees. As of mid-October 2026, example advertised rates at major online banks include roughly 4.20%-4.50% APY (shop current yields before opening). Separate this from your checking account — out of sight, out of mind. Do not get a linked debit card.
Calculate your exact monthly target (Day 1)
Use our Savings Goal Calculator with: Goal = $50,000, Timeline = 36 months, Interest Rate = your HYSA's APY. This gives you the precise monthly deposit needed. Write this number down and memorize it.
Automate the transfer (Day 2)
Set up an automatic recurring transfer from checking to your HYSA for the morning after each payday. If paid biweekly, split it: about $650/paycheck. The transfer must happen before you see the money in your checking account. This is non-negotiable — manual savings plans fail when life gets busy; automation removes the decision each month.
Audit your spending and cut the Big 3 (Week 1)
Pull 3 months of bank/credit card statements. Categorize every dollar. Focus cuts on housing, transportation, and food — these three typically total 65-75% of spending. Target $700-900/month in cuts from these categories alone. Ignore small purchases under $20/month — they are not worth the mental energy.
Start one income-boosting activity (Month 1)
Pick the highest-value side income you can start this month. Freelancing, tutoring, consulting, or a part-time gig that pays $400+/month. Dedicate the first month to getting set up and landing your first client. All side income goes directly into the HYSA — do not blend it with regular spending.
Monthly check-in: track and adjust (Every 30 days)
Every month, compare your HYSA balance to the milestone table above. If you are behind, identify why and make one specific adjustment. If ahead, consider whether you can sustain the pace or need to ease up to avoid burnout. The goal is consistency over heroics.
5 Mistakes That Derail $50,000 Savings Goals
1. Investing the money in stocks
Three years is too short for stock market risk. The S&P 500 dropped 34% in 33 days during COVID (2020) and took 6 months to recover. If your timeline coincides with a crash, you could be sitting at $33,000 when you need $50,000. A HYSA with 4.50% APY gives you guaranteed growth with zero downside.
2. Not automating transfers
Manual savings requires 36 consecutive decisions to transfer money. Each one is an opportunity to rationalize skipping "just this month." Automatic transfers remove decision fatigue entirely. NBER research on 401(k) automatic enrollment found participation in tenure months 3–15 rose from 37% to 86% when the default switched from opt-in to auto-enroll (Madrian and Shea).
3. Starting too aggressively and burning out
Saving 40% of take-home pay from day one is like running a sprint at marathon pace. By month 4, most people quit entirely. Start at 25% if needed and ramp up as you adjust. Consistency at $1,100/month for 36 months beats $1,500/month for 8 months followed by giving up.
4. No emergency fund buffer
If your car breaks down ($1,500 repair) and your only savings is the $50,000 fund, you will raid it. Keep a separate $2,000-3,000 emergency buffer in checking or a separate savings account. This prevents one bad month from derailing your entire 3-year plan. Our guide on where to keep your emergency fund explains the best account options for this buffer.
5. Ignoring lifestyle inflation during the 3 years
You get a $5,000 raise in Year 2. The temptation is to "reward yourself" with a nicer apartment or a new car. Every dollar of lifestyle inflation during your 3-year window directly reduces your savings. The raise should go into the HYSA until you hit $50,000 — then celebrate however you want.
Run Your Own Numbers
Every income and expense situation is different. Use our free calculators to find your exact monthly target and see how interest accelerates your progress.
Sources Federal Reserve G.19, credit card APR (Aug. 2026 release), FDIC deposit insurance ($250,000 per depositor, per bank), NBER Working Paper 7682, Madrian & Shea (401(k) automatic enrollment). Checked October 2026.
Frequently Asked Questions
How much do I need to save per month to reach $50,000 in 3 years?
Without any interest, you need to save $1,389 per month ($50,000 / 36 months). With a high-yield savings account earning about 4.25-4.75% APY (example top-tier online rates as of mid-October 2026), the required monthly contribution drops to roughly $1,290-$1,300 because compound interest does some of the work for you.
Can I save $50,000 in 3 years on a $60,000 salary?
It's extremely difficult but possible with aggressive lifestyle changes. On a $60,000 gross salary (about $4,200/month take-home for a single filer with no state income tax in 2026, before benefits), saving $1,389 leaves limited room for housing and essentials. You'd likely need side income of $500-800/month and tight housing costs. A more comfortable path requires either a higher salary or a longer timeline.
Where should I keep my $50,000 savings goal money?
A high-yield savings account (HYSA) is the best option for a 3-year goal. As of mid-October 2026, many top online HYSAs advertise about 4.25-4.75% APY with FDIC insurance up to $250,000 per depositor, per bank. Avoid investing this money in stocks — a 3-year timeline is too short to recover from a potential market downturn. CDs can work if you use a CD ladder strategy, but they sacrifice flexibility.
What if I fall behind on my savings goal?
Recalculate immediately. If you miss $500 one month, you need an extra $16/month across the remaining months to catch up — manageable if caught early. Consider building a one-month buffer into your plan (target $50,000 in 35 months instead of 36). Also look for one-time windfalls: tax refunds, bonuses, or selling unused items can cover gaps.
Should I pay off debt before saving $50,000?
It depends on the interest rate. Pay off credit card balances first when you are paying assessed interest — the Federal Reserve's G.19 release put the average APR on credit card accounts assessed interest at 22.36% in August 2026. No savings account matches that guaranteed cost. For student loans under 5-6%, you can save and pay simultaneously. For a car loan at 4-7%, consider minimum payments while saving. If your debt rate exceeds your HYSA rate (often about 4.25-4.75% at top online banks as of mid-October 2026), prioritize the debt.
What happens to my savings plan if HYSA rates drop?
HYSA rates can fluctuate with Federal Reserve policy. If your rate drops from 4.5% to 3.5% while you still target $50,000 in 36 months, plan on adding about $20-$25 per month to your transfer. Run the updated numbers in a savings goal calculator each quarter and adjust your automatic transfer accordingly. Even at 3.5% APY, a HYSA still beats leaving deposits in an account earning the FDIC national average savings rate (0.38% as of October 19, 2026) by roughly $3,100 in extra interest over 36 months of $1,300/month deposits.
Related Guides
The 50/30/20 Budget Rule Explained with Real Examples
Learn the 50/30/20 budget rule with real examples at $50K, $75K, and $100K income. Includes a case study, category breakdowns, and when the rule doesn't work.
High-Yield Savings Account vs CD: Which Is Better in 2026?
Compare high-yield savings accounts vs CDs with October 2026 rates. See when each wins, a $30,000 comparison, and the optimal split strategy.