Guides / Savings Strategy
Where to Keep Your Emergency Fund for the Best Interest Rate
You built a $24,000 emergency fund. Congratulations — but many households still lack a cash buffer: the Federal Reserve's 2024 SHED found 37% of adults would not cover a $400 emergency expense entirely with cash or its equivalent, and 13% could not pay by any means. But where you keep that money matters as much as how much you saved. The difference between a traditional checking account and a high-yield savings account on $25,000 is over $1,100 per year in free money — even after the Federal Reserve's recent rate cuts. This guide breaks down every option, compares real October 2026 rates, and shows you exactly where to park your cash for maximum safety and interest.
Last updated: October 2026
Source Federal Reserve SHED 2024, $400 emergency expense (May 2025 report). Checked October 2026.
TL;DR - Quick Answer
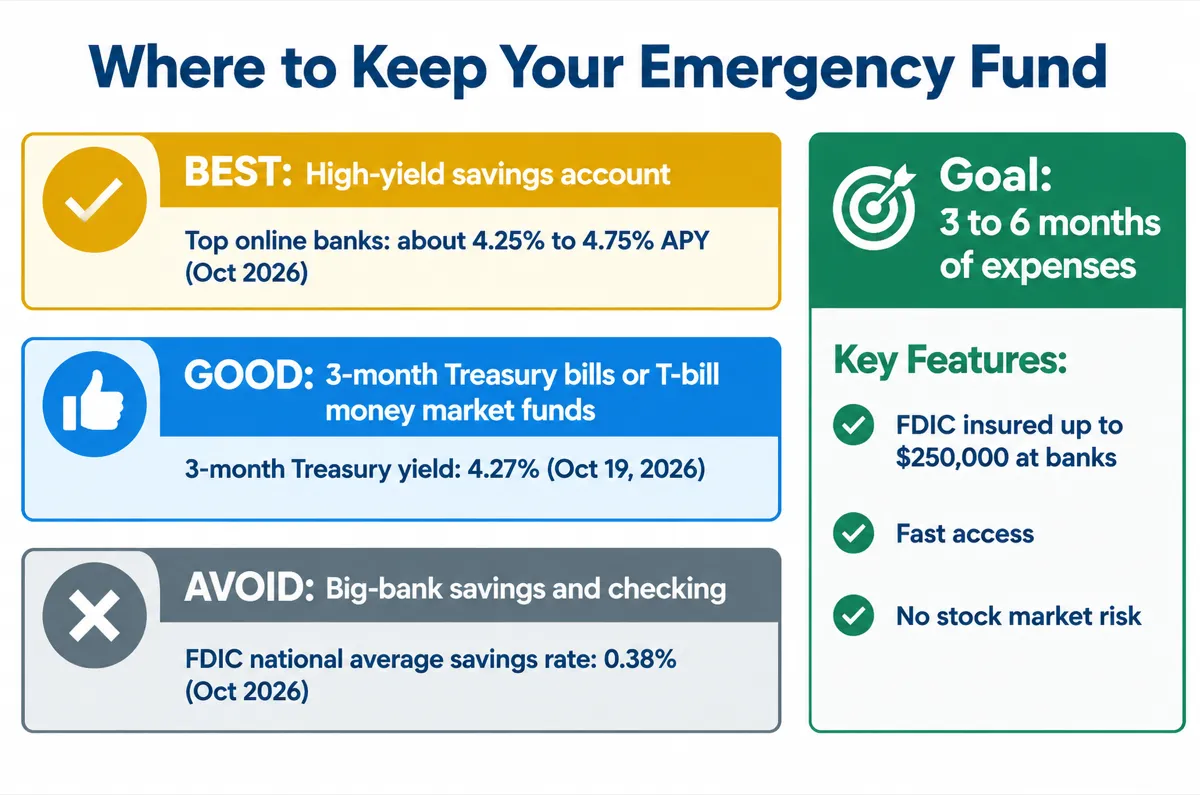
Best option: High-yield savings account at 4.2-4.75% APY. Keep 3-6 months of expenses liquid and FDIC insured.
- Target size: 3-6 months of essential expenses ($12,600-$25,200 for most households spending $4,200/month)
- Top accounts: Example advertised APYs at major online banks often fall in the roughly 4.2%-4.5% range as of mid-October 2026 (verify current rates before opening)
- Avoid: Traditional checking (0.01% APY), stocks, and single long-term CDs without a ladder strategy
- Annual gain: Moving $25,000 from checking to a 4.50% HYSA earns an extra $1,122.50 per year
Use our Emergency Fund Calculator to determine your target amount.
Why Where You Keep Your Emergency Fund Matters
Most people leave their emergency fund in the same checking account where their paycheck lands. Many branch checking accounts still pay about 0.01% APY; the FDIC national average for interest checking was 0.07% as of October 19, 2026 (savings averaged 0.38%). On a $25,000 balance at 0.01%, that is $2.50 in annual interest. Meanwhile, BLS data show all-items CPI rose 3.7% over the 12 months ending September 2026 — about $925 in purchasing power lost on $25,000 if cash earns nothing.
Move that same $25,000 to a high-yield savings account paying 4.50% APY and the math changes dramatically. You earn $1,125 per year in interest — a $1,122.50 annual difference compared to checking. Over five years, that compounds to roughly $6,300 in extra interest, enough to cover 1.5 months of expenses for someone spending $4,200 per month on essentials. Yes, HYSA rates have eased from the 5.0%+ peaks of late 2023 as the Fed has cut rates, but the gap between a HYSA and checking remains enormous.
The account type also determines access speed and safety. Your emergency fund exists for job loss, medical bills, and car repairs — events that require cash within 24-48 hours, not weeks. A brokerage account might earn 8-10% historically, but it can drop 20-30% in a recession exactly when you need the money. The right account balances three priorities: competitive interest (4.0%+ APY), instant liquidity (same-day or next-day transfers), and full principal protection (FDIC insurance up to $250,000 per depositor, per bank).
| Account Type | APY on $25,000 | Annual Interest | 5-Year Total Interest |
|---|---|---|---|
| Traditional checking | 0.01% | $2.50 | $12.50 |
| High-yield savings | 4.50% | $1,125 | $6,295 |
*5-year total assumes constant 4.50% APY with monthly compounding and no withdrawals. Example HYSA rate as of mid-October 2026; actual rates fluctuate with Federal Reserve policy.
Sources FDIC national deposit rates (Oct. 19, 2026), BLS CPI-U, 12-month change 3.7% (Sept. 2026). Checked October 2026. Checking row uses a 0.01% illustrative big-bank rate; FDIC national interest checking averaged 0.07%.
Emergency Fund Account Comparison: Every Option Ranked
Here is how every common account type stacks up for emergency fund purposes. Rates reflect October 2026 market conditions from top providers across each category. Note that yields have shifted lower since 2024 as the Federal Reserve cut the federal funds target from the 5.25%-5.50% range toward 3.75%-4.00% as of mid-October 2026.
| Account Type | APY | Liquidity | FDIC Insured | Best For |
|---|---|---|---|---|
| Traditional checking | 0.01% | Instant | Yes | Daily spending buffer ($500-1,000 max) |
| High-yield savings (HYSA) | ~4.2-4.75% (top online; FDIC avg. savings 0.38%) | Same/next day | Yes | Primary emergency fund (best default) |
| Money market account | ~4.0-4.5% (top tier; FDIC avg. money market 0.63%) | Same day (check/debit) | Yes | Those wanting check-writing access |
| Certificates of deposit (CDs) | ~4.4-4.8% (top online; FDIC avg. 12-mo. CD 1.76%) | Locked (penalty to withdraw) | Yes | CD ladder strategy only |
| Treasury bills (T-bills) | ~4.1-4.3% (Treasury 3-mo. yield, Oct. 19, 2026) | 1-3 business days | No (U.S. gov backed) | Tax-advantaged savers in high brackets |
| Series I savings bonds | 4.26% composite (May-Oct. 2026 issues; variable) | 12-month lock, 3-mo penalty if <5 yrs | No (U.S. gov backed) | Inflation hedge, not primary emergency fund |
| Brokerage (stocks/ETFs) | 8-10% avg (variable) | 1-3 business days | No (SIPC up to $500K) | Long-term investing, not emergencies |
*Top-tier HYSA/CD APYs are examples from online banks (Tier-2); FDIC national averages shown inline where applicable. I-bond composite rate is from TreasuryDirect for May 1-October 31, 2026 purchases (next fixed-rate announcement November 1, 2026). Brokerage returns are historical averages, not guaranteed.
Sources Federal Reserve, FOMC target federal funds rate, Treasury daily par yield curve (3-month 4.27%, Oct. 19, 2026), TreasuryDirect, Series I composite 4.26% (May-Oct. 2026), FDIC national deposit rates (Oct. 19, 2026). Checked October 2026.
Top 3 Options: Detailed Pros and Cons
1. High-Yield Savings Account (HYSA)
The HYSA remains the gold standard for emergency funds in late 2026. Many online banks advertise roughly 4.2%-4.5% APY as of mid-October 2026 (verify before opening — Tier-2 bank rate pages, not FDIC national averages). That compares with a 0.38% FDIC national average for savings and about 0.01% on many branch checking accounts. Most top HYSAs have no minimum balance and no monthly fees. The HYSA is still the best risk-free place for emergency cash.
Pros
- 4.2-4.75% APY on $24,000 = $1,008-$1,140/year in interest
- FDIC insured up to $250,000 per bank
- Transfers to checking in 1-2 business days (some instant)
- No market risk — principal never drops
- No early withdrawal penalties
- Can open in 10 minutes online
Cons
- Rates move with Fed policy — the target range was 3.75%-4.00% as of September 2026
- No check-writing on most HYSAs
- Some accounts limit to 6 withdrawals/month (soft limit)
- Separate from your primary bank — one extra login
- Not ideal for balances over $250,000 (FDIC limit per bank)
Verdict: Best for 80-90% of your emergency fund. Put $18,000-$22,000 of a $24,000 fund here. Even at the current lower rates, you still earn over $1,000/year on a $24,000 balance.
2. Money Market Account
Money market accounts (MMAs) function like savings accounts but typically include check-writing and debit card access. Brokerage money market funds and bank MMAs often quote yields in the same ballpark as top HYSAs as of mid-October 2026 (fund yields change daily — Tier-2). Bank MMAs carry FDIC insurance; fund-based MMAs are not FDIC insured (though they hold government securities). The FDIC national average for money market deposit accounts was 0.63% as of October 19, 2026.
Pros
- Check and debit access for emergencies
- 4.0-4.5% APY — nearly matches HYSA rates
- FDIC insured at bank MMAs
- Same-day access via debit card at ATMs
- Often pairs well with existing brokerage accounts
Cons
- Minimum balance requirements ($1,000-$2,500 at some banks)
- Debit card access makes it easier to spend impulsively
- Fund-based MMAs are not FDIC insured (but very safe)
- Slightly lower rates than top HYSAs (0.1-0.3% difference)
- Monthly fee if balance drops below minimum ($10-15/month)
Verdict: Good alternative if you want check access without sacrificing much yield. On $24,000, the 0.2-0.3% rate difference vs. a HYSA costs about $48-72/year — a small price for debit card convenience.
3. CD Ladder Strategy
A CD ladder splits your emergency fund across multiple certificates of deposit with staggered maturity dates. Instead of locking $24,000 in a single 12-month CD at 4.65% APY (and paying a 6-month interest penalty to access it early), you divide the money into 3-month, 6-month, and 12-month rungs. Each quarter, a CD matures and you can reinvest or withdraw without penalty.
Pros
- 4.4-4.8% APY — among the highest FDIC-insured cash rates available
- Rate locked for the CD term regardless of Fed cuts
- Quarterly liquidity with a 4-rung ladder
- Disciplined structure prevents impulsive spending
- Works well for funds above $15,000
Cons
- Early withdrawal penalty: 3-6 months of interest
- More complex to manage than a single HYSA
- Not suitable for the first $5,000-$8,000 (keep that liquid)
- Requires reinvestment action every 3-6 months
- Opportunity cost if rates rise after you lock in
Verdict: Best as a supplement to a HYSA, not a replacement. Use for the portion of your fund you are confident you will not need for 90+ days.
Case Study: Amanda, 34, Nurse, $78K in Phoenix
Her Situation
- Age: 34, registered nurse at Banner Health
- Gross salary: $78,000/year ($6,500/month)
- Take-home after taxes/benefits: $4,850/month
- Monthly essentials: $4,200 (rent $1,750, car $420, food $580, insurance $400, utilities $190, minimum debt $860)
- Target emergency fund: 6 months = $25,200
- Current savings: $25,200 (goal reached after 18 months of saving $1,400/month)
- Previously kept entire fund in branch checking at about 0.01% APY
Her New Structure
- $4,200 in Wells Fargo checking (1 month buffer + daily spending)
- $15,000 in an online HYSA at 4.20% APY (example rate; 3.6 months of expenses, instant transfer)
- $6,000 in CD ladder across Ally (2 rungs: $3,000 in 6-month CD at 4.50% APY, $3,000 in 12-month CD at 4.65% APY)
Annual Interest Comparison
Old setup (all checking)
$2.52/year
New setup (split accounts)
$905/year
Annual gain
+$902.48
Amanda's restructure took 45 minutes total — 15 minutes to open the Ally HYSA, 15 minutes to initiate the $21,000 transfer from Wells Fargo, and 15 minutes to set up the 2-rung CD ladder. Her $15,000 HYSA earns $630/year at 4.20% APY. Her $6,000 in CDs earns $275/year (blended 4.58% APY). The $4,200 in checking earns $0.42/year — but gives her instant access for a flat tire or urgent copay without touching the higher-yield accounts.
When her 6-month CD matured in April 2026, she rolled the $3,068 ($3,000 principal + $68 interest) into a new 12-month CD at 4.65% APY. She kept the matured funds in her HYSA for 2 weeks while comparing rates, then locked in the new CD. This rolling strategy ensures she always has either a CD maturing or $15,000+ available in her HYSA within 24 hours.
The CD Ladder Strategy Explained With Numbers
A CD ladder works by dividing your emergency fund into equal portions across CDs with different maturity dates. Here is a 4-rung ladder for $16,000 of Amanda's fund (keeping $9,200 in HYSA for instant access):
| Rung | Amount | Term | APY | Maturity Value | Matures |
|---|---|---|---|---|---|
| Rung 1 | $4,000 | 3 months | 4.30% | $4,043 | January 2027 |
| Rung 2 | $4,000 | 6 months | 4.50% | $4,090 | April 2027 |
| Rung 3 | $4,000 | 9 months | 4.60% | $4,138 | July 2027 |
| Rung 4 | $4,000 | 12 months | 4.65% | $4,186 | October 2027 |
Total interest earned across all 4 rungs in the first year: $455 on $16,000 (stated APYs on the rungs average about 4.51%). Compare that to leaving $16,000 in checking at 0.01% APY, which earns $1.60. The ladder generates about $453 more per year while providing access to $4,000 every 3 months without early withdrawal penalties.
When Rung 1 matures in January 2027, Amanda has three choices: withdraw the $4,043 if she needs it, roll it into a new 12-month CD at the current rate, or move it to her HYSA. Most months she reinvests into a new 12-month CD, creating a self-perpetuating ladder where one CD matures every quarter. Use our CD Calculator to model different ladder configurations and see exact maturity values.
CD Ladder Rule of Thumb
Never put more than 50-67% of your emergency fund in CDs. Keep the remaining 33-50% ($8,400-$12,600 of a $25,200 fund) in a HYSA for same-day access. If you need $6,000 for an emergency root canal and your next CD does not mature for 8 weeks, the HYSA covers you without penalty.
3 Common Emergency Fund Mistakes
1. Keeping too much in checking
The Federal Reserve's 2022 Survey of Consumer Finances put the median transaction-account balance at $8,000 (checking, savings, and similar accounts combined)—and many households still park most of that in low-yield checking. At 0.01% APY, $25,200 in checking earns $2.52 per year. That same $25,200 in a 4.20% HYSA earns $1,058 per year. The $1,055.48 you leave on the table annually equals 26 days of groceries for a household spending $580/month on food. Keep $500-1,000 in checking for immediate needs and move the rest today. The transfer takes 5 minutes and the interest starts accruing immediately.
2. Investing your emergency fund in stocks
Stocks average 8-10% returns long-term, so investing a $25,200 emergency fund seems smart — until you need the money during a downturn. In 2022, the S&P 500 Total Return Index fell 18.1% for the calendar year. A $25,200 portfolio would have fallen to about $20,639 — a $4,561 shortfall when covering 6 months of $4,200/month expenses. Job losses and market crashes correlate: companies lay off workers during recessions, exactly when your portfolio is down 15-25%. Emergency funds must prioritize stability over growth. A 4.20% HYSA guarantees your $25,200 stays $25,200 while still earning over $1,058 per year in interest.
3. Not having an emergency fund at all
A Bankrate survey (January 2025, Tier-2) found 59% of U.S. adults would not pay a $1,000 emergency expense from savings alone. Without a fund, a $2,400 transmission repair goes on a credit card at the average assessed-interest APR (22.36% in August 2026, Federal Reserve G.19) — costing hundreds in finance charges if you carry the balance. The math is unforgiving: a single $3,000 surprise expense on credit at about 22% APR costs roughly $370 in interest over one year if unpaid. Building even a $1,000 starter fund in a HYSA (requiring just $167/month for 6 months) breaks the cycle of debt for most unexpected costs.
Calculate Your Emergency Fund Target
Before choosing where to keep your money, know how much you need. Our free calculators help you set the right target and plan how long it takes to get there.
Sources FDIC deposit insurance ($250,000 per depositor, per bank), NCUA share insurance ($250,000 standard maximum), Federal Reserve G.19, credit card APR (Aug. 2026 release), Bankrate emergency savings survey (Jan. 23, 2025; Tier-2), Federal Reserve SCF 2022, median transaction account $8,000 (Oct. 2023). Checked October 2026.
Frequently Asked Questions
Where is the best place to keep an emergency fund in 2026?
A high-yield savings account (HYSA) remains the best default for most people. As of mid-October 2026, many top online banks advertise about 4.2-4.75% APY with FDIC insurance up to $250,000 per depositor, per bank. That is far above the FDIC national average savings rate of 0.38% (October 19, 2026). You get same-day or next-day access to your money without market risk. Keep 3-6 months of essential expenses in a HYSA and avoid keeping more than $500-1,000 in a traditional checking account.
Should I keep my emergency fund in a checking account?
No — not beyond a small buffer for immediate needs. A traditional checking account at a big bank pays roughly 0.01% APY. On a $25,000 balance, that earns $2.50 per year. The same $25,000 in a 4.50% APY HYSA earns $1,125 per year — a $1,122.50 difference. Keep $500-1,000 in checking for same-day transactions and park the rest in a HYSA.
Can I use a CD for my emergency fund?
Only with a CD ladder strategy, not a single long-term CD. A 12-month CD might pay 4.4-4.8% APY as of October 2026, but early withdrawal penalties typically cost 3-6 months of interest. A 3-rung ladder — splitting funds across 3-month, 6-month, and 12-month CDs — gives you quarterly liquidity while locking in higher rates than checking. Keep at least 1 month of expenses ($3,000-5,000 for most households) in a HYSA for instant access. Note that CD rates have edged lower since mid-2024, so a HYSA may now offer a comparable yield with far better flexibility.
Is it safe to invest my emergency fund in stocks or ETFs?
No. Emergency funds must be liquid and stable. The S&P 500 dropped 34% in 33 days during March 2020. If you lost your job during that crash, you would be forced to sell investments at a loss to cover rent and groceries. A $24,000 emergency fund invested in stocks could have dropped to $15,840 — leaving you $8,160 short when you needed the money most. Keep emergency money in FDIC-insured cash accounts.
How much should I keep in my emergency fund?
Most financial planners recommend 3-6 months of essential expenses — not gross income. If your monthly essentials (housing, food, insurance, minimum debt payments, utilities) total $4,200, target $12,600-$25,200. Single-income households and freelancers should aim for 6 months ($25,200 on $4,200/month expenses). Dual-income households with stable jobs can often target 3 months ($12,600). Use our Emergency Fund Calculator to find your exact number.
What happens to my emergency fund rates when the Fed cuts rates?
When the Federal Reserve lowers the federal funds rate, HYSA and money market APYs usually follow within a few weeks. The FOMC target range stood at 3.75%-4.00% after the September 17, 2026 cut, down from the 5.25%-5.50% range that prevailed in much of 2023-2024. Existing CDs keep their locked rate until maturity — one advantage of a CD ladder. Even at 4.25% APY, a HYSA earns $1,062 per year on $25,000 versus $17.50 at the FDIC national average for interest checking (0.07%, October 19, 2026).
Related Guides
High-Yield Savings Account vs CD: Which Is Better in 2026?
Compare high-yield savings accounts vs CDs with October 2026 rates. See when each wins, a $30,000 comparison, and the optimal split strategy.
The 50/30/20 Budget Rule Explained with Real Examples
Learn the 50/30/20 budget rule with real examples at $50K, $75K, and $100K income. Includes a case study, category breakdowns, and when the rule doesn't work.