Guides / Budgeting
The 50/30/20 Budget Rule Explained with Real Examples
Most budgeting advice fails because it is too complicated to stick with. The 50/30/20 budget rule solves that by dividing your take-home pay into three simple buckets: half for needs, nearly a third for wants, and a fifth for savings. This guide shows you exactly how it works — with real dollar amounts at three income levels and a full before-and-after case study.
Last updated: October 2026
TL;DR - Quick Answer
- 50% Needs: Housing, utilities, groceries, insurance, transportation, minimum debt payments
- 30% Wants: Dining out, entertainment, hobbies, subscriptions, non-essential shopping
- 20% Savings: Emergency fund, retirement contributions, investments, extra debt payoff
- Base it on take-home pay — not your gross salary
Use our 50/30/20 Budget Calculator and Savings Goal Calculator to build your personalized split.
What Is the 50/30/20 Budget Rule?
The 50/30/20 budget rule is a percentage-based budgeting framework that divides your after-tax income into three categories. Senator Elizabeth Warren and Amelia Warren Tyagi introduced it in their 2005 book All Your Worth: The Ultimate Lifetime Money Plan, and it has since become one of the most widely recommended budgeting methods because of its simplicity.
Source Elizabeth Warren & Amelia Warren Tyagi, All Your Worth (Free Press, 2005). Checked October 2026. Tier-2 bibliographic record; the 50/30/20 split is defined in the book itself.
Unlike line-item budgets that track dozens of categories, the 50/30/20 rule gives you three numbers to remember. Every time you get paid, you mentally (or automatically) route money into needs, wants, and savings. There is no spreadsheet required after the initial setup — which is exactly why people actually follow it.
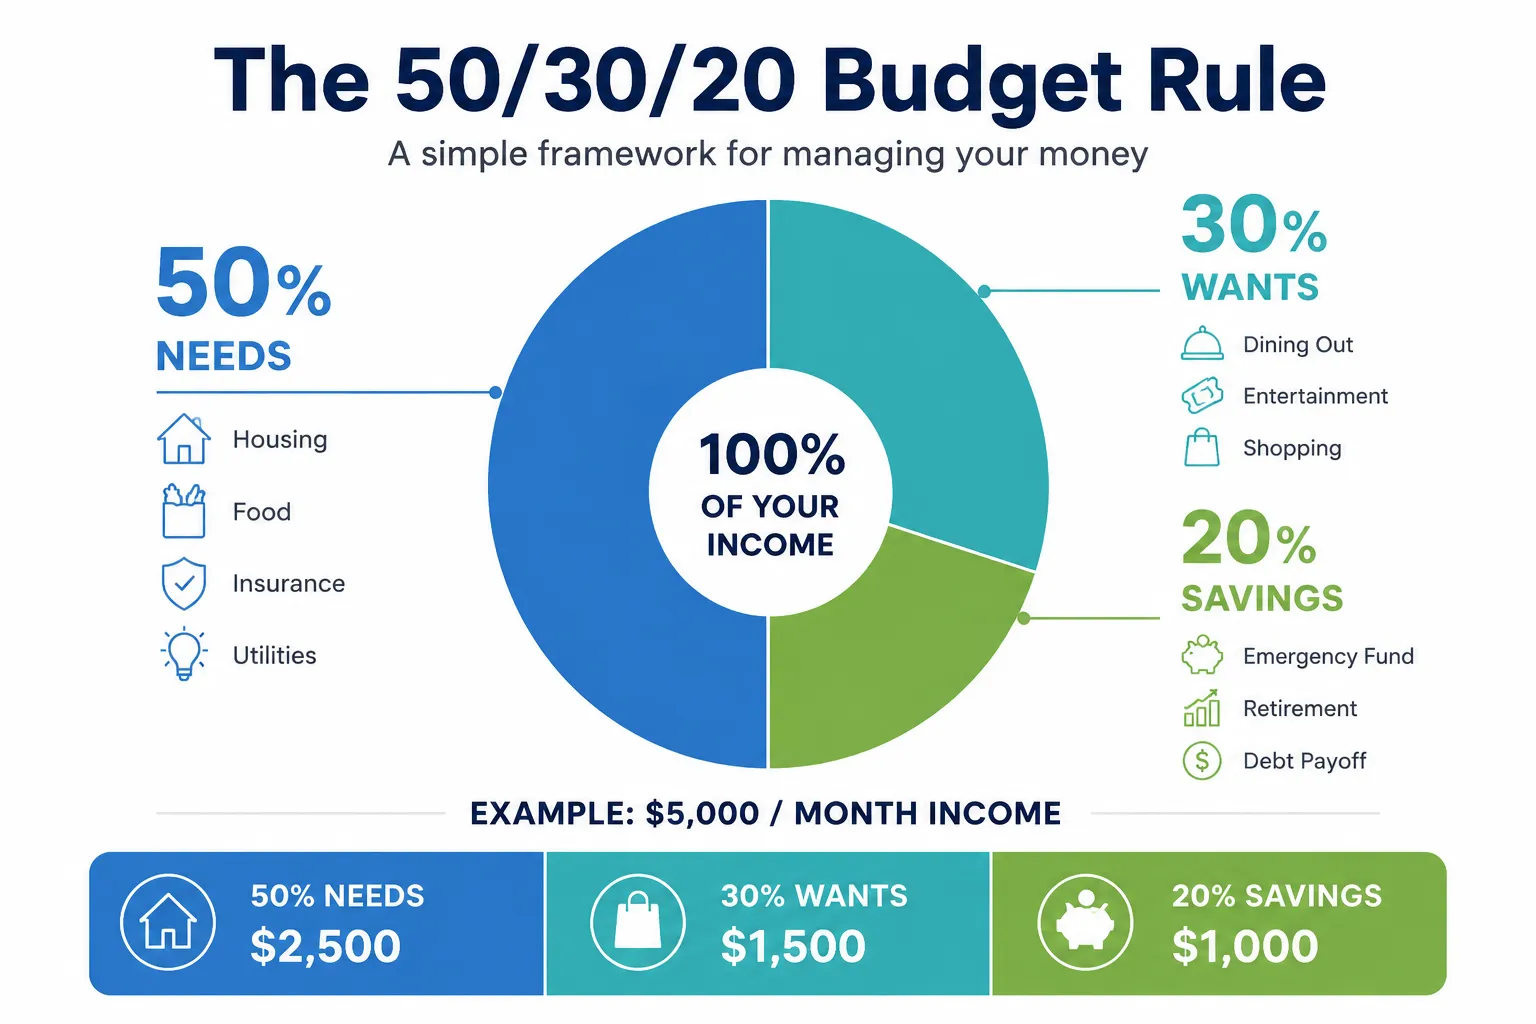
Here is the core split applied to a $5,000/month take-home paycheck:
50%
Needs
$2,500
Non-negotiable living expenses
30%
Wants
$1,500
Lifestyle and discretionary spending
20%
Savings
$1,000
Future you: emergency fund, retirement, debt payoff
The power of this framework is that it builds savings into every paycheck by default. You are not saving "whatever is left over" at the end of the month — which, for most people, is zero. Savings get funded first alongside your needs, not last.
What Goes in Each Category: Detailed Breakdown
The most common question about the 50/30/20 budget rule is where specific expenses belong. Some items sit in a gray zone — a car payment might be a need if you commute, but a want if you bought more car than necessary. Use this table as your starting reference, then adjust based on your situation.
| Category | Needs (50%) | Wants (30%) | Savings (20%) |
|---|---|---|---|
| Housing | Rent, mortgage, property taxes, HOA fees | — | — |
| Utilities | Electric, gas, water, internet, cell phone (basic plan) | Premium phone upgrades, cable TV | — |
| Food | Groceries, meal prep ingredients | Restaurants, delivery, coffee shops | — |
| Transportation | Car payment (basic), gas, insurance, transit pass, maintenance | Rideshares, luxury car upgrade, recreational travel | — |
| Insurance | Health, auto, renters/homeowners (required coverage) | — | — |
| Debt | Minimum payments on all loans and credit cards | — | Extra payments beyond minimums |
| Entertainment | — | Streaming, concerts, hobbies, gym, vacations | — |
| Personal | Basic clothing for work | Non-essential shopping, beauty, gifts | — |
| Future Goals | — | — | Emergency fund, 401(k), IRA, HSA, brokerage account, HYSA |
*Minimum debt payments count as needs because failing to pay them damages your credit and triggers penalties. Any amount above the minimum belongs in the 20% savings/debt bucket.
For context, the BLS Consumer Expenditure Survey (2024) shows the average U.S. household spends about 33.4% on housing, 17.0% on transportation, 12.9% on food, and 7.9% on healthcare — roughly 71% combined before insurance, debt, and other needs. That is why the 50% needs bucket is a target, not a description of how most households already spend.
Sources BLS Consumer Expenditures 2024 news release (Dec. 19, 2025), BLS Economics Daily (Feb. 2026) — housing & transportation shares, BLS CPI news release (Jan. 13, 2026) — shelter +3.2% YoY, Dec. 2025. Checked October 2026.
Real Examples at Three Take-Home Income Levels
The 50/30/20 budget rule only makes sense when you see it applied to real numbers. Below are monthly breakdowns for three common take-home income levels. These figures use after-tax pay — the amount deposited into your checking account each month.
| Take-Home Income | Needs (50%) | Wants (30%) | Savings (20%) |
|---|---|---|---|
| $50,000/year ($4,167/mo) | $2,083 | $1,250 | $833 |
| $75,000/year ($6,250/mo) | $3,125 | $1,875 | $1,250 |
| $100,000/year ($8,333/mo) | $4,167 | $2,500 | $1,667 |
$50,000 Take-Home ($4,167/month)
At this income level, the 50/30/20 budget rule is tight but achievable in most mid-size cities. A realistic allocation might look like: $1,100 rent, $150 utilities, $350 groceries, $280 transportation, $103 insurance minimums, and $100 phone — totaling $2,083 in needs. Wants include $400 dining out, $300 entertainment, $250 personal shopping, and $300 miscellaneous fun. The $833 savings bucket might split into $400 emergency fund, $250 retirement (401k or IRA), and $183 extra student loan payment.
$75,000 Take-Home ($6,250/month)
This is where the rule starts feeling comfortable. Needs at $3,125 can cover a $1,600 mortgage or rent, $200 utilities, $450 groceries, $400 car costs, $275 insurance, and $200 in minimum debt payments. Wants at $1,875 leave room for $600 dining, $400 entertainment, $375 hobbies, and $500 travel savings. The $1,250 savings bucket could fund $500 to a 401(k), $300 to an HYSA emergency fund, $250 to a Roth IRA, and $200 toward extra debt payoff.
$100,000 Take-Home ($8,333/month)
At six figures take-home, the 20% savings allocation equals $1,667/month — $20,000 per year without touching wants. Needs at $4,167 comfortably cover a $2,200 housing payment, $250 utilities, $550 groceries, $500 transportation, $417 insurance, and $250 phone. Wants at $2,500 support a genuinely enjoyable lifestyle: $800 dining and social, $500 entertainment, $600 travel, and $600 personal spending. Savings of $1,667 might allocate $800 to retirement, $400 emergency fund, $267 taxable investments, and $200 HSA contributions.
Case Study: Tyler, 27, $61.5K Salary in Denver
Tyler earns $61,500 as a project coordinator in Denver (illustrative). After federal taxes, Colorado's flat 4.4% state income tax (2026 withholding tables), FICA (7.65%), and his employer health plan contribution, he takes home $4,050 per month. He heard about the 50/30/20 budget rule on a podcast and decided to audit his spending. What he found was a common pattern: needs consuming 71% of his income, wants at 24%, and savings at just 5%.
Before: Tyler's Budget
Split: 71% needs / 24% wants / 5% savings
- Rent (1BR, Capitol Hill): $1,620
- Utilities + internet: $185
- Groceries: $435
- Car payment + insurance + gas: $710
- Health insurance (employee share): $230
- Student loan (minimum): $285
- Phone: $85
- Needs subtotal: $3,550
- Dining out + delivery: $460
- Entertainment + streaming: $215
- Shopping + subscriptions: $280
- Gym: $55
- Wants subtotal: $1,010
- Savings (inconsistent): $200
- Total: $4,760 (deficit covered by credit card)
After: Tyler's 50/30/20 Budget
Target: $2,025 needs / $1,215 wants / $810 savings
- Rent (roommate, shared 2BR): $950
- Utilities + internet (split): $120
- Groceries (meal prep): $310
- Car payment + insurance + gas: $540
- Health insurance: $230
- Student loan (minimum): $285
- Phone (switched to Mint Mobile): $55
- Needs subtotal: $2,490
- Dining out (2x/week max): $270
- Entertainment + streaming: $170
- Personal shopping: $125
- Gym (budget gym): $40
- Hobbies + social: $190
- Wants subtotal: $795
- Emergency fund (dedicated savings): $310
- 401(k) (4% + 3% employer match): $340
- Extra student loan payment: $155
- Savings subtotal: $805
What Tyler Changed
Tyler's biggest move was finding a roommate, cutting rent from $1,620 to $950 — a $670/month savings that alone closed most of his budget gap. He switched phone carriers ($30 saved), meal-prepped Sundays ($125 saved on groceries), and capped dining out at twice per week ($190 saved). He enrolled in his employer's 401(k) to capture the full 3% match, which effectively adds $153/month in free money. He also moved his emergency fund to a dedicated savings account instead of leaving it in checking. The BEA personal saving rate was 4.1% in August 2026 — well below the 20% savings bucket this rule targets.
Tyler did not hit a perfect 50/30/20 split — his needs still land at 61% because Denver rent is expensive even with a roommate. But he moved from a $710/month credit card deficit to a balanced budget with $805 in monthly savings. Over 12 months, that $805/month builds a $9,660 emergency fund while paying down $1,860 in extra student loan principal.
Key Takeaway
Tyler's story shows the 50/30/20 budget rule works best as a direction, not a destination. Getting from 71/24/5 to 61/20/20 was a massive improvement — saving $9,660 per year versus going $710/month deeper into credit card debt. He plans to revisit his split when he gets his next raise or finds a cheaper apartment. Even a $3,000 raise (roughly 5%) would add $187/month to savings after taxes, pushing his total savings rate toward 24%.
Sources Colorado DOR, 2026 estimated tax worksheet (4.4%), BEA, Personal Income and Outlays (Aug. 2026) — 4.1% saving rate. Checked October 2026. Tyler is an illustrative single filer; take-home is rounded.
When the 50/30/20 Rule Doesn't Work
The 50/30/20 budget rule is an excellent starting point, but it assumes a middle-class income in a reasonably affordable area. Several situations make the standard ratios impossible — and pretending otherwise leads to frustration and abandoned budgets.
High Cost-of-Living Areas
In expensive metros, rent alone can exceed half of take-home pay. Census median household income was $83,730 in 2024 (money income, pretax), while BLS data show housing absorbs one-third of average household spending nationwide — and more in coastal cities. On a $6,250 take-home paycheck, even $2,000 rent is 32% before groceries, insurance, or transportation. Residents in these cities often use a modified 60/20/20 or 65/15/20 split until income rises or housing costs stabilize.
Heavy Debt Loads
If you carry $40,000 in credit card debt at the Federal Reserve G.19 average APR of 22.36% for accounts assessed interest (August 2026), minimum payments alone might be $850-$1,100/month — potentially more than your entire 50% needs bucket. In this case, prioritize debt payoff over the standard split. A temporary 50/10/40 approach (50% needs, 10% wants, 40% debt payoff) may be necessary until high-interest debt is eliminated. Shop 0% APR balance-transfer offers carefully; terms and fees change often.
Low or Irregular Income
Freelancers, gig workers, and commission-based earners face income swings that make fixed percentages difficult. If your monthly income ranges from $2,800 to $5,200, budget using your lowest expected month as the baseline. In good months, route the surplus entirely to savings rather than inflating wants.
Single Income, Dependents
Childcare can rival rent in many metros. A parent earning $4,167 take-home with $1,400 rent and $1,200 childcare has only $567 left for all other needs before wants or savings. The 50/30/20 budget rule was popularized for dual-income households without young dependents — adjust expectations accordingly.
If you are in one of these situations, do not abandon budgeting entirely. Use the framework as a target to move toward, not a standard you must meet today. Even shifting from 80/15/5 to 65/20/15 represents meaningful financial progress. If housing costs are your biggest obstacle, understanding your debt-to-income ratio can help you set realistic targets and identify when refinancing or downsizing would make the biggest impact.
Sources Census, Income in the United States: 2024 ($83,730 median), Federal Reserve G.19 (Aug. 2026) — credit card APR 22.36%. Checked October 2026.
How to Implement the 50/30/20 Rule: Step by Step
Setting up the 50/30/20 budget rule takes about two hours upfront. After that, maintenance is minimal — especially if you automate transfers. Follow these six steps in order.
Calculate your exact take-home pay
Look at your last three paychecks and average the net deposit amount. If you are paid biweekly, multiply by 26 and divide by 12 to get your monthly figure. For Tyler at $61.5K in Denver, that number is $4,050/month. Do not use your gross salary — the 50/30/20 budget rule is always based on what you actually receive.
Run your numbers through the calculator
Enter your take-home pay into our 50/30/20 Budget Calculator. It instantly shows your three dollar targets. Write these three numbers on a sticky note: needs, wants, savings. At $4,050 take-home, that is $2,025 / $1,215 / $810.
Audit your last 90 days of spending
Pull bank and credit card statements for the past three months. Categorize every transaction as need, want, or savings/debt. Calculate your current split. Most people discover they are at 65/30/5 or 70/25/5 — far from the target. This gap analysis tells you exactly where to focus.
Set up separate accounts (or virtual buckets)
Open a dedicated savings account for your 20% bucket. Some banks like Ally and Capital One 360 let you create sub-savings accounts labeled "Emergency," "Retirement," and "Goals." For wants, consider a separate checking account or a prepaid debit card loaded with your monthly $1,215 (or whatever your wants target is). When the wants account hits zero, you stop spending on discretionary items until next month.
Automate savings on payday
Schedule an automatic transfer of your 20% savings amount for the morning after each payday. If paid biweekly at $810/month savings, transfer $405 per paycheck. This happens before you have a chance to spend it. Use our Savings Goal Calculator to set specific targets — like building a $10,000 emergency fund in 14 months at $714/month.
Review and adjust monthly
On the first of each month, spend 15 minutes comparing your actual spending to your three targets. If needs ran over, identify one specific cut for next month. If wants came in under budget, do not roll the surplus into more wants — redirect it to savings. After three months, most people find the rhythm becomes automatic.
50/30/20 vs Other Budgeting Methods
The 50/30/20 budget rule is not the only approach. Here is how it compares to two popular alternatives so you can pick the right fit.
| Method | Best For | Drawback |
|---|---|---|
| 50/30/20 Rule | Beginners, steady income, balanced lifestyle | Too rigid for HCOL areas or heavy debt |
| Zero-Based Budget | Detail-oriented people, tight budgets, debt payoff | Time-intensive, 2-3 hours/month maintenance |
| Pay Yourself First | High earners, strong savers, simple automation | No guidance on needs vs wants spending limits |
| Envelope System | Cash-heavy spenders, overspending habit breakers | Impractical for online bills, hard to track digitally |
If you are new to budgeting, start with 50/30/20. It requires the least ongoing effort and builds the savings habit immediately. You can always graduate to zero-based budgeting later if you need tighter control during a debt payoff sprint or savings push. The envelope system — whether physical cash envelopes or digital equivalents in apps like Goodbudget — can help if your main problem is overspending in specific categories like dining out or entertainment, but most people find the three-bucket simplicity of the 50/30/20 approach more sustainable long-term.
The BEA personal saving rate was 4.1% in August 2026 — far below the 20% savings bucket this rule targets — so most households need deliberate automation to hit 20%. The takeaway: the best budget is the one you actually follow. Start simple, then add complexity only if you need it. For more on building sustainable savings habits, read our guide to saving $50,000 in 3 years.
Sources BEA, Personal Income and Outlays (Aug. 2026), CFPB, An essential guide to building an emergency fund, Federal Reserve SHED (2025) — 55% with 3 months emergency savings, CFPB Your Money, Your Goals toolkit — $500 then $1,000 emergency fund goals. Checked October 2026.
Build Your 50/30/20 Budget Now
Enter your take-home pay and get your exact needs, wants, and savings targets in seconds. Then set a savings goal and see how your 20% bucket grows over time.
Frequently Asked Questions
What is the 50/30/20 budget rule?
The 50/30/20 budget rule splits your after-tax (take-home) income into three buckets: 50% for needs (housing, groceries, insurance, minimum debt payments), 30% for wants (dining out, entertainment, hobbies), and 20% for savings and extra debt payoff (emergency fund, retirement, investments). It was popularized by Senator Elizabeth Warren in the book All Your Worth.
Is the 50/30/20 rule based on gross or net income?
Always use net (take-home) income — the amount that actually hits your bank account after taxes, health insurance premiums, and other payroll deductions. Using gross income makes every category look artificially large and leads to overspending. If you earn $75,000 gross but take home $5,200/month, your 50% needs bucket is $2,600, not $3,125.
What counts as a need vs a want?
Needs are expenses you must pay to survive and maintain employment: rent/mortgage, utilities, groceries, transportation to work, health insurance, and minimum debt payments. Wants are discretionary: streaming services, restaurants, vacations, gym memberships beyond basic fitness, and non-essential shopping. The gray area (like a car payment on a luxury vehicle) often gets reclassified during budget audits.
Does the 50/30/20 rule work in expensive cities?
Often not at standard ratios. BLS Consumer Expenditure Survey data (2024) show U.S. households already spend about 33% on housing alone — before insurance, debt, and other needs — so high-rent metros can push housing well above half of take-home pay. Many residents adapt to a 60/20/20 or 70/20/10 split temporarily, then adjust as income rises or housing costs stabilize. The rule is a starting framework, not a rigid law.
What if my needs already exceed 50% of my income?
You are not alone — as of mid-October 2026, BLS data show the CPI shelter index rose 3.2% year-over-year through December 2025, and the average U.S. household already directs 33.4% of spending to housing (2024 Consumer Expenditure Survey), before counting other needs. Focus on the biggest levers first: reduce housing (roommate, smaller place, refinancing when rates make sense), transportation (sell car, use transit), and food costs. Temporarily cut wants to 15-20% and savings to 10-15% while you close the gap. The goal is progress toward balance, not perfection on day one.
How much should I have in emergency savings before following the 50/30/20 rule?
The CFPB suggests building toward $500, then $1,000, as starter emergency savings before larger goals. The Federal Reserve's 2025 SHED survey found 55% of adults had at least three months of expenses saved. Once you have a baseline, work toward 3-6 months of essential expenses (your needs bucket total). At $2,500/month in needs, that means $7,500-$15,000. Keep this in a separate, accessible account (bank or credit union, per CFPB guidance). Only after this buffer is built should you redirect savings toward investments or accelerated debt payoff.
What apps or tools can automate the 50/30/20 budget?
Several free and low-cost tools can automate the 50/30/20 split. YNAB ($14.99/month) lets you create three category groups matching needs, wants, and savings — it auto-imports transactions from linked bank accounts. Monarch Money ($9.99/month or $99/year) has a built-in 50/30/20 template that color-codes spending in real time. For a free option, many banks now offer built-in budgeting tools: Ally Bank's spending buckets, Capital One's auto-categorization, and SoFi's Relay dashboard all support percentage-based budgets. The simplest no-app approach is opening three separate accounts (needs checking, wants checking, savings HYSA) and setting up automatic transfers on payday.
Related Guides
How to Save $50,000 in 3 Years: A Realistic Plan
A step-by-step plan to save $50,000 in 3 years on an average salary. Includes monthly targets, budget breakdowns, a real case study, and strategies that actually work.
Where to Keep Your Emergency Fund for the Best Interest Rate
Compare HYSAs, money market accounts, CDs, and more for your emergency fund. Real October 2026 APY rates, a case study, and the CD ladder strategy explained.