Guides / Retirement Planning
How Much Do I Need to Retire at 55? A Complete Breakdown
Retiring at 55 sounds like freedom — but it requires a portfolio large enough to cover 30-40 years of expenses, a decade of healthcare before Medicare kicks in, and a withdrawal strategy that avoids early withdrawal penalties. This guide gives you the exact numbers, a real case study, and a step-by-step plan to get there.
Last updated: October 2026
TL;DR - Quick Answer
- Most people need: About $1.9 million - $3.1 million to retire at 55 comfortably (spending plus a healthcare reserve)
- The 4% rule of thumb: Withdraw 4% of your portfolio in year one ($80,000/year from a $2 million portfolio) — often trimmed to 3.25-3.5% for longer retirements
- Healthcare gap: Budget an extra $500,000-$650,000 for the 10 years before Medicare at 65 (2026 unsubsidized ACA premiums rose sharply after enhanced credits expired)
- Conservative target: Use 3.5% withdrawal rate for a 35-40 year retirement horizon
Run your numbers with our Retirement Calculator, FIRE Calculator, and Compound Interest Calculator.
The Math Behind Retiring at 55
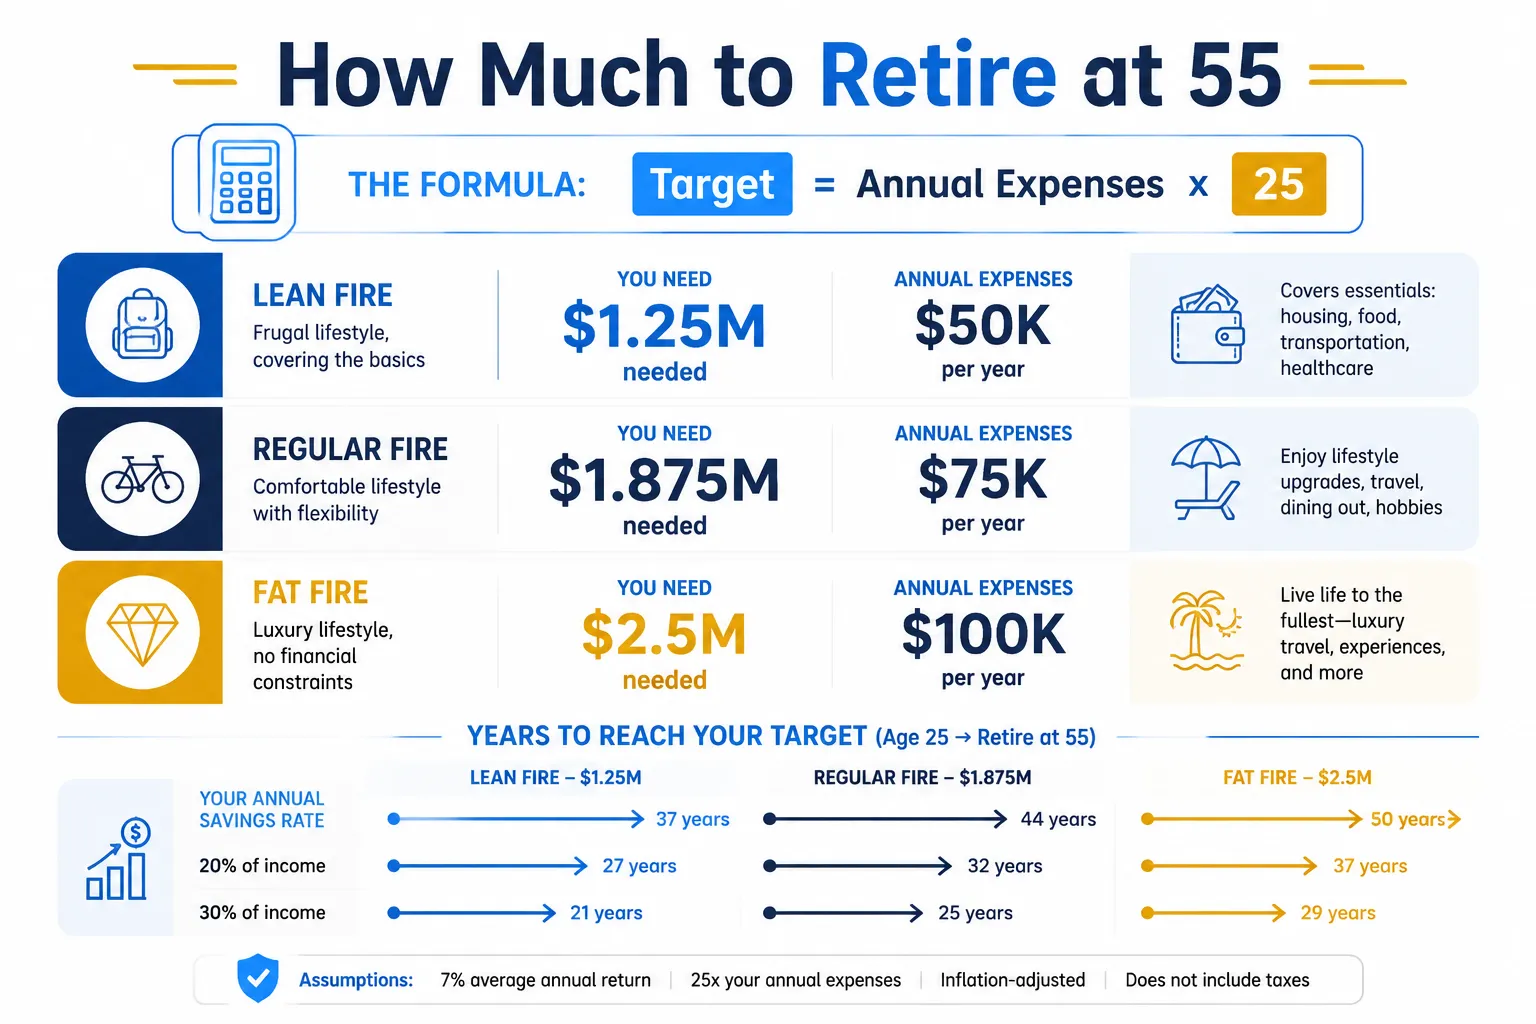
Every retirement number starts with one question: how much will you spend each year? Once you know that, you can work backward to the portfolio size you need. The most widely cited framework is the 4% rule — but retiring at 55 requires adjustments that most standard retirement advice ignores.
The 4% Rule Explained
The 4% rule says you can withdraw 4% of your portfolio in the first year of retirement, then adjust for inflation each year, with a high probability your money lasts 30 years. The formula is simple:
Example: $80,000/year spending → $80,000 / 0.04 = $2,000,000
William Bengen's 1994 research and the later Trinity Study (Tier-2 summaries) tested withdrawal rates against historical U.S. stock and bond returns. A 4% initial withdrawal, adjusted for inflation, held up in many — but not all — 30-year U.S. historical windows. Treat it as a starting point, not a guarantee. The key word is 30 years.
Source William Bengen, Journal of Financial Planning (Oct. 1994 reprint PDF) — Tier-2. Checked October 2026. Historical simulation; not an IRS or SSA rule.
Why 55 Means a 30-40 Year Horizon
Retire at 65 and you need your money to last roughly 25-30 years. Retire at 55 and you are planning for 35-40 years — possibly longer if you have longevity in your family. Every additional year of retirement increases the risk of a bad sequence of returns (a market crash early in retirement) depleting your portfolio.
The practical adjustment: use a 3.25-3.5% withdrawal rate instead of 4%. That changes the math significantly:
| Annual Spending | At 4% Rule | At 3.5% Rule (Safer) |
|---|---|---|
| $50,000 | $1,250,000 | $1,428,571 |
| $80,000 | $2,000,000 | $2,285,714 |
| $120,000 | $3,000,000 | $3,428,571 |
The Healthcare Gap Before Medicare
Medicare eligibility generally begins at 65 (CMS). Retire at 55 and you are on your own for a full decade of health insurance — the single biggest financial wildcard for early retirees. Employer-sponsored coverage disappears, and with the expiration of enhanced ACA premium tax credits after 2025, unsubsidized benchmark Silver premiums for 2026 often exceed $1,000/month nationally for people in their late 50s (about $625/month at age 40 and roughly $1,327/month at age 60 on the national weighted average before subsidies, per KFF benchmark data as of mid-October 2026).
The 10-Year Penalty (2026 Update)
At roughly $1,250-$1,400/month in combined premiums and routine out-of-pocket costs for a single early retiree (ages 55-64, national averages), the decade before Medicare can cost $150,000-$170,000 in today's dollars — more for couples or high-premium states like Wyoming or West Virginia. Capitalizing about $18,000-$22,000 per year of healthcare spending at a 3.5% withdrawal rate implies an extra $500,000-$630,000 in portfolio reserve. KFF (Tier-2) pegs gross 2026 benchmark premium increases at about 26% on average after enhanced credits expired.
Sources CMS, Medicare eligibility overview, KFF Quick Take (Oct. 28, 2025) — ~26% average 2026 ACA gross premium increase, KFF State Health Facts — 2026 U.S. benchmark premium ($625/mo, age 40), CMS — federal default ACA age rating factors (May 2017). Checked October 2026. Age-60 premium applies CMS default age factors (2.714 ÷ 1.278) to KFF’s national age-40 benchmark; state curves vary.
Required Portfolio by Lifestyle Level
The table below shows total portfolio targets for three common retirement lifestyles. Figures include a healthcare reserve for ages 55-64 and use a 3.5% withdrawal rate for the longer retirement horizon.
| Lifestyle | Annual Spending | Base Portfolio (3.5%) | Healthcare Reserve | Total Target |
|---|---|---|---|---|
| Modest | $50,000/yr | $1,428,571 | $500,000 | $1,928,571 |
| Comfortable | $80,000/yr | $2,285,714 | $575,000 | $2,860,714 |
| Affluent | $120,000/yr | $3,428,571 | $650,000 | $4,078,571 |
*Modest lifestyle assumes paid-off housing in a lower cost-of-living area. Comfortable includes travel and dining out. Affluent assumes maintaining a higher standard of living, potentially in a major metro. Healthcare reserve reflects 2026 unsubsidized ACA benchmark premiums (often $1,000-$1,400/month for ages 55-64 nationally) plus out-of-pocket costs, expressed as a 3.5% withdrawal-funded reserve.
What Each Lifestyle Looks Like in Practice
A modest $50,000/year budget might include a $1,800/month mortgage-free housing cost, $600/month for groceries and dining, $500/month for transportation, $400/month for healthcare (post-Medicare), and $700/month for everything else. This works well in cities like Pittsburgh, Indianapolis, or Raleigh — less so in San Francisco or New York.
A comfortable $80,000/year budget adds international travel ($8,000/year), a newer car replacement fund, higher dining and entertainment spending, and a buffer for home maintenance. This is the target most dual-income professionals aim for.
An affluent $120,000/year budget supports maintaining your pre-retirement lifestyle: premium healthcare, multiple trips per year, helping adult children, and living in a higher cost-of-living area without downsizing.
Case Study: Robert, 42, Software Engineer in Seattle
Current Situation
- Age: 42 (target retirement: 55)
- Salary: $165,000/year
- 401(k) balance: $198,000
- Roth IRA: $52,000
- Taxable brokerage: $45,000
- Total invested: $295,000
- Monthly savings: $3,500 ($2,042 401k + $625 Roth + $833 taxable)
- Mortgage: $2,800/month (12 years remaining)
Retirement Target
- Desired spending: $85,000/year (comfortable, mortgage-free)
- Portfolio needed (3.5% rule): $2,428,571
- Healthcare reserve (10 years): $575,000
- Total target: $3,003,571
- Years until 55: 13
- Assumed return: 7% average annual
Projection at Current Pace
- $295,000 growing at 7% for 13 years: $295,000 × 1.07^13 ≈ $710,904
- $3,500/month ($42,000/year) invested for 13 years at 7%: ≈ $845,907 in future value
- Projected portfolio at 55: ~$1,556,811
- Mortgage paid off by 54, freeing $2,800/month ($33,600/year)
Gap Analysis
Robert's projected $1,556,811 falls short of his $3,003,571 target by $1,446,760. At a 3.5% withdrawal, his projected portfolio would generate about $54,488/year — enough for a modest lifestyle but roughly $30,500 short of his $85,000 comfort target. The gap widened after the healthcare reserve moved to $575,000 following 2026 unsubsidized ACA premium increases (KFF Tier-2 estimates). Even accounting for the mortgage payoff reducing his spending need to roughly $51,400/year ($85,000 − $33,600), he would still need about $1,468,571 for spending alone — far less than the all-in target once healthcare is included.
Robert's Action Plan
- 1. Increase savings to $5,200/month — redirect the $2,800 mortgage payment after payoff plus boost contributions now. That narrows the shortfall by about $410,000 versus $3,500/month (to roughly $1.04 million below target at 7% returns).
- 2. Build a taxable bridge account — target $350,000 in taxable index funds by 55 to fund ages 55-59½ without touching 401(k) or IRA (avoiding the 10% early withdrawal penalty).
- 3. Start a Roth conversion ladder at 50 — convert $40,000/year from traditional IRA to Roth for 5 years, creating penalty-free access to converted principal after the 5-year seasoning period.
- 4. Consider a partial retirement at 55 — consulting 2 days/week at $200/hour ($1,600/week, ~$80,000/year) covers healthcare and reduces portfolio withdrawals to near zero for the first 5 years.
- 5. Evaluate relocating at 55 — moving from Seattle to a lower cost-of-living area like Boise or Phoenix could cut annual spending from $85,000 to $65,000, reducing the target portfolio by $571,428.
Healthcare: The Biggest Wildcard for Early Retirees
If you retire at 65, Medicare handles most of your healthcare costs. Retire at 55 and you enter the most expensive decade of private health insurance — premiums spike in your late 50s, and you have no employer subsidy to soften the blow.
| Age Range | Monthly Premium (Individual) | Annual Total (Premiums + Out-of-Pocket) |
|---|---|---|
| 55-59 | ~$1,090-$1,260 (unsubsidized benchmark Silver) | $13,000 - $18,000 |
| 60-64 | ~$1,300-$1,470 (unsubsidized benchmark Silver) | $16,000 - $22,000 |
| 60 (KFF benchmark, national) | ~$1,327 (benchmark Silver, age-adjusted) | ~$15,924 (premiums only) |
| 65+ (Medicare) | $202.90 Part B standard (2026) + Part D/Medigap varies | $4,500 - $8,000+ |
For a couple retiring at 55, double the individual estimates. A 57-year-old couple on a Silver-tier ACA plan in 2026 typically pays $2,400-$3,200/month ($28,800-$38,400/year) without subsidies — a significant jump from prior years after the enhanced premium tax credits expired after 2025 (KFF Tier-2: gross premiums up about 26% on average for 2026). For 2026 Marketplace coverage, premium tax credits generally apply up to 400% of the prior-year federal poverty level — about $62,600 for a single filer and $128,600 for a family of four (HealthCare.gov, based on 2025 poverty guidelines). Without enhanced credits, income above that cap receives no subsidy (a cliff, not a gradual phase-out).
Sources HealthCare.gov — federal poverty level (2025/2026 tables), KFF (Nov. 24, 2025) — subsidy cliff returns if enhanced credits expire, CMS fact sheet (Nov. 2025) — 2026 Part B premium $202.90. Checked October 2026.
Strategy: Manage Your MAGI
Early retirees often live off taxable brokerage accounts and Roth contributions (which do not count as income) to keep Modified Adjusted Gross Income below the 400% FPL cliff (about $62,600 single / $128,600 family of four for 2026 Marketplace coverage). Staying below this threshold can save $12,000-$20,000 per year in healthcare costs — which, capitalized at 3.5%, represents $343,000-$571,000 in portfolio value. HSA contributions (up to $5,400 for self-only HDHP coverage at age 55+ in 2026) also reduce MAGI, potentially pushing you back under the cliff.
Step-by-Step Plan to Retire at 55
Calculate your exact retirement number
Track every dollar you spend for 3 months. Multiply by 12, add 10-15% buffer, then divide by 0.035 (conservative withdrawal rate). Add about $500,000-$650,000 for healthcare. That is your target. A $75,000/year spender needs roughly $2.7-$2.9 million total.
Maximize tax-advantaged accounts
In 2026, contribute the maximum to your 401(k) ($24,500, or $32,500 with the age-50+ catch-up — and $35,750 if you are ages 60-63 under SECURE 2.0), Roth or traditional IRA ($7,500, or $8,600 with catch-up), and HSA if eligible ($4,400 individual / $8,750 family, plus $1,000 catch-up at 55+). Capture every dollar of employer match. For someone over 50 with family HSA coverage, these three accounts alone allow up to $50,850/year in tax-advantaged savings.
Sources IRS IR-2025-111, 2026 retirement plan limits (Nov. 13, 2025), IRS Rev. Proc. 2025-19 (2026 HSA limits). Checked October 20, 2026.
Build a taxable bridge account
You cannot access 401(k) or IRA funds without the 10% early withdrawal tax until 59½ (IRS exceptions include Rule of 55 after leaving your employer in or after the year you turn 55, and 72(t) SEPP). Fund a taxable brokerage with low-cost index funds — this is your spending money for ages 55-59½. Target 4-5 years of expenses: $80,000/year x 5 = $400,000 in taxable accounts.
Set up a Roth conversion ladder
Starting 5 years before retirement, convert $40,000-$50,000/year from traditional IRA/401(k) to Roth IRA. Pay taxes at your current (lower) rate. After 5 years, each conversion's principal becomes available for penalty-free withdrawal. This bridges the gap between your taxable account depletion and age 59½.
Plan your healthcare strategy
Research ACA plans in your state — note that 2026 premiums rose sharply after the enhanced premium tax credits expired. If retiring before 55, consider COBRA (18 months of employer coverage, typically $600-$700/month for individuals). Structure withdrawals to keep MAGI below about $62,600 (single) or $128,600 (family of four) — the 400% FPL subsidy cliff for 2026 Marketplace coverage. Budget about $1,100-$1,500/month for ages 55-64 depending on age and state (unsubsidized). An HSA-eligible HDHP can also reduce MAGI via deductible HSA contributions (up to $5,400 for self-only coverage at 55+ in 2026).
Sources IRS Retirement Topics — exceptions to tax on early distributions, IRS Rev. Proc. 2025-19 (2026 HSA limits). Checked October 20, 2026.
Run annual projections and adjust
Every year, recalculate your projected portfolio at 55 using actual returns and savings. If you are behind, increase savings or push the target date by 1-2 years. If ahead, consider reducing risk by shifting 5-10% from stocks to bonds. Use our Compound Interest Calculator to model different scenarios.
Sources IRS Retirement Topics — required minimum distributions (RMDs), IRS IRB 2024-33 (July 2024) — applicable RMD ages 73 vs 75 by birth year. Checked October 2026. Early retirees still face RMDs later; Roth IRAs have no lifetime RMDs for the original owner.
Calculate Your Retirement Number
Stop guessing. Plug in your current savings, monthly contributions, and target retirement age to see exactly where you stand and what it takes to retire at 55.
Frequently Asked Questions
How much money do I need to retire at 55?
Most people need a portfolio of roughly $1.9 million to $3.1 million to retire at 55, depending on annual spending and unsubsidized ACA costs. Using a historical 4% rule of thumb, $50,000/year implies $1.25 million, $80,000/year implies $2 million, and $120,000/year implies $3 million — but early retirees should add about $500,000-$650,000 for the 10-year healthcare gap before Medicare at 65. KFF (Tier-2) estimates gross ACA benchmark premiums rose about 26% on average for 2026, and enhanced premium tax credits expired after 2025, so unsubsidized Silver-plan costs for ages 55-64 often exceed $1,000/month nationally as of mid-October 2026.
Can I retire at 55 and still access my 401(k)?
Generally, IRA withdrawals before 59½ face a 10% additional tax unless an exception applies. For 401(k) plans, the IRS Rule of 55 lets you avoid that 10% tax on distributions from the plan you left if you separate from service in or after the calendar year you turn 55 (not available for IRAs). SEPP/72(t) substantially equal payments also avoid the penalty when rules are followed. Most early retirees still fund ages 55-59½ from taxable accounts and Roth conversion ladders.
Is the 4% rule safe for a 40-year retirement?
The classic 4% rule of thumb was designed for a 30-year retirement; many planners use 3.25-3.5% for 35-40 year horizons. Morningstar's 2026 withdrawal-rate research (Tier-2) suggests even a 30-year starting rate near 3.9% for diversified portfolios — below the original 4% headline. A $2 million portfolio at 3.5% yields $70,000/year — more conservative than $80,000 at 4%. Dynamic spending rules (for example Guyton-Klinger guardrails) can adjust withdrawals when markets fall, but they add complexity beyond a fixed percentage.
How much does health insurance cost if I retire before 65?
After enhanced ACA premium tax credits expired at the end of 2025, unsubsidized benchmark Silver premiums for 2026 coverage jumped sharply — KFF (Tier-2) estimates about a 26% average increase in what insurers charge. Nationally, the weighted average benchmark premium is about $625/month for a 40-year-old and roughly $1,327/month at age 60 before subsidies (KFF benchmark data plus the federal age curve). A couple in their late 50s often pays $2,000-$2,600/month unsubsidized. Budget roughly $180,000-$240,000 in premiums plus out-of-pocket costs over the 10-year gap until Medicare at 65 if you are not subsidy-eligible.
What is the fastest way to reach a $2 million retirement portfolio?
Maximize tax-advantaged accounts first: 401(k) ($24,500/year in 2026, or $32,500 with the age-50+ catch-up), IRA ($7,500/year, or $8,600 with catch-up), and HSA ($4,400 individual / $8,750 family, plus $1,000 catch-up at 55+). These three accounts alone allow up to $46,500/year for someone over 50 with self-only HDHP coverage. Then pour surplus into taxable index funds. Illustrative math only: at a 7% average return, saving $3,500/month from a $400,000 starting balance reaches $2 million in about 13 years. Use our Compound Interest Calculator to model your exact timeline.
Related Guides
401(k) vs Roth IRA: Which Retirement Account Is Better for You?
Compare 401(k) vs Roth IRA: contribution limits, tax treatment, income limits, and when each wins. Includes a case study and the optimal hybrid strategy.
Compound Interest: 5 Real-Life Examples That Show Its Power
See compound interest in action with 5 real examples: $500/month for 40 years, credit card debt traps, student loans, and the Rule of 72 explained.