How Student Loan Interest Works
Student loan interest accrues on your outstanding principal balance each day, but most borrowers experience it as a monthly charge on their statement. For fixed-rate loans, your interest rate stays the same for the life of the loan. The lender converts your annual rate into a daily rate by dividing by 365, then multiplies that rate by your current balance each day. At the end of the billing cycle, those daily charges are summed and added to your account.
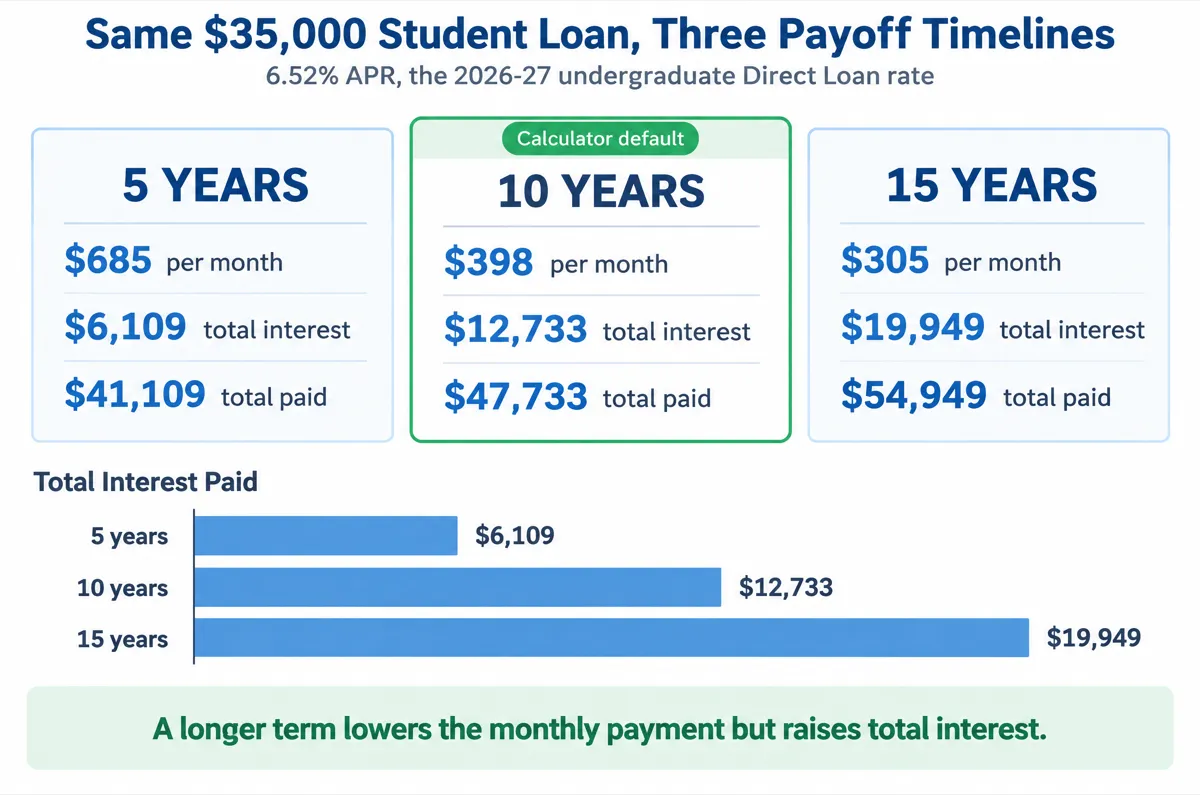
Unlike credit cards, student loans use simple interest on a declining balance through amortization. Each monthly payment is split between interest and principal. Early payments are heavily weighted toward interest — on a $35,000 loan at 6.52% over 10 years, your first payment of about $398 includes roughly $190 in interest and $208 toward principal. As the balance drops, the interest portion shrinks and more of each payment attacks the principal directly.
This structure means the total interest you pay depends on three variables: your starting balance, your interest rate, and how long you take to repay. Extending your term lowers monthly payments but dramatically increases total interest. Understanding this tradeoff is the foundation of every smart repayment decision. Use our calculator above to see exactly how your balance, rate, and term interact for your specific situation.
2026–27 Federal Direct Loan Rates
For loans first disbursed July 1, 2026 through June 30, 2027, the U.S. Department of Education set fixed rates at 6.52% for undergraduate Direct Subsidized and Unsubsidized Loans, 8.07% for graduate Direct Unsubsidized Loans, and 9.07% for Direct PLUS Loans (based on the May 12, 2026 10-year Treasury auction plus statutory add-ons). Each loan keeps its rate for life. The calculator defaults to the undergraduate rate; enter your servicer's weighted average if you hold multiple disbursement years.
Sources FSA Partner Announcement GENERAL-26-33 (June 4, 2026) — 2026–27 Direct Loan rates, Federal Register annual rate notice (Sept. 10, 2026). Checked October 2026.
Federal vs Private Student Loans
Federal student loans are issued by the U.S. Department of Education and come with borrower protections that private loans rarely match. They include fixed interest rates set by formula each award year, income-driven and Repayment Assistance Plan (RAP) options, Public Service Loan Forgiveness (PSLF), deferment and forbearance options, and no credit check for most undergraduate borrowers. Direct Subsidized Loans do not accrue interest while you are enrolled at least half-time, which can save thousands compared to unsubsidized loans that capitalize interest at graduation.
Private student loans are issued by banks, credit unions, and online lenders. Rates are typically variable or fixed based on your credit score and cosigner strength. A borrower with excellent credit might qualify for rates near 4-6%, while those with thin credit files could face rates of 10% or higher. Private loans generally lack income-driven repayment, loan forgiveness programs, and flexible deferment. If you have both federal and private loans, prioritize understanding the terms of each before choosing a repayment strategy.
A common mistake is refinancing federal loans into a private loan to get a lower rate without weighing the lost protections. If you work in public service, expect income fluctuations, or might need deferment, keeping federal loans in the federal system is often the better choice even at a slightly higher rate.
Repayment Plan Options
Federal borrowers can choose from several repayment plans, each designed for different financial situations. The Standard Repayment Plan spreads payments evenly over 10 years — the fastest option for paying the least total interest. The Graduated Repayment Plan starts with lower payments that increase every two years, useful for borrowers who expect rising income but want to stay on a 10-year track.
Extended Repayment stretches payments over 25 years, cutting monthly bills but adding substantial interest. Income-driven repayment (IDR) plans — including the new Repayment Assistance Plan (RAP) available from July 1, 2026, plus PAYE, IBR, and ICR where you still qualify — tie payments to income and family size. The Saving on a Valuable Education (SAVE) Plan ended in March 2026 after a court order; borrowers formerly on SAVE must choose another plan. RAP uses 1–10% of adjusted gross income (with a $10 monthly floor and interest subsidies while payments stay current) and can run up to 30 years. New loans disbursed on or after July 1, 2026 generally must use RAP or the Tiered Standard plan.
Sources Federal Student Aid — SAVE Plan ended; choose a new plan, U.S. Department of Education — RAP and Tiered Standard (July 1, 2026). Checked October 2026.
Private loan borrowers have fewer options. Most lenders offer standard fixed repayment over 5 to 15 years. Some allow interest-only payments during school or a short grace period. If you need flexibility, contact your servicer directly — many offer temporary hardship programs even though they are not required by law.
Case Study: Sarah, a 25-Year-Old Software Engineer
Sarah graduated with $42,000 in federal Direct Loans at a weighted average rate of 6.52% (2026–27 undergraduate disbursements). Her first job pays $78,000 per year, and after taxes and rent she has about $900 per month available for loan payments. On the Standard 10-year plan, her monthly payment is about $477, leaving room for savings and discretionary spending.
Sarah considered switching to a 25-year Tiered Standard schedule to free up cash flow. That would drop her payment to roughly $284, but total interest would jump from about $15,300 to over $43,200 — an extra $28,000 in cost for modest monthly relief. She stayed on the 10-year standard plan and added $100 per month toward principal.
With the extra $100, Sarah pays off her loans in about seven years and nine months instead of 10 years, saving approximately $3,700 in interest. She also redirects the freed-up $577 monthly payment toward her compound interest investment account once the loans are gone. By age 33, she is debt-free and has built a portfolio that would not have been possible if she had stretched her loans over 25 years.
Comparison: Standard vs Extended vs Income-Driven
The table below compares three common approaches for a $35,000 loan at6.52% interest. RAP payments vary with AGI and dependents; illustrative low-income payments often fall below standard.
| Plan | Monthly Payment | Payoff Timeline | Total Interest |
|---|---|---|---|
| Standard (10-year) | $398 | 10 years | $12,733 |
| Tiered Standard (25-year) | $237 | 25 years | $36,028 |
| RAP (income-based) | Varies by AGI | Up to 30 years | Lower near-term; may qualify for PSLF |
The Standard plan costs the least in total interest. Extended repayment nearly triples interest cost for a 43% lower monthly payment. IDR plans trade higher long-term cost (or forgiven balance) for payment flexibility when income is limited. Run your own numbers with our calculator to see where extra payments shift the balance.
Tips for Faster Payoff
Paying off student loans faster starts with a clear target. List every loan, its balance, rate, and servicer. If you have multiple loans, use the avalanche method (highest rate first) to minimize total interest, or the snowball method (smallest balance first) if quick wins keep you motivated. Our Debt Payoff Calculator can model both strategies across multiple debts.
Make extra payments toward principal, not future bills. Contact your servicer to confirm extra amounts apply to principal immediately rather than advancing your due date. Even $50 per month on a $35,000 loan at 6.52% saves about $2,000 in interest and cuts roughly 17 months off a 10-year term. Apply windfalls — tax refunds, bonuses, side income — directly to your highest-rate loan.
Avoid diverting loan payment money toward lower-priority spending. If your loans are your highest-rate debt, they deserve priority over discretionary purchases. If you also carry credit card debt at 20%+ APR, tackle that first using our Credit Card Payoff Calculator, then redirect those payments to student loans. Once loans are gone, redirect the full payment amount to investing — see compound interest in real examples for how early investing compounds over decades.
Consider whether refinancing makes sense only after evaluating federal protections. Autopay discounts of 0.25% are offered by most servicers and private lenders — a small but effortless saving. Set calendar reminders to recheck your strategy annually as income and rates change.
Frequently Asked Questions
Should I pay off student loans or invest?
Compare your loan interest rate to expected investment returns after taxes. If your loans are at 5-7% and you can earn 8-10% long-term in a diversified portfolio, investing while making minimum payments may build more wealth. If your loans are above 7% or you value the guaranteed return of being debt-free, prioritize payoff. Many borrowers split the difference: minimum payments plus retirement match, then extra toward loans.
What happens if I miss a student loan payment?
Federal loans enter delinquency after one missed payment and default after 270 days. Consequences include damaged credit, wage garnishment, and loss of eligibility for deferment and forgiveness. Private lenders may report delinquency after 30 days and pursue collections sooner. Contact your servicer immediately if you anticipate difficulty — IDR plans and temporary forbearance exist specifically for this situation.
Can I deduct student loan interest on my taxes?
You may deduct up to $2,500 in qualified student loan interest per year (2026 limit unchanged). The deduction phases out for single filers with modified adjusted gross income between $85,000 and $100,000, and for joint filers between $175,000 and $205,000 (IRS Rev. Proc. 2025-32). It is above-the-line — no itemizing required — and reduces taxable income, not tax dollar-for-dollar. A full $2,500 deduction saves roughly $275–$925 depending on your marginal bracket.
Sources IRS Topic 456 — Student loan interest deduction, IRS Rev. Proc. 2025-32 (2026 inflation adjustments). Checked October 2026.
Is Public Service Loan Forgiveness worth pursuing?
PSLF forgives remaining federal Direct Loan balances after 120 qualifying payments while working full-time for a qualifying employer (government, nonprofits, etc.). If you work in public service and have high loan balances relative to income, PSLF can save tens of thousands. Enroll in an IDR plan, certify employment annually, and keep meticulous records. For high earners in the private sector, aggressive payoff often outperforms PSLF timelines.
Does paying extra on student loans hurt my credit score?
No. Paying extra reduces your balance and improves your debt-to-income ratio, both positive for credit health. Closing student loan accounts may cause a small temporary dip because you lose an active installment account, but the long-term benefit of lower debt outweighs this effect. Keep other credit accounts open and in good standing to maintain a strong score after payoff.