Guides / Debt Strategy
How to Pay Off $10,000 in Credit Card Debt: 5 Proven Strategies
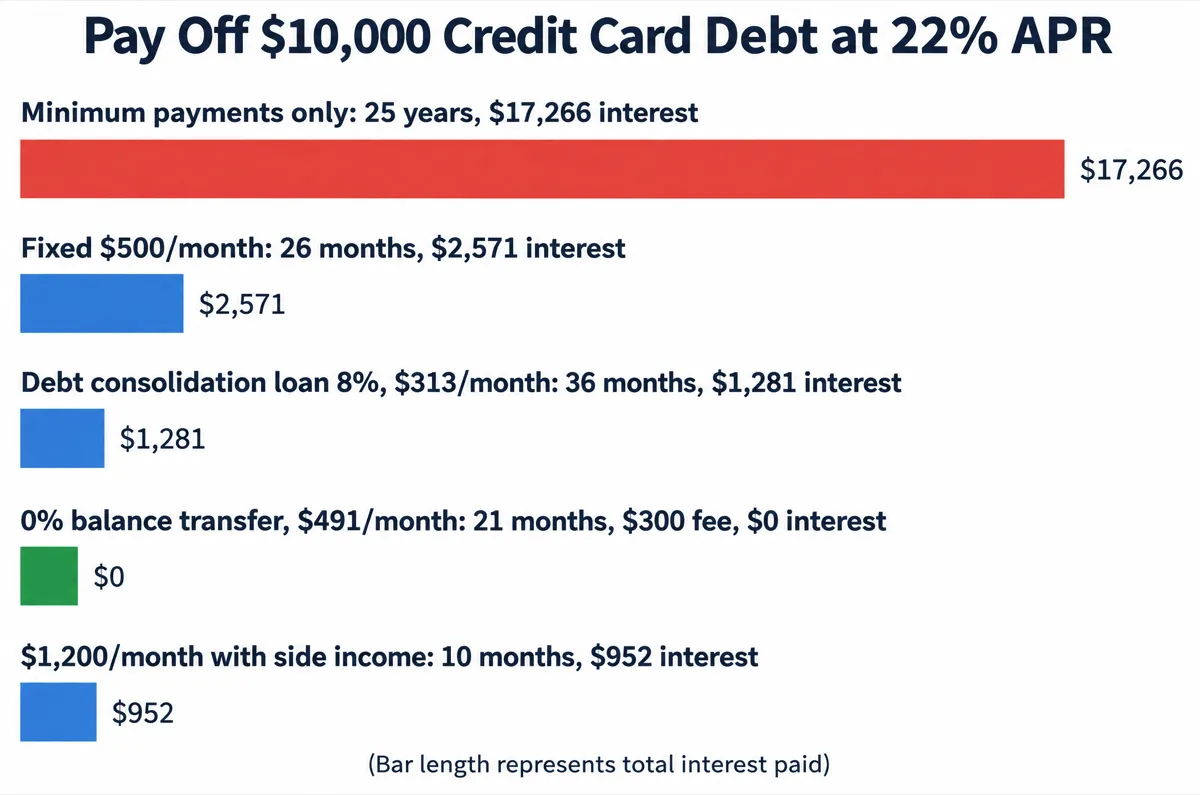
$10,000 in credit card debt at 22% APR is not a life sentence — but paying only the minimum turns it into one. Left untouched, that balance takes about 25 years to eliminate and costs $17,266 in interest alone. This guide runs five specific strategies with real numbers so you can pick the fastest path to zero for your budget and personality.
Last updated: October 2026
TL;DR - Quick Answer
- Minimum payments are a trap: $10,000 at 22% APR with minimum payments (about $283 in month one) takes about 25 years and costs $17,266 in interest
- Fastest low-cost option: 0% balance transfer at $491/month for 21 months — total cost $10,300 ($300 transfer fee, $0 interest)
- Best no-transfer option: Fixed $500/month payment — debt-free in 26 months, $2,571 in interest
- Fastest overall: Paying $1,200/month ($200 budget plus $1,000 side income) — paid off in 10 months, $952 in interest
Use our Debt Payoff Calculator and Credit Card Payoff Calculator to model your exact balances and target date.
The True Cost of Paying Only the Minimum
A common minimum-payment formula is 1% of your balance plus that month's interest (with a floor of about $25), and this guide uses it for every “minimum only” figure. On a $10,000 balance at 22% APR, your minimum payment starts at $283.33/month — and nearly two-thirds of it goes to interest, not principal.
Here is how the math works against you:
Of the $283.33 minimum in month one, only $100 (1% of the balance) goes toward the principal. As the balance slowly drops, the minimum shrinks too — stretching payoff over decades. At this pace:
- Time to payoff: about 25 years (299 months)
- Total interest paid: $17,266
- Total amount repaid: $27,266 on a $10,000 purchase
That $17,266 in interest is money that never bought you anything — no groceries, no rent, no vacation. It is pure cost for borrowing $10,000. Every strategy below exists to escape this trap as quickly as your budget allows.
Key Insight
The gap between minimum payments and a fixed $500/month plan is staggering: 25 years and $17,266 in interest versus 26 months and $2,571. That is $14,695 saved simply by committing to a consistent, higher payment — no balance transfer or loan required.
5 Proven Strategies to Pay Off $10,000 Fast
All five scenarios start with the same $10,000 balance at 22% APR unless noted. Strategy 4 uses a three-card portfolio totaling $10,000. Compare each option against your monthly budget and how quickly you need to be debt-free.
Strategy 1: Aggressive Fixed Payment ($500/Month)
The simplest approach: pick a fixed monthly payment and never go below it, regardless of what the minimum drops to. On $10,000 at 22% APR, paying exactly $500 every month eliminates the balance in 26 months (the last payment is only about $73) with $2,571 in total interest.
- Monthly payment: $500 (fixed, never lower)
- Months to payoff: 26
- Total interest: $2,571
- Total cost: $12,571
Month 1 breaks down as $183.33 in interest and $316.67 toward principal. By month 12, the balance sits at approximately $5,792 and monthly interest has dropped to about $106 — meaning more of each $500 payment attacks principal. This strategy requires no new accounts, no credit checks, and no transfer fees. If you can spare $500/month, start here.
Strategy 2: Balance Transfer to a 0% APR Card
A 0% introductory APR balance transfer card pauses interest charges for 12-21 months, letting every dollar go toward principal. Transfer the full $10,000 to a card offering 0% for 21 months, pay a 3% transfer fee ($300) that is added to the balance ($10,300), and commit to $491/month ($10,300 ÷ 21).
- Monthly payment: $491 (final payment $485)
- Months to payoff: 21
- Total interest: $0
- Transfer fee (3%): $300
- Total cost: $10,300
This is the lowest total-cost strategy on the list — $2,271 less than the aggressive fixed payment approach. The critical rule: pay off the entire balance before the 0% period expires. Any remaining balance after month 21 typically jumps to 20-25% APR retroactively on some cards. Set a calendar reminder for month 18 and confirm you are on track. You will need a credit score of roughly 670+ to qualify for the best 0% offers in 2026.
Strategy 3: Debt Consolidation Loan at 8%
A personal loan replaces high-rate credit card debt with a fixed-rate installment loan. On $10,000 borrowed at 8% over 36 months, your payment is $313/month — lower than the balance transfer — and you know exactly when you will be debt-free.
- Monthly payment: $313
- Months to payoff: 36
- Total interest: $1,281
- Total cost: $11,281
Consolidation trades speed for affordability. You pay $1,281 in interest versus $2,571 with the $500/month fixed approach, but the timeline stretches to three years. This works well if $500/month strains your budget or you want a single automatic payment instead of juggling multiple card due dates. Cut up the old cards after consolidating — freshly zeroed cards with thousands in available credit are the fastest way to end up owing both the loan and a new card balance.
Strategy 4: Debt Snowball (Smallest Card First)
If your $10,000 is spread across multiple cards, the debt snowball method targets the smallest balance first for quick psychological wins. Here is a realistic three-card portfolio (weighted average APR about 23.7%) with $500/month total available. Minimums use the same 1%-plus-interest formula described above:
| Card | Balance | APR | Min Payment |
|---|---|---|---|
| Store card | $1,800 | 19.99% | $48 |
| Visa | $2,200 | 22.99% | $64 |
| Mastercard | $6,000 | 24.99% | $185 |
| Total | $10,000 | — | $297 |
Pay $297 in minimums across all three cards, then send the remaining $203 to the $1,800 store card. When the store card clears in month 8, roll its full $251 payment ($48 minimum + $203 extra) to the Visa. When Visa clears in month 15, roll everything to the Mastercard.
- Monthly payment: $500 total ($297 minimums + $203 extra)
- Months to payoff: 26
- Total interest: $2,953
- Total cost: $12,953
Snowball costs $197 more in interest than targeting the highest-rate card first (avalanche: $2,756 total interest, Mastercard cleared in month 19), but you eliminate the store card in month 8 and the Visa in month 15 — two visible wins before the final push. If you have abandoned debt plans before, those early zero-balance moments can be the difference between finishing and quitting.
Strategy 5: Side Income Blast (+$1,000/Month Extra)
Temporarily increasing income is the fastest way out. On $10,000 at 22% APR, paying $200 from your regular budget plus $1,000 in side income each month ($1,200 total, held constant) clears the balance in 10 months with $952 in interest.
- Monthly payment: $1,200 ($200 budget + $1,000 side income)
- Months to payoff: 10
- Total interest: $952
- Total cost: $10,952
Realistic side income sources for $1,000/month: freelance writing or design ($40-60/hour, 20 hours/month), rideshare or delivery driving ($800-$1,200/month part-time), tutoring ($30-50/hour), or selling unused items plus ongoing resale (eBay, Facebook Marketplace). The side income blast is not permanent — it is a 10-month sprint. Once the balance hits $0, redirect that $1,000 toward building an emergency fund so you never carry a credit card balance again.
Strategy Comparison: All 5 Options Side by Side
Use this table to match a strategy to your monthly budget and target timeline. The baseline minimum-payment row shows what happens if you do nothing differently.
| Strategy | Monthly Payment | Months to Payoff | Total Interest | Total Cost |
|---|---|---|---|---|
| Minimum payments only | $283 (declining) | 299 (25 years) | $17,266 | $27,266 |
| Aggressive fixed payment | $500 | 26 | $2,571 | $12,571 |
| Balance transfer (0% APR) | $491 | 21 | $0* | $10,300 |
| Debt consolidation (8%) | $313 | 36 | $1,281 | $11,281 |
| Debt snowball (3 cards)*** | $500 | 26 | $2,953 | $12,953 |
| Nonprofit DMP (~8% APR)** | $535 | 22 | $769 + $770 fees | $11,539 |
| Side income blast | $1,200 | 10 | $952 | $10,952 |
*Balance transfer total cost includes $300 transfer fee (3% of $10,000), added to the balance and repaid at $491/month. All calculations assume $10,000 starting balance at 22% APR unless noted, monthly compounding, and minimums of 1% of the balance plus interest. ***The three-card snowball uses the portfolio in Strategy 4 (weighted APR about 23.7%). Figures are rounded — use our calculators for your exact debts.
**DMP assumes a negotiated 8% APR (NFCC says DMP rates are typically 10% or less), $500 toward principal plus a $35 monthly agency fee, and excludes the one-time setup fee (up to $75 at most agencies). Many real plans run 36-60 months because they use lower monthly payments.
What to Expect in Late 2026: Rates, Fees, and Offers
The strategies above only work if the rates you can actually get resemble the assumptions. The Federal Reserve's G.19 Consumer Credit release (published October 7, 2026) reports an average credit card APR of 21.19% across all accounts and 22.36% on accounts that are charged interest, as of August 2026 — which is why this guide models $10,000 at 22%. Here is how the other levers compare before you apply for anything:
| Item | Typical Range | Impact on $10,000 |
|---|---|---|
| Average card APR (Fed, Aug 2026) | 21.19% all accounts; 22.36% accounts paying interest | $177-$186 interest in month one |
| 0% transfer promo length | Up to 21 months on dedicated transfer cards; 12-15 months on most rewards cards | $491/month clears $10,300 (balance plus 3% fee) in 21 months; a 15-month promo needs $687 |
| Balance transfer fee | 3% if transferred in the first 60 days to 4 months, then 5% (min $5) | $300 early vs $500 late added to balance |
| Personal loan APR | 11.90% bank average on 24-month loans (Fed); 6.99%+ for top-tier credit at some lenders | $1,281 (8%) to about $1,940 (11.9%) interest over 36 months |
| Personal loan origination fee | 1%-10% typical; $0 at some lenders | $100-$1,000 deducted from proceeds |
| Nonprofit DMP (NFCC agencies) | Rates typically 10% or less; setup up to $75; $25-$50 per month; 36-60 month plans | $1,500-$3,000 in fees over a 60-month plan at $25-$50/month |
Two details change the winner. First, a 5% transfer fee turns the $300 cost in Strategy 2 into $500, which raises the total to $10,500 — still $2,071 cheaper than the fixed $500 payment at 22%, but only $781 cheaper than an 8% consolidation loan. If you only qualify for the 11.9% bank average, that loan costs about $1,940 in interest, so even the 5%-fee transfer beats it by roughly $1,440. Second, a 12-month promo requires $875/month on a $10,500 post-fee balance, so shorter promos only beat a loan if you can truly afford that payment. Note that a 3% fee requires moving fast: the Citi Simplicity and Chase Slate offers, for example, charge 3% only on transfers made within the first 4 months, then 5%. When you cannot, compare both options side by side in the Loan Comparison Calculator.
A cheaper first step costs nothing: call each issuer and ask for a hardship or rate-reduction review. Results vary by issuer and payment history, but even a 4-point cut is worth the call: dropping $10,000 from 22% to 18% saves about $33/month in interest immediately — $396 in the first year without opening a single new account. Once your balances are under control, protect against relapse with the account tiers in our emergency fund guide, and pick your payoff order with the avalanche vs snowball comparison.
Sources Federal Reserve Board, G.19 Consumer Credit (October 7, 2026), National Foundation for Credit Counseling, debt repayment methods, myFICO on credit inquiries. Checked October 2026. Issuer terms as listed by Bankrate and NerdWallet in October 2026. Offers change frequently — confirm current terms with the issuer.
Case Study: Rachel, 29, $52K Salary in Denver
Her Situation
- Gross salary: $52,000/year ($3,250/month take-home)
- Total credit card debt: $10,200 across 3 cards
- Minimum payments: $300/month combined
- Available for debt payoff: $510/month total
- Rent: $1,350/month (studio apartment)
- Credit score: 712 (good — qualifies for 0% transfer)
Her 3 Cards
- Target RedCard: $1,400 at 26.99% ($46 min)
- Chase Freedom: $2,800 at 23.99% ($84 min)
- Capital One Quicksilver: $6,000 at 21.99% ($170 min)
Rachel's Analysis
Rachel ran all five strategies through the Credit Card Payoff Calculator. Minimum payments would cost her $16,386 in interest over about 21 years. The $510/month fixed plan (highest-rate card first) cleared debt in 26 months at $2,722 in interest. The balance transfer at $501/month ($10,200 + $306 transfer fee, spread over 21 months) cost $306 total — saving $2,416 versus the fixed payment approach.
She considered snowball for the motivational wins, but although the $1,400 Target card would clear in month 6, the last card would not reach zero until month 26 — five months after the transfer plan finishes. Consolidation at 8% over 36 months ($320/month, $1,307 in interest) was affordable but added 15 extra months of payments compared to the transfer.
Rachel's Chosen Strategy: 0% Balance Transfer
Rachel applied for a Citi Simplicity card offering 0% APR for 21 months on balance transfers. She transferred all $10,200, paid the $306 fee (3%), and set up automatic payments of $501/month. She cut up all three original cards and removed them from her Apple Wallet to prevent new charges.
| Month | Payment | Remaining Balance | Interest Paid |
|---|---|---|---|
| Start | — | $10,506 | $0 |
| 1 | $501 | $10,005 | $0 |
| 6 | $501 | $7,500 | $0 |
| 12 | $501 | $4,494 | $0 |
| 18 | $501 | $1,488 | $0 |
| 21 | $486 (final) | $0 | $0 |
Rachel will be debt-free in May 2028 — 21 months from her August 2026 start date. Total cost: $10,506 ($10,200 principal + $306 transfer fee). Starting in month 22, she redirects the $501/month toward a $5,000 emergency fund, reaching that goal in 10 more months.
Your Step-by-Step Plan to Pay Off $10,000
Follow these seven steps in order. Skipping step 1 or step 2 is how most payoff plans fail within the first 90 days.
List every card with balance, APR, and minimum payment
Log into each account and write down the exact numbers. Include store cards, gas cards, and any card you have not used in months. Rachel's list totaled $10,200 across three cards with $300/month in minimums.
Stop adding new charges immediately
Remove cards from your wallet and online checkout profiles. Paying $500/month toward debt while charging $300/month in new purchases is running on a treadmill. Use a debit card or cash until every balance reads $0.00.
Build a $1,000 starter emergency fund
Save $1,000 before attacking debt aggressively. Without any buffer, one $800 car repair goes right back on a credit card at 22%. This takes 2-3 months if you save $350-$500/month, then redirect the full amount to debt.
Choose your strategy from the comparison table
Match your monthly budget to a strategy. Under $490/month: consolidation loan ($313/month) or a nonprofit DMP. $490-$900/month: balance transfer ($491/month) or fixed payment. $1,000+/month available: side income blast. Multiple small cards and a history of quitting: snowball.
Set up automatic payments on payday
Schedule your debt payment to transfer on the same day your paycheck arrives. Rachel set $501 to auto-pay her Citi card on the 1st and 15th ($250 and $251). Automating removes willpower from the equation — the money leaves before you can spend it.
Track progress monthly and adjust if needed
Check your balance on the first of each month. If you receive a tax refund, bonus, or windfall, apply it directly to principal — do not treat it as spending money. A $1,200 tax refund applied in month 3 shaves two months off a 21-month balance transfer plan.
Redirect payments to savings once debt-free
When the final balance hits $0, immediately redirect your former debt payment to an emergency fund (target 3-6 months of expenses) and then toward retirement or other goals. You were living without that $491-$1,200/month — keep the habit, change the destination.
4 Mistakes That Keep You in Credit Card Debt
Missing the balance transfer deadline
A 0% transfer only works if you pay off the balance before the promotional period ends. On $10,000 remaining after month 21 at 24.99% APR, you suddenly owe $2,499/year in interest. Set calendar alerts at months 12, 18, and 20. If you are behind at month 18, increase payments or explore a second transfer.
Consolidating without closing old cards
Moving $10,000 to an 8% personal loan while keeping three credit cards open invites relapse. Those cards still have $20,000+ in combined available credit sitting there. Close them or lock them away after consolidating. One new charge at 22% undoes months of progress.
Treating side income as bonus spending money
Earning an extra $1,000/month from freelancing only works if every dollar goes to the credit card. Deposit side income directly to the card the same day it arrives. If it hits your checking account, it will get absorbed by lifestyle creep within two months.
Paying debt before building any emergency buffer
Sending 100% of savings to debt with $0 in the bank means one unexpected expense sends you right back to square one. The 2-3 months spent saving $1,000 first costs roughly $40 in extra interest — far less than a $800 relapse that adds another year to your payoff timeline.
Payoff Plan by Balance Size
Your optimal strategy depends heavily on how much you owe. A $2,000 balance calls for a different playbook than $15,000. Here is a breakdown by common balance levels, with payoff timelines at 22.9% APR unless noted.
$2,000 Balance
A $2,000 balance is the most common entry point for first-time credit card debtors — usually the result of a single unexpected expense like a car repair, medical bill, or emergency travel. At 22.9% APR, paying $100/month clears the balance in 26 months with roughly $543 in interest. That is manageable on most budgets without restructuring your entire financial life.
This balance is small enough to brute-force with disciplined fixed payments. Consolidation loans and transfer fees often cost more than they save at this level. A 0% balance transfer with a 3% fee ($60) and a $172 monthly payment ($2,060 ÷ 12) clears in 12 months for $60 total, versus 14 months and about $284 in interest if you paid the same $172 on the card — a saving of about $224, but only if you actually follow through. For most people at $2,000, simply paying $100-$150/month and avoiding new charges is the fastest path to zero.
| Monthly Payment | Months to Payoff | Total Interest | Total Cost |
|---|---|---|---|
| ~$58 (minimum, declining) | 141 (11.8 years) | ~$2,729 | ~$4,729 |
| $100 | 26 | ~$543 | ~$2,543 |
| $150 | 16 | ~$330 | ~$2,330 |
| $200 | 12 | ~$241 | ~$2,241 |
$5,000 Balance
At $5,000, credit card interest becomes genuinely expensive. Paying only the minimum (~$145/month at first on a $5,000 balance at 22.9% APR) stretches payoff across 19 years and costs roughly $8,450 in interest — more than the original purchase. This is the turning point where minimum payments stop being a nuisance and start being a financial emergency.
If your $5,000 is split across multiple cards, the avalanche method (highest APR first) is the most effective approach. Direct every extra dollar to the card charging the highest rate while paying minimums on the rest. At $300-$500/month total, most people clear a $5,000 portfolio in 12-21 months depending on how aggressively they pay.
| Monthly Payment | Months to Payoff | Total Interest | Total Cost |
|---|---|---|---|
| ~$145 (minimum, declining) | 232 (19.3 years) | ~$8,454 | ~$13,454 |
| $200 | 35 | ~$1,860 | ~$6,860 |
| $300 | 21 | ~$1,076 | ~$6,076 |
| $500 | 12 | ~$602 | ~$5,602 |
$10,000 Balance
A $10,000 credit card balance puts real pressure on monthly cash flow. Minimum payments starting at roughly $291/month at 22.9% APR take about 25 years to eliminate and cost approximately $18,000 in interest. At this level, the strategies in this guide — balance transfers, consolidation loans, and aggressive fixed payments — all become worth serious consideration. Note that this table uses 22.9% APR, so interest figures differ slightly from the 22% scenarios earlier in the guide — a 0.9-point gap adds roughly $90 a year on $10,000.
A personal loan at 10% APR over 24 months on $10,000 costs roughly $1,075 in interest ($11,075 total). The same balance on a credit card at 19.9% APR paid off at $500/month takes 25 months and costs about $2,251 in interest — a difference of $1,176 (the loan's payment is $461/month versus $500). Consolidation makes the most sense when you need a lower fixed payment and cannot qualify for a 0% balance transfer.
| Monthly Payment | Months to Payoff | Total Interest | Total Cost |
|---|---|---|---|
| ~$291 (minimum, declining) | 301 (25 years) | ~$17,995 | ~$27,995 |
| $300 | 54 | ~$6,044 | ~$16,044 |
| $500 | 26 | ~$2,716 | ~$12,716 |
| $800 | 15 | ~$1,535 | ~$11,535 |
$15,000 Balance
$15,000 in credit card debt creates significant financial pressure. Minimum payments starting at roughly $436/month at 22.9% APR stretch payoff across 28 years and cost approximately $27,500 in interest — you repay about $42,500 on $15,000 borrowed. At this level, a structured plan is not optional. Hoping the balance shrinks on its own is how people end up carrying debt into retirement.
Start by calling your card issuers and requesting an APR reduction; a history of on-time payments strengthens your case, and each point removed saves about $12.50/month on $15,000. If you qualify, a 0% balance transfer on a portion of the balance can save thousands — but only if you are disciplined enough to pay off the transferred amount before the promotional period ends. Combine a transfer with a fixed payment plan of $600-$900/month to clear the full balance in under three years.
| Monthly Payment | Months to Payoff | Total Interest | Total Cost |
|---|---|---|---|
| ~$436 (minimum, declining) | 341 (28.4 years) | ~$27,537 | ~$42,537 |
| $400 | 67 | ~$11,609 | ~$26,609 |
| $600 | 35 | ~$5,579 | ~$20,579 |
| $900 | 21 | ~$3,227 | ~$18,227 |
Calculate Your Credit Card Payoff Plan
Every debt situation is different. Enter your exact balances, APRs, and monthly budget to see how long each strategy takes and how much interest you will pay — or save.
Frequently Asked Questions
How long does it take to pay off $10,000 in credit card debt?
It depends entirely on your monthly payment. Paying only the minimum (about $283 in month one on a $10,000 balance at 22% APR, shrinking as the balance falls) takes about 25 years and costs $17,266 in interest. A fixed $500/month payment clears the debt in 26 months with $2,571 in interest. Paying $1,200/month (for example, $200 of regular budget plus $1,000 of side income) pays it off in 10 months for $952 in interest. A 0% balance transfer card at $491/month eliminates it in 21 months with zero interest (you pay a $300 transfer fee, which is added to the balance).
Is a balance transfer or debt consolidation loan better for $10,000?
A 0% APR balance transfer wins on total cost if you can pay off the balance before the promotional period ends. On $10,000, a 21-month 0% transfer at about $491/month ($10,300 including the 3% fee) costs $300 in transfer fees and $0 in interest — total cost $10,300. An 8% consolidation loan over 36 months at $313/month costs $1,281 in interest — total cost $11,281. Choose balance transfer if you can commit to the higher monthly payment; choose consolidation if you need a lower, fixed payment over a longer term.
Should I use the debt snowball or avalanche method for credit cards?
For credit card debt, avalanche (highest rate first) saves the most money. On three cards totaling $10,000 (a $1,800 card at 19.99%, a $2,200 card at 22.99%, and a $6,000 card at 24.99%) with $500/month available, avalanche costs approximately $2,756 in interest and finishes in 26 months. Snowball (smallest balance first) costs about $2,953 in interest over the same 26 months — $197 more, but it clears the first card in month 8 instead of month 19. If you have quit debt plans before, snowball's psychological momentum may be worth the extra cost. See our full comparison in the debt avalanche vs snowball guide.
How much should I pay monthly to pay off $10,000 fast?
Aim for at least 5% of the balance per month ($500 on $10,000) to make meaningful progress. At 22% APR, $500/month pays off the debt in 26 months with $2,571 in interest. To finish in 12 months, you need about $936/month at 22% APR (total interest about $1,230), and about $1,200/month to finish in 10 months. Use our Credit Card Payoff Calculator to find the exact payment for your target date and interest rate.
Will a balance transfer or paying off cards hurt my credit score?
A balance transfer application triggers a hard inquiry; according to myFICO, one additional inquiry takes fewer than five points off most people's FICO Scores, and FICO only counts inquiries from the past 12 months. A new card also lowers your average account age slightly. Against that, amounts owed make up 30% of a FICO Score, and utilization is a key part of it. Moving $10,000 from three cards with $12,000 in combined limits (83% utilization) to a new card with a $12,000 limit and paying the $10,300 balance (including the fee) down to $4,408 by month 12 at $491/month cuts utilization on that card from 86% to 37%, which helps your score over time. Do not close the oldest paid-off card if it has no annual fee, since its age keeps helping your score.
What if I cannot afford $500/month — is a debt management plan worth it?
A nonprofit debt management plan (DMP) through an NFCC-affiliated agency is worth considering when your budget tops out at $300-$490/month and you do not qualify for a 0% transfer or an 8-10% loan. According to the National Foundation for Credit Counseling, creditors typically lower DMP interest rates to 10% or less, agencies charge a setup fee of up to $75 and a monthly fee of $25-$50, and plans usually run 36-60 months. As an illustration, $10,000 at 8% with a $535 monthly payment (including a $35 fee) finishes in about 22 months for roughly $770 in interest plus $770 in fees — about $11,540 total, versus $12,571 at 22% APR with a $500 fixed payment. At a lower payment of $300/month the same plan runs about 38 months. The tradeoff: enrolled cards are usually closed, and your score can dip temporarily.
Can I pay off credit card debt while saving for other goals?
Build a starter emergency fund of $1,000-$2,000 first, then redirect every extra dollar to credit card debt. Credit cards at 18-25% APR guarantee a return no savings account can match. Once credit card debt is eliminated, redirect your former payment ($500-$1,200/month) toward savings goals like a house down payment or retirement. On a $52,000 salary, becoming debt-free in 21 months frees up $491/month that previously went to credit card payments.
Related Guides
Debt Avalanche vs Snowball Method: Which Gets You Debt-Free Faster?
Compare debt avalanche and snowball methods with a real $38,000 debt portfolio. See which saves more money and which keeps you motivated to finish.
Where to Keep Your Emergency Fund for the Best Interest Rate
Compare HYSAs, money market accounts, CDs, and more for your emergency fund. Real October 2026 APY rates, a case study, and the CD ladder strategy explained.
The 50/30/20 Budget Rule Explained with Real Examples
Learn the 50/30/20 budget rule with real examples at $50K, $75K, and $100K income. Includes a case study, category breakdowns, and when the rule doesn't work.