Guides / Mortgage Strategy
15-Year vs 30-Year Mortgage: Which Saves You More Money?
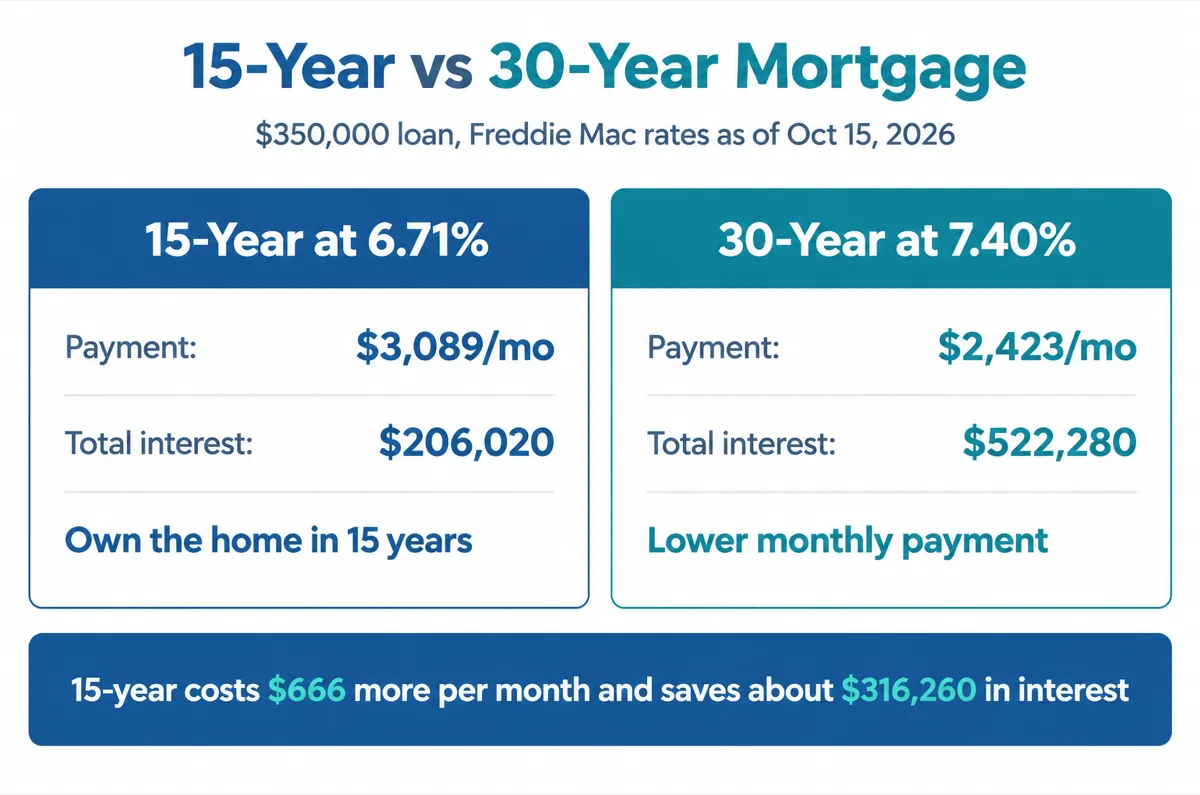
The difference between a 15-year and 30-year mortgage on a $350,000 loan is not a rounding error — it is $666 per month and about $316,260 in total interest over the life of the loan. This guide runs every number at mid-October 2026 PMMS averages so you can see exactly what each term costs, where the break-even point falls, and which option fits your budget.
Last updated: October 2026
TL;DR - Quick Answer
- 15-year at 6.71%: $3,089/month, about $206,020 total interest, $556,020 total cost on a $350,000 loan
- 30-year at 7.40%: $2,423/month, about $522,280 total interest, $872,280 total cost on the same loan
- Monthly difference: $666 — enough to max a Roth IRA ($625/month) with about $41 left over
- Break-even on interest savings: Guaranteed from day one — the 15-year saves about $316,260 no matter what the market does
- Best for most buyers in fall 2026: 30-year for flexibility, with extra payments when cash flow allows
Use our Mortgage Calculator and Loan Comparison Calculator to model your exact loan amount and rate.
The Real Numbers: $350,000 at Fall 2026 Rates
The national median existing single-family home price was $434,900 in Q2 2026, according to the National Association of Realtors (industry survey data). A buyer putting roughly 20% down near that median often borrows about $350,000 — a round number that makes the math easy to follow. As of the Freddie Mac Primary Mortgage Market Survey week ending October 15, 2026, the average 15-year fixed rate was 6.71% and the 30-year fixed was 7.40% — a 0.69-percentage-point spread.
On that $350,000 principal, the 15-year payment comes to $3,089 per month. Over 180 payments, you send the lender $556,020 and pay about $206,020 in interest. The 30-year payment drops to $2,423 per month — $666 less — but over 360 payments you send $872,280 total and pay about $522,280 in interest. That is about $316,260 more in interest charges for the privilege of a lower monthly bill.
The trade-off is cash flow versus total cost. The 15-year borrower pays an extra $7,992 per year ($666 x 12) but owns the home outright in 2041 instead of 2056. After 15 years, the 15-year borrower has zero mortgage balance. The 30-year borrower still owes about $263,023 and faces 180 more payments totaling about $436,140. From year 16 onward, the 15-year borrower has $3,089 per month freed up — while the 30-year borrower continues writing checks.
The opportunity cost matters. If you take the 30-year and invest the $666 monthly difference in a diversified index fund at a hypothetical 7% average annual return (not guaranteed), that investment grows to about $211,100 over 15 years. You still owe about $263,023 on the mortgage, so your net position is roughly $51,900 worse off than the 15-year borrower who owns the home free and clear. At a hypothetical 10% return, the invested portfolio hits about $276,100 — enough to pay off the remaining balance with about $13,100 left over. The break-even investment return sits around 9.4%: above that, the 30-year plus investing wins; below it, the 15-year wins on total wealth.
Closing costs are nearly identical for both terms — typically $6,500 to $8,500 on a $350,000 loan (roughly 2% of the purchase price). Lenders do not charge a premium for the shorter term. The only difference is qualification: because the 15-year payment is $666 higher, you need roughly $2,379 more in monthly gross income to qualify under the 28% housing ratio ($666 / 0.28 = $2,379).
Sources Freddie Mac Primary Mortgage Market Survey (week ending Oct. 15, 2026), NAR Q2 2026 existing-home median price release (Aug. 4, 2026). Checked October 2026. NAR median price is industry survey data (Tier 2). Loan examples use PMMS averages for 20%-down, excellent-credit conventional loans.
15-Year vs 30-Year: Head-to-Head Comparison
Every figure below assumes a $350,000 loan with no extra payments, property taxes, or insurance. Add $350 to $550 per month for taxes and insurance depending on your state.
| Metric | 15-Year (6.71%) | 30-Year (7.40%) | Difference |
|---|---|---|---|
| Monthly principal + interest | $3,089 | $2,423 | +$666/mo (15yr) |
| Total payments over life of loan | $556,020 | $872,280 | +$316,260 (30yr) |
| Total interest paid | $206,020 | $522,280 | $316,260 saved (15yr) |
| Loan paid off by | Year 15 (2041) | Year 30 (2056) | 15 years sooner |
| Balance after 15 years | $0 | $263,023 | $263,023 remaining |
| Amount paid in first 15 years | $556,020 | $436,140 | +$119,880 (15yr) |
| Invest $666/mo at 7% for 15 years | N/A | $211,100 | Still ~$51,900 short of payoff |
| Min. gross income (28% rule) | $11,032/mo ($132,386/yr) | $8,654/mo ($103,843/yr) | +$28,543/yr (15yr) |
*Rates reflect Freddie Mac PMMS averages for the week ending Oct. 15, 2026 (15-year: 6.71%, 30-year: 7.40%). Property taxes, insurance, and PMI not included. Investment return assumes a hypothetical 7% annual average in a taxable brokerage account (not guaranteed).
Source Freddie Mac PMMS archive (Oct. 15, 2026). Checked October 2026.
Break-Even Analysis: When Does Each Option Win?
The 15-year mortgage wins on guaranteed interest savings from month one — about $316,260 over the full term, with no market risk attached. But the 30-year plus invest strategy closes the gap over time. In year 1, investing the $666 difference at a hypothetical 7% yields about $8,255 while you paid $7,992 extra on the 15-year — a small advantage to investing. By year 5, the investment portfolio reaches about $47,700 versus $39,960 in cumulative extra 15-year payments, a $7,740 lead.
The crossover happens around year 14, when the invested balance exceeds the cumulative extra payments — but you still owe about $263,023 on the mortgage at that point. True wealth parity requires roughly a 9.4%+ average investment return over 15 years, or reaching year 15 with a hypothetical 10% return (about $276,100 invested vs. $263,023 owed, a ~$13,100 surplus). Below 7% returns, the 15-year mortgage builds more net wealth in most years because the guaranteed interest savings outpace weaker market performance.
Key Insight
The 15-year mortgage is a guaranteed 6.71% return on every extra dollar (your PMMS rate). To beat it by investing, you need consistent after-tax returns above that level for 15 straight years — historically plausible but never guaranteed. From 2000 through 2010, the S&P 500 returned about 0.4% annually (historical, NYU Stern Damodaran data). Past performance does not predict future results.
Sources NYU Stern (Damodaran), Historical Returns on Stocks, Bonds and Bills (Jan. 2026), S&P Dow Jones Indices, S&P 500 historical returns research (Sept. 2021). Checked October 2026. Stock returns cited are historical U.S. averages, not forecasts.
Who Should Choose a 15-Year vs 30-Year Mortgage
Choose the 15-Year If...
- Your total housing cost (PITI) stays under 28% of gross income — on $145,000/year, that means $3,383/month or less including taxes and insurance
- You have 6+ months of expenses saved (about $21,000 minimum on a ~$3,465/month PITI payment)
- You are 50 or older and want the mortgage paid off before a planned retirement at 65
- You value guaranteed returns over market volatility — about $316,260 in interest savings with zero risk on a $350,000 loan at mid-October 2026 PMMS rates
- Your income is stable and unlikely to drop — dual-income household with combined tenure of 5+ years at current employers
Choose the 30-Year If...
- The $666/month difference would strain your budget or prevent retirement contributions (401(k) match, Roth IRA)
- You plan to invest the payment difference — $666/month at a hypothetical 7% grows to about $211,100 in 15 years
- Your income is variable (commission, freelance, startup equity) and you need payment flexibility during lean months
- You may move within 10 years — total interest paid on a $350,000 30-year loan after 7 years is roughly $175,000 vs. about $139,000 on a 15-year, a ~$36,000 gap that may not justify the higher payment
- You want to qualify for a larger home — the 30-year requires about $28,500 less annual income to meet the 28% ratio on the same loan amount
Case Study: David and Sarah, $145K Combined Income in Portland, OR
Their Situation
- Combined gross income: $145,000/year ($12,083/month)
- Location: Portland, OR — median home price $485,000
- Purchase price: $418,000 (14% below median)
- Down payment: 20% ($83,600), loan amount: $334,400
- Monthly debts: $380 student loans, $420 car payment
- Emergency fund: $28,000 (6.2 months of expenses)
- 401(k): both contributing 8% with 4% employer match
The Numbers
- Property tax: $348/month (1.0% of value)
- Homeowners insurance: $165/month
- 15-year PITI: $3,465/month (28.7% of gross income)
- 30-year PITI: $2,828/month (23.4% of gross income)
- 15-year total interest: about $196,910 over 180 payments
- 30-year total interest: about $499,110 over 360 payments
- Total debt ratio (30yr): 30.0% — within 36% limit
- Total debt ratio (15yr): 35.3% — within limit but tight
What They Chose: 30-Year with a Plan
David and Sarah chose the 30-year at 7.40% ($2,315/month P&I) even though the 15-year fits within lender limits at 35.3% total DTI. Their reasoning: with $2,100/month average childcare costs starting in 2027, the 15-year's $3,465 PITI plus $800 in existing debts leaves just $918/month for everything else after childcare — too thin for comfort. Their monthly budget with the 30-year: $2,828 housing + $800 debts + $1,450 groceries and utilities + $800 retirement + $500 savings = $6,378 against $8,200 take-home pay, leaving $1,822 in flex money. They auto-deposit $400/month into a brokerage account (most of the $637 payment difference) and plan to refinance to a 15-year when their student loans are paid off in 2029, freeing $380/month. At that point, their projected income of $158,000 makes the 15-year PITI ($3,465) about 26.3% of gross — comfortably within range.
Step-by-Step: How to Choose Your Mortgage Term
Calculate both payments on your exact loan amount
Plug your loan amount into both term options. On $334,400, the difference is about $637/month ($2,952 vs. $2,315). On $350,000, it is $666/month at mid-October 2026 PMMS averages. Know your exact number before deciding — a $50,000 difference in loan size shifts the monthly gap by roughly $95.
Run the 28/36 rule with PITI, not just principal and interest
Add property taxes ($300-$600/month in most states), insurance ($120-$250/month), and PMI if putting less than 20% down ($150-$280/month). David and Sarah's 15-year PITI of $3,465 looked manageable on P&I alone ($2,952) but felt tight once student loans, car payments, and upcoming childcare costs were factored in.
Stress-test your budget at the higher payment
Could you cover the 15-year payment if one income dropped by 50% for 6 months? On $145,000 combined income, half is $72,500 ($6,042/month gross). A $3,465 housing payment would consume 57.4% of one income — risky. The $2,828 30-year payment consumes 46.8%, still tight but survivable with their $28,000 emergency fund.
Compare the opportunity cost honestly
Will you actually invest the $666/month difference, or will it absorb into lifestyle spending? Many households who choose a 30-year for "investment flexibility" never invest the difference. If you will not invest it, the 15-year saves about $316,260 in guaranteed interest on a $350,000 loan. If you will invest consistently, run the break-even at your expected return rate.
Consider the hybrid: 30-year with extra principal payments
Take the 30-year at $2,423/month and add $400/month in extra principal. You pay off the $350,000 loan in about 20 years instead of 30, save about $208,400 in interest, and retain the flexibility to skip extra payments during tight months. This is the approach most financial planners recommend for buyers under age 45 in fall 2026.
Source IRS IR-2025-111 (2026 IRA contribution limits, Nov. 13, 2025). Checked October 2026. Roth IRA limit $7,500 in 2026 (also in tax-data.ts).
Run Your Own Numbers
Every loan amount and rate combination produces a different answer. Use our free calculators to compare 15-year and 30-year scenarios on your exact home price and down payment.
Frequently Asked Questions
How much more does a 15-year mortgage cost per month?
On a $350,000 loan at mid-October 2026 Freddie Mac PMMS averages, a 15-year mortgage at 6.71% costs $3,089 per month versus $2,423 for a 30-year at 7.40% — a difference of $666 per month. That extra $666 buys you a mortgage-free life 15 years sooner and saves about $316,260 in total interest over the life of the loan.
Is a 15-year mortgage always cheaper in the long run?
A 15-year mortgage always saves on total interest — on a $350,000 loan you pay about $206,020 in interest versus $522,280 on a 30-year, a $316,260 difference. However, if you invest the $666 monthly payment difference at a hypothetical 7% average return (not guaranteed), your portfolio grows to about $211,100 over 15 years — still roughly $52,000 short of the $263,000 balance you would owe on the 30-year at that point. The 15-year wins on guaranteed savings, but the gap narrows when you factor in investment opportunity cost and higher historical stock returns.
What are typical 15-year and 30-year mortgage rates in fall 2026?
As of the Freddie Mac Primary Mortgage Market Survey week ending October 15, 2026, the national average 30-year fixed rate was 7.40% and the 15-year fixed rate was 6.71% — a 0.69-percentage-point spread. PMMS rates apply to conventional, conforming purchase loans with 20% down and strong credit; your quoted rate will differ.
Can I switch from a 30-year to a 15-year mortgage later?
Yes, through refinancing. If rates drop further or your income rises, you can refinance a remaining balance from a 30-year to a 15-year term. Refinancing costs typically run $3,000 to $6,000 in closing fees, so the break-even point is usually 18 to 36 months of interest savings. Alternatively, you can simulate a 15-year payoff by adding about $666 per month in extra principal payments on a $350,000 loan at current PMMS averages without refinancing.
Who should choose a 15-year mortgage over a 30-year?
Choose a 15-year mortgage if your full housing payment (PITI) stays below 28% of gross income ($3,383/month on a $145,000 salary), you have at least 6 months of emergency savings (roughly $21,000 on a $3,465/month PITI payment), you are within 20 years of retirement, or you prioritize guaranteed interest savings over market returns. Skip the 15-year if the higher payment would push your total debt above 36% of income or leave you with less than $15,000 in liquid savings.
How do mortgage rates affect the 15-year vs 30-year decision?
Higher rates raise payments on both terms, but the 15-year still cuts total interest dramatically — at mid-October 2026 PMMS averages (6.71% / 7.40%), the 15-year saves about $316,260 in interest on a $350,000 loan versus a 30-year. When rates fall, both payments drop and the dollar gap between terms usually shrinks. Many buyers lock a 30-year for flexibility and either refinance to a 15-year later or add extra principal when cash flow allows.
Related Guides
How Much House Can I Afford? Complete Guide by Income Level
Learn exactly how much home you can afford based on your salary, debts, and down payment. Includes income-based tables, a real case study, and the formulas lenders actually use.
Pay Off Mortgage Early vs Invest: The Math Behind the Decision
Should you pay off your mortgage early or invest the extra money? We run the real numbers at today's rates so you can see exactly which option builds more wealth.