Guides / Mortgage Strategy
Pay Off Mortgage Early vs Invest: The Math Behind the Decision
You have an extra $500 a month. Should you throw it at your mortgage or put it in an index fund? This is one of the most debated questions in personal finance — and the answer depends on numbers most people never bother to run. This guide does the math for you.
Last updated: October 2026
TL;DR - Quick Answer
- If your mortgage rate is below 5%: Investing almost always wins — historically by a wide margin
- If your mortgage rate is 6-7%: Investing still has the edge mathematically, but the gap narrows enough that either choice is reasonable
- If your mortgage rate is 8%+: Paying off the mortgage is a guaranteed high return — strongly consider it
- The hybrid approach: Max your 401(k) match first, then split extra cash between mortgage and investing
Use our Mortgage Calculator and Compound Interest Calculator to run your exact scenario.
Why This Decision Matters More Than You Think
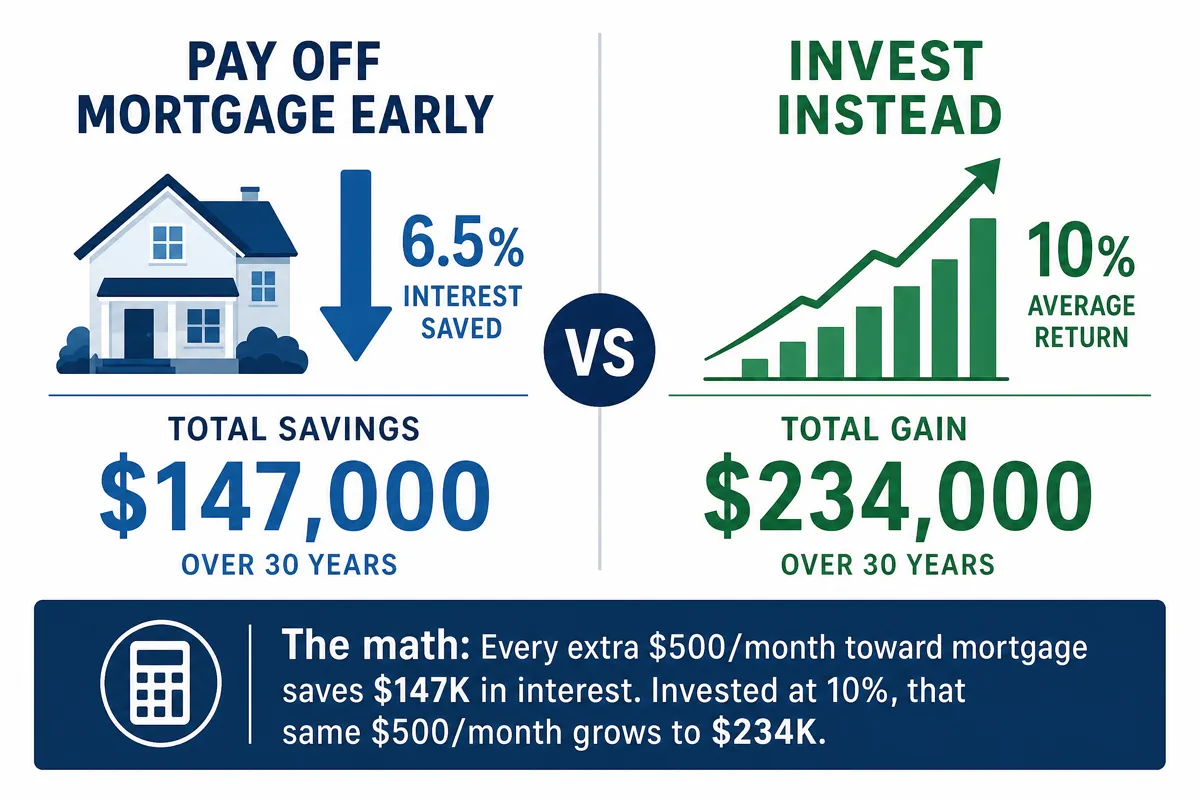
The difference between paying off your mortgage early and investing isn't just a few thousand dollars — over a 20- to 30-year time horizon, it can mean a six-figure swing in your net worth. The decision boils down to one question: is it better to pay off mortgage early and earn a guaranteed return equal to your interest rate, or invest the money and chase a historically higher but uncertain return?
When you make an extra mortgage payment, you're effectively earning a risk-free return equal to your mortgage interest rate. With a 7.40% mortgage — the Freddie Mac PMMS average 30-year fixed rate as of mid-October 2026 — every extra dollar you pay avoids future interest at that rate. No market crash, no bad quarter, no volatility — just a guaranteed return (home equity is not as liquid as cash).
When you invest instead, you're betting on long-term historical returns of the stock market. From 1928 through 2024, the S&P 500 averaged about 10.0% per year with dividends reinvested (geometric mean; NYU Stern Damodaran and S&P Dow Jones Indices historical data) — higher than most mortgage rates historically, but not guaranteed going forward. Calendar-year 2008 total return was about -36.6% (Damodaran). Early 2020 saw a rapid, sharp drawdown before markets recovered. Past performance does not predict future results.
Sources Freddie Mac Primary Mortgage Market Survey (week ending Oct. 15, 2026), NYU Stern (Damodaran), Historical Returns on Stocks, Bonds and Bills (Jan. 2026), S&P Dow Jones Indices, S&P 500 historical returns research (Sept. 2021). Checked October 2026. Stock figures are historical U.S. averages, not forecasts.
The mathematical answer and the right-for-you answer are often different. Let's start with the math, then factor in the human elements.
The Numbers: $500/Month Extra Over 20 Years
Let's use a common scenario: you have a $300,000 mortgage at 7.40% interest (Freddie Mac PMMS average as of mid-October 2026) on a 30-year fixed term. You're 5 years in and have an extra $500/month to either put toward your mortgage or invest in a broad market index fund.
Option A: Pay Off Mortgage Early
Your standard monthly payment on a $300,000 mortgage at 7.40% is about $2,077. Adding $500/month brings your total to about $2,577. Here's what happens:
- Remaining balance (after 5 years): approximately $283,600
- Without extra payments: 25 years remaining, about $339,600 more in interest
- With $500/month extra: paid off in ~15.4 years instead of 25
- Total interest saved: approximately $147,400
- You own your home free and clear about 9 years early
Option B: Invest the $500/Month
Instead of extra mortgage payments, you invest $500/month in a low-cost S&P 500 index fund. Assuming historical average returns:
- At a hypothetical 10% average annual return: $500/month grows to approximately $379,700 after 20 years
- At a hypothetical 7% return: grows to approximately $260,500
- Total invested out of pocket: $120,000
- Investment gain at 10%: approximately $259,700
- Investment gain at 7%: approximately $140,500
Head-to-Head Comparison
| Metric | Pay Off Mortgage | Invest (10% return) | Invest (7% return) |
|---|---|---|---|
| Total out-of-pocket | $120,000 | $120,000 | $120,000 |
| Financial benefit | $147,400 saved | $259,700 gained | $140,500 gained |
| Mortgage paid off | 9 years early | On schedule (year 30) | On schedule (year 30) |
| Risk level | Zero (guaranteed) | Moderate-High | Moderate-High |
| Liquidity | Locked in home equity | Fully liquid | Fully liquid |
| Net advantage vs. payoff | Baseline | +$112,300 | -$6,900 |
*Assumes $300K mortgage at 7.40% (Freddie Mac PMMS, week ending Oct. 15, 2026), 30-year fixed, extra payments starting in year 6. Investment returns are hypothetical and nominal. Tax implications not included — see tax section below.
Source Freddie Mac PMMS archive (Oct. 15, 2026). Checked October 2026.
Real Case Study: Marcus and Elena, $138K Combined Income
Their Situation
- Combined gross income: $138,000/year in Denver, CO
- Mortgage: $355,000 at 6.75%, 30-year fixed (3 years in)
- Current monthly payment: $2,302
- Remaining balance: about $343,000
- Extra available per month: $800
- Marcus's 401(k): contributing 6% (employer matches 4%)
- Elena's 401(k): contributing 5% (employer matches 3%)
- No other debt
The Decision
- Both already get full employer match (free 3-4% return)
- 6.75% mortgage rate is in the "gray zone"
- Elena wants security of faster payoff
- Marcus wants the upside of market returns
- Solution: hybrid approach
What They Did: The 50/50 Split
Marcus and Elena split their $800/month: $400 extra toward the mortgage and $400 into a Vanguard Total Stock Market index fund (VTSAX, 0.04% expense ratio). After 27 months, their mortgage balance is about $320,300 (vs. about $332,000 without extra payments — roughly $11,600 ahead), and their investment account holds about $11,700 ($10,800 contributed + ~$900 growth at a hypothetical 7% average return). They estimate the mortgage will be paid off about 6 years early, while the investment account will hold roughly $180,000 by the time they hit year 20. They have the psychological win of progress on both fronts, and the flexibility to shift the ratio if rates drop (refi and invest more) or the market tanks (lean into mortgage payments). They are sticking with the 50/50 split to stay disciplined through any future downturn rather than chasing short-term market moves.
How Your Mortgage Rate Changes the Answer
The decision is heavily influenced by your specific mortgage rate. Here's how the 20-year outcome shifts for $500/month extra, assuming a 10% average stock market return:
| Mortgage Rate | Interest Saved (Payoff) | Investment Growth (Invest) | Winner |
|---|---|---|---|
| 3.0% | $44,000 | $259,700 | Invest (by $216K) |
| 4.5% | $74,000 | $259,700 | Invest (by $186K) |
| 5.5% | $96,500 | $259,700 | Invest (by $163K) |
| 7.40% (Oct. 2026 PMMS avg) | $147,400 | $259,700 | Invest (by $112K) |
| 7.5% | $150,400 | $259,700 | Invest (by $109K) |
| 8.5% | $181,600 | $259,700 | Invest (by $78K) |
| 10.0% | $233,900 | $259,700 | Invest (narrow edge) |
*Investment returns assume a hypothetical 10% nominal average. Interest saved varies by remaining balance and years left. Figures are approximate — use our calculators for your exact scenario.
Key Insight
Historical U.S. stock returns (about 10% geometric mean since 1928, Damodaran) often favor investing when your mortgage rate is below high single digits — but returns are not guaranteed. At the mid-October 2026 PMMS average of 7.40%, prepaying still saves a meaningful guaranteed amount while investing keeps liquidity. The payoff return is fixed; the market includes years like 2008 (about -36.6% total return, Damodaran).
Tax Factors Most People Miss
Taxes change the math in important ways that favor investing in some scenarios and mortgage payoff in others:
Mortgage Interest Deduction
If you itemize deductions (only about 9.5% of returns in tax year 2022 per IRS Statistics of Income, because the 2026 standard deduction is $32,200 for married couples filing jointly), your effective mortgage rate is lower than the stated rate. In the 22% tax bracket, a 7.40% mortgage effectively costs about 5.77%. Deductible home acquisition debt is generally capped at $750,000 for homes bought after Dec. 15, 2017 (IRS Publication 936).
Sources IRS Rev. Proc. 2025-32 (tax year 2026 inflation adjustments), IRS Publication 936 (2026), home mortgage interest deduction, IRS SOI, Individual Income Tax Returns preliminary data (tax year 2022). Checked October 2026. Itemization share is IRS SOI tax year 2022; standard deduction from Rev. Proc. 2025-32 via tax-data.ts.
Capital Gains Tax on Investments
Investment gains are taxed when you sell. Long-term capital gains (held over 1 year) are taxed at 0%, 15%, or 20% depending on taxable income (IRS Topic 409). For a married couple with moderate taxable income, 15% is common — so a hypothetical 10% gross return is closer to 8.5% after taxes, narrowing the spread versus prepaying.
Source IRS Topic 409, Capital Gains and Losses. Checked October 2026.
Tax-Advantaged Accounts Change Everything
If you invest in a 401(k) or Roth IRA instead of a taxable brokerage account, the math shifts dramatically. Roth IRA gains are completely tax-free. 401(k) contributions reduce your current taxable income. An employer match is an immediate 50-100% return that no mortgage payoff can compete with. Always capture the full employer match before putting extra money toward the mortgage.
When Paying Off Your Mortgage Early Is the Better Choice
Despite the math favoring investing in most scenarios, there are real situations where accelerating your mortgage payoff is the smarter move:
- You're within 5-7 years of retirement. Entering retirement without a mortgage payment dramatically reduces your required withdrawal rate. A $2,000/month mortgage payment means you need $600,000 less in your retirement portfolio (using the 4% rule).
- Your mortgage rate is above 7%. At rates this high, the guaranteed return from payoff starts to rival historical stock market returns — with zero risk.
- You've already maxed out tax-advantaged accounts. If your 401(k), Roth IRA, and HSA are fully funded, the comparison shifts to taxable investing vs. mortgage payoff, where the after-tax investment return is lower.
- You have low risk tolerance or sleep poorly. The psychological burden of debt is real for many homeowners — eliminating a monthly payment can matter as much as spreadsheet math.
- You're in a high-tax state with no itemized deductions. Without the mortgage interest deduction, your effective rate equals your stated rate, making payoff relatively more attractive.
Step-by-Step: How to Make Your Decision
Max out your employer 401(k) match first
This isn't optional. A 50% employer match is an instant 50% return — no mortgage payoff or market investment comes close. If your employer matches 4% and you earn $80,000, contribute at least $3,200/year to get the full $1,600 match.
Build a 3-6 month emergency fund
Neither extra mortgage payments nor investments help if you lose your income and can't make the regular payment. Keep $15,000-$30,000 in emergency savings before aggressively tackling either option. The FDIC national average savings deposit rate was 0.38% in October 2026; competitive online savings accounts often pay well above that average.
Source FDIC National Rates and Rate Caps (October 2026 release). Checked October 2026.
Pay off any debt above your mortgage rate
Credit card debt at 21%+ (Fed G.19 average was 21.19% in Aug. 2026)? Car loan at 8%? Pay those off before making extra mortgage payments. The guaranteed return is higher than either your mortgage rate or expected stock returns.
Source Federal Reserve G.19 Consumer Credit (Aug. 2026 credit card APRs). Checked October 2026.
Compare your effective mortgage rate to expected returns
Calculate your after-tax mortgage rate (rate x (1 - tax bracket) if you itemize). Compare it to your expected after-tax investment return (7-8% in a taxable account, 10% in tax- advantaged). If the spread is 3%+ in favor of investing, lean toward investing.
Factor in your personal risk tolerance and timeline
If you're 15+ years from retirement with stable income, you can weather market volatility — lean toward investing. If you're 5-10 years out, the guaranteed return of mortgage payoff becomes more valuable. Use our Investment Return Calculator to model different scenarios.
3 Common Arguments — And Why They're Only Half Right
"You can always borrow against your home equity"
True, but a HELOC or cash-out refinance comes with closing costs, variable rates, and the risk of owing more than your home is worth in a downturn. Investments in a brokerage account are instantly liquid — you can sell and have cash in 2 business days. Home equity is the least liquid form of wealth you can hold.
"The stock market always goes up long-term"
Over many long historical windows, U.S. stocks have recovered from severe drawdowns — but decade-long flat periods happen (2000-2010 returned about 0.4% annually per Damodaran data). Your specific timing matters. If you retire in a downturn, a paid-off home provides safety that a depleted portfolio cannot.
"Inflation makes your mortgage cheaper over time"
This is correct — a fixed $2,000/month payment feels smaller in 10 years when inflation has raised wages. But this argument applies equally whether you make extra payments or not. Your fixed payment stays the same regardless. The real question is what earns a better return: the extra payment or the invested dollar. Inflation doesn't change that comparison.
Sources IRS IR-2025-111, 2026 retirement plan limits (Nov. 13, 2025), NYU Stern (Damodaran), Historical Returns on Stocks, Bonds and Bills (Jan. 2026), S&P Dow Jones Indices, S&P 500 historical returns research (Sept. 2021). Checked October 2026. Retirement limits from tax-data.ts (IRS IR-2025-111). Stock returns are historical, not guaranteed.
Run Your Own Numbers
Every mortgage and financial situation is different. Use our free calculators to see exactly how each scenario plays out for you.
Frequently Asked Questions
Is it better to pay off my mortgage early or invest?
Mathematically, investing often wins if your expected after-tax return exceeds your mortgage rate — but market returns are not guaranteed. With a 7.40% mortgage (Freddie Mac PMMS average 30-year fixed as of mid-October 2026) and a hypothetical 10% average stock return, investing $500/month for 20 years produces about $112,000 more wealth than prepaying in our baseline example. Paying early delivers a guaranteed return equal to your mortgage rate.
What if my mortgage rate is very low — say 3%?
A low rate makes investing even more attractive on paper. At 3%, the spread between your mortgage cost and historically observed stock returns is wide. Paying off a 3% mortgage early is essentially choosing a guaranteed 3% return over historically higher (but uncertain) market returns. Many planners would prioritize diversified investing once higher-rate debt and employer matches are covered.
Should I factor in the mortgage interest deduction?
Yes, but its impact is smaller than most people think. IRS Statistics of Income data show only about 9.5% of returns itemized in tax year 2022, because the standard deduction is $32,200 for married couples in 2026. If you itemize, the deduction lowers your effective mortgage rate by your marginal bracket — for example, 7.40% becomes about 5.77% in the 22% bracket. Home acquisition debt is generally limited to $750,000 for homes purchased after Dec. 15, 2017 (IRS Pub. 936).
What about the emotional benefit of being debt-free?
This is real and valid. Carrying a mortgage is a significant source of financial stress for many households. If being debt-free lets you sleep better, take career risks, or retire with confidence, the peace of mind can outweigh a few percentage points of return. Personal finance is personal — the mathematically optimal answer isn't always the right one for you.
Can I do both — pay extra on my mortgage AND invest?
Absolutely, and this is what many financial planners recommend. A common approach: invest enough to get your full employer 401(k) match (free money), fund a Roth IRA ($7,500 limit in 2026), then split remaining extra cash 50/50 between extra mortgage payments and taxable investing. This hedges your bets and builds wealth on two fronts.
Should I refinance before deciding to pay extra or invest?
If your current mortgage rate is well above today's PMMS averages, refinancing first may be the best move. Dropping from 8.0% to 7.40% on a $300,000 balance with 25 years remaining saves roughly $120/month in principal and interest, freeing cash for either extra payments or investing. Factor in closing costs (typically $3,000-$6,000) — you need to stay in the home long enough to break even, usually 18-24 months. Use our Mortgage Calculator and Refinance Calculator to run the exact numbers.
Related Guides
How Much House Can I Afford? Complete Guide by Income Level
Learn exactly how much home you can afford based on your salary, debts, and down payment. Includes income-based tables, a real case study, and the formulas lenders actually use.
How to Start Investing with $1,000: A Beginner's Step-by-Step Guide
Start investing with just $1,000. Learn which account to open, what to buy (VTI, VOO, VTSAX), and how $100/month grows to six figures over time.