Guides / Housing Strategy
Rent vs Buy in 2026: How to Make the Right Decision
"Should I rent or buy a house?" is the question behind every housing search — and the honest answer is not always "buy." With 30-year fixed mortgage rates averaging 7.40% in the Freddie Mac PMMS for the week of October 15, 2026 — up from 6.65% in August — the monthly cost of buying has moved further from renting. This guide compares real monthly costs, break-even timelines, and a decision framework built on specific numbers, not real estate slogans.
Last updated: October 2026
TL;DR - Quick Answer
- Break-even timeline (Oct 2026): Often 4.5–6 years at 7.40% PMMS mortgage rates before buying costs less than renting in many scenarios — longer than when rates were near 6.5% mid-year
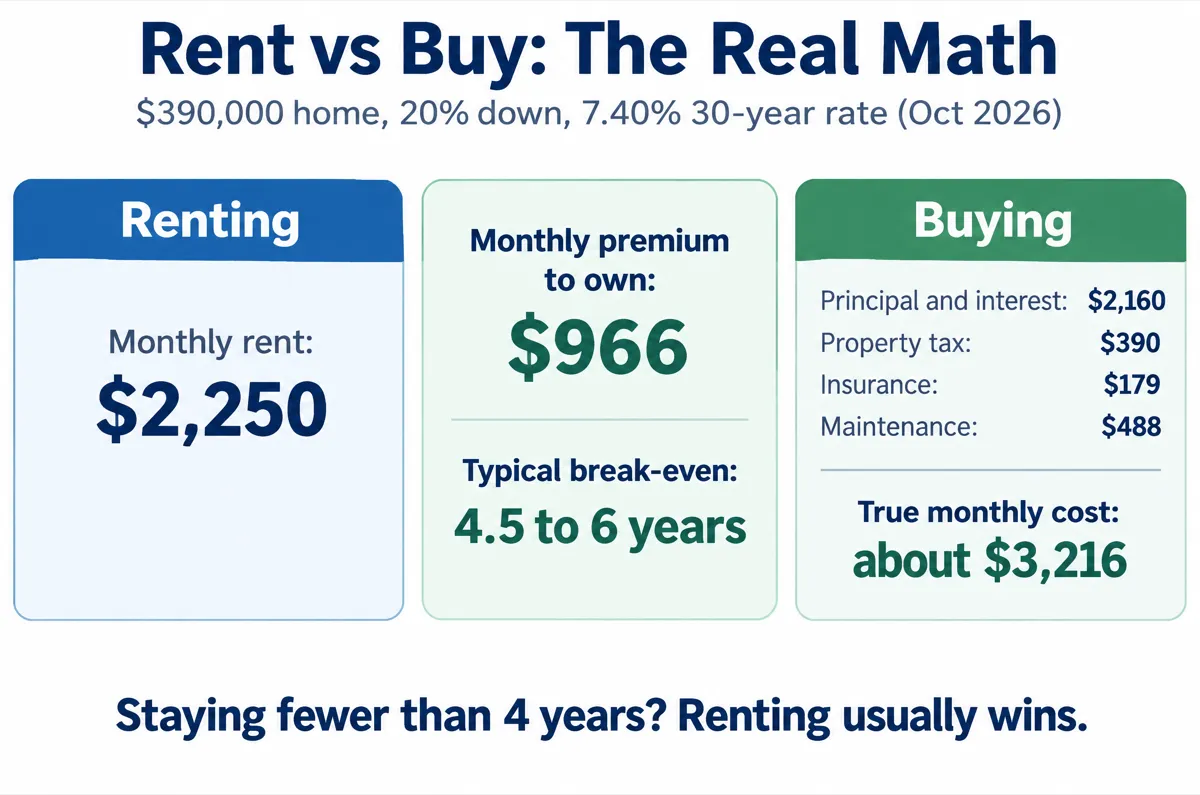
- Monthly cost gap: Owning a $390,000 home costs ~$3,216/month vs. $2,250/month rent — a $966/month premium
- Hidden buy costs: $8,000–$15,000 closing fees, 1–2% annual maintenance, plus opportunity cost on your down payment
- Rent if: Moving within 5 years, unstable income, or buying would drain your emergency fund below 3 months
- Buy if: Staying 6+ years, stable dual income, 20% down saved, and total housing stays under 28% of gross pay
Use our Rent vs Buy Calculator to run your exact scenario.
The Real Cost of Buying vs Renting
Most rent-vs-buy debates compare a $2,250 rent check to a $2,160 mortgage payment and declare buying the winner. That comparison ignores $900–$1,100 in monthly costs that homeowners pay and renters never see. At 7.40% interest on a 30-year fixed loan (Freddie Mac PMMS, week of October 15, 2026), the sticker price is only the starting point.
Consider a $390,000 home with 20% down ($78,000). Your loan is $312,000. Principal and interest run $2,160 per month at the October 15, 2026 PMMS average of 7.40%. Property tax at 1.2% adds $390 per month (above the roughly 0.89% U.S. effective rate implied by 2024 Census ACS aggregates, but typical in many counties). Homeowner's insurance at 0.55% of value costs $179 per month. Maintenance and repairs at 1.5% of home value — the midpoint of the 1–2% rule — add $488 per month. Your true monthly ownership cost is $3,216, not $2,160. That is $966 more than the $2,250 rent payment next door (a worked example; the Census ACS 2024 U.S. median gross rent was $1,487).
Rates climbed from 6.65% (August 20, 2026 PMMS) to 7.40% (October 15, 2026), adding about $157 per month in P&I on a $312,000 loan — roughly $56,600 more interest over 30 years than financing at 6.65% (PMMS week of August 20, 2026).
Upfront costs widen the gap further. Closing costs on a $390,000 purchase typically run $7,800 to $19,500 (2–5% of the purchase price per the CFPB, excluding the down payment). Title insurance, appraisal fees, lender origination charges, and prepaid property taxes all hit at closing. A $78,000 down payment plus $11,700 in closing costs (3% midpoint) means $89,700 leaves your bank account before you hang a single picture.
Then there is opportunity cost — the investment return you give up by tying cash in a house. If you invested that $78,000 down payment in a diversified stock portfolio at a hypothetical 7% long-term annual return (historical U.S. stock returns have averaged near 10% over very long periods but vary sharply year to year), it could grow to roughly $153,400 over 10 years — not a guarantee. Parked in an FDIC-insured savings account at the October 2026 national average rate of 0.38%, it earns about $296 per year. Renters keep capital liquid; buyers convert it to illiquid home equity.
Sources Freddie Mac PMMS (30-year FRM 7.40%, Oct. 15, 2026), CFPB, closing costs typically 2–5% of purchase price, U.S. Census Bureau, ACS 2024 tables B25090 & B25082 (national effective property tax rate ~0.89%), Census ACS 2024, U.S. median gross rent $1,487, FDIC national deposit rates (savings 0.38%, October 2026 release). Checked October 2026. National effective property tax rate (~0.89%) = aggregate real estate taxes on owner-occupied homes (ACS table B25090) divided by aggregate home value (B25082). Insurance and maintenance percentages are planning assumptions.
To see how the monthly gap between owning and renting varies by location, our rent vs buy by state report sets the payment on the median home against the median rent in all 50 states and DC, and lists the mortgage rate at which the two cost the same in each state.
Hidden Costs Most Renters Never Pay
| Cost Category | Renting ($2,250/mo) | Buying ($390K home) |
|---|---|---|
| Monthly housing payment | $2,250 | $2,160 (P&I) |
| Property tax | $0 | $390 |
| Homeowner's insurance | $0 (renter's ~$18) | $179 |
| Maintenance & repairs (1.5%/yr) | $0 | $488 |
| Upfront costs | $2,250 (deposit) | $89,700 (down + closing) |
| True monthly cost | $2,250 | $3,216 |
*Assumes $390,000 purchase, 20% down, $312,000 loan at 7.40% for 30 years, 1.2% property tax, 0.55% insurance. Maintenance at 1.5% of home value per year. PMMS rate as of October 15, 2026.
Important Caveat
Renters who invest the $966 monthly difference ($11,592/year) at a hypothetical 7% long-term return build about $167,200 from those contributions alone over 10 years — on top of keeping their $78,000 down payment invested (roughly $314,000 combined at 7%, not guaranteed). Buying only wins if home appreciation and equity paydown exceed that renter wealth.
Break-Even Analysis: How Long Must You Stay?
The break-even point is when the total cost of buying equals the total cost of renting, accounting for equity gained through mortgage paydown and home appreciation. By mid-October 2026, PMMS 30-year fixed rates averaged 7.40% — up from 6.65% in August and well above the 3% era when break-even often hit in 3 to 4 years.
On the $390,000 home scenario above, buying starts $966 per month more expensive than renting from day one. Over the first year, that gap totals $11,592 in extra out-of-pocket costs, plus $11,700 in closing fees — $23,292 before counting equity from appreciation. At 2.6% annual home appreciation (FHFA national HPI, July 2025 to July 2026, released September 29, 2026), the property gains about $10,140 in value in year one. Mortgage principal paydown adds roughly $2,933 at 7.40%. Combined, you recover about $13,073 against $23,292 in excess cash costs — still underwater after year one in this simplified cash-flow view.
By year 5, cumulative extra ownership costs reach approximately $69,660 ($966/month × 60 months + $11,700 closing). Equity from appreciation (about $51,500 cumulative at 2.6%/year compounded) plus principal paydown (about $16,800) totals roughly $68,300 on top of the original $78,000 down payment — putting net housing cost near break-even with renting around years 4–5 in this scenario. If appreciation slows to 1%, break-even pushes toward year 6 or later.
At 7.40% mortgage rates, many planners cite 4.5 to 6 years as a typical break-even range nationally — longer than when rates were near 6.5% mid-year. Faster-appreciation metros can break even sooner; slow-growth markets can take 7 to 9 years. If you sell before break-even, you also pay 5–6% in agent commissions ($19,500–$23,400 on a $390,000 home), which can erase another year of equity gains.
The 7.40% rate environment skews early payments heavily toward interest. On a $312,000 loan at 7.40%, you pay about $22,990 in interest in year one versus roughly $2,933 toward principal. At 3%, that ratio was roughly $9,000 interest and $6,800 principal.
Sources FHFA, U.S. house prices up 2.6% year-over-year (July 2025–July 2026; release Sept. 29, 2026), Freddie Mac PMMS archive (30-year rates Aug.–Oct. 2026). Checked October 2026. Break-even timing depends on rent growth, taxes, maintenance, and whether you invest the monthly gap.
Side-by-Side: $2,250/Month Rent vs. $390,000 Home Purchase
The table below compares renting at $2,250/month against buying a $390,000 home with 20% down ($78,000), a $312,000 mortgage at 7.40%, and $11,700 in closing costs. Rent assumes 3% annual increases. Home assumes 2.6% annual appreciation (FHFA national year-over-year rate through July 2026).
| Metric | Rent ($2,250/mo) | Buy ($390K home) |
|---|---|---|
| Monthly cost (year 1) | $2,250 | $3,216 |
| Upfront cash required | $2,250 (deposit) | $89,700 (down + closing) |
| 5-year total housing spend | $143,347 | $204,660 |
| 5-year equity / net position | $0 equity | ~$148,500 equity |
| 5-year net cost (spend minus equity) | $143,347 | ~$56,170 |
| 10-year total housing spend | $309,525 | $397,676 |
| 10-year equity / net position | $0 equity | ~$234,000 equity |
| 10-year net cost (spend minus equity) | $309,525 | ~$163,700 |
| Break-even timeline | N/A | ~4–5 years |
| Flexibility to relocate | 30-day notice | 3–6 months to sell |
*Net cost = total cash spent minus home equity (down payment + principal paydown + appreciation at 2.6%/year). Does not include opportunity cost of invested down payment or selling costs. Rent total includes 3% annual increases. Rate: 7.40% 30-year fixed (PMMS, Oct. 15, 2026).
Case Study: Kevin and Lisa, $130K Combined, Charlotte, NC
Their Situation
- Combined gross income: $130,000/year ($10,833/month)
- Take-home pay: ~$8,100/month after taxes and 401(k)
- Current rent: $2,200/month for a 2-bedroom apartment
- Target purchase: $365,000 townhouse in South Charlotte
- Savings: $78,000 ($55,000 earmarked for down payment)
- Existing debts: $340/month (student loans + one car)
- Both employed 4+ years, expect to stay 8–10 years
The Numbers
- Down payment (20%): $73,000 on $365,000 purchase
- Loan amount: $292,000 at 7.40%, 30-year fixed (PMMS Oct. 15, 2026)
- P&I payment: $2,022/month
- Property tax: $292/month (0.96% planning rate; Mecklenburg County levy 48.31¢ per $100 for FY2025 plus city taxes)
- Insurance: $167/month (0.55% planning assumption)
- Maintenance (1.5%): $456/month
- True monthly ownership cost: $2,937/month
- Closing costs: ~$10,950 (3% of purchase price)
The Decision
Kevin and Lisa face a $737/month premium to own ($2,937 vs. $2,200 rent). Their total housing cost would be 27.1% of gross income — within the 28% guideline. Total debt ratio with their $340/month obligations hits 30.2%, still under the 36% lender limit. FHFA data show Charlotte metro house prices up about 1.4% year-over-year through Q2 2026, which modestly shortens break-even versus the national 2.6% pace.
They chose to buy — but with conditions. They kept $23,000 of their $78,000 savings as an emergency fund (2.8 months of expenses) rather than pushing to a 25% down payment. They budget $456/month for maintenance from day one. Lisa's employer requires in-office presence, and Kevin's remote role is stable for at least 3 years with a contract extension likely. Their 8–10 year horizon exceeds a roughly 4-year break-even in this scenario, and Charlotte's purchase price ($365,000) sits below the Census median new-home sale price of $410,700 (Q2 2026). Financing at 7.40% instead of 6.65% (August 2026 PMMS) costs them about $147/month more in P&I on their $292,000 loan — roughly $53,000 more interest over 30 years than at 6.65%. If either had expected a move within 4 years, renting at $2,200 and investing the $737 difference would have been the smarter financial move.
Sources FHFA / FRED, Charlotte-Concord-Gastonia HPI (Q2 2026), Census / HUD, median new home sale price $410,700 (Q2 2026), Mecklenburg County, FY2025 property tax rate 48.31¢ per $100. Checked October 2026.
When Renting Is the Smarter Financial Move
Renting is not a failure — it is often the optimal choice. Here are the situations where signing a lease beats signing a mortgage in 2026:
- You plan to move within 4 to 5 years. Selling costs (5–6% commission), closing costs, and the front-loaded interest on a 7.40% mortgage mean short-term owners rarely come out ahead. A 3-year stay on a $390,000 home typically costs $30,000–$40,000 more than renting after selling fees.
- Your income is unstable or variable. Commission sales, freelance work, startup equity, or a single-income household with one partner considering a career change all increase risk. A $3,216 monthly ownership cost is fixed; a $2,250 lease gives you flexibility to downsize if income drops 30%.
- Local home prices are elevated relative to rents. When the price-to-rent ratio exceeds 20 (home price divided by annual rent), buying rarely makes financial sense. A $390,000 home renting for $2,250/month has a ratio of 14.4 — borderline. In San Francisco, where a $1.3 million condo rents for $3,600/month (ratio 30.1), renting is almost always cheaper.
- You need career flexibility. Relocating for a $25,000 raise, accepting a 2-year assignment in another city, or pursuing an advanced degree all favor renting. Breaking a lease costs 1–2 months' rent ($2,250–$4,500). Selling a home costs $19,500–$23,400 plus 60–120 days on market.
- Buying would drain your emergency fund below 3 months. If a $78,000 down payment plus $11,700 closing costs leaves you with less than $15,000 in liquid savings on a $5,000/month budget, one HVAC failure ($8,500) or job loss creates a crisis. Renters call the landlord; homeowners write the check.
When Buying Makes Financial Sense
Buying builds wealth through forced savings (mortgage principal paydown) and appreciation — but only if you stay long enough and buy within your means. These conditions favor purchasing in 2026:
- You will stay 6 or more years. At 7.40% rates, years 5 to 6 is often where cumulative equity on a $390,000 home at roughly 2.6% FHFA-style appreciation exceeds the total premium paid over renting plus all transaction costs. Every year beyond 6 widens the gap in the buyer's favor.
- You have stable, predictable income. Dual-income households with 5+ years at current employers, W-2 salaried roles, and total housing under 28% of gross income ($3,033/month on $130,000/year) can absorb the $966/month ownership premium without sacrificing retirement savings or emergency fund contributions.
- You can put 20% down without touching your emergency fund. A $78,000 down payment on a $390,000 home plus $11,700 closing costs requires $89,700 upfront — and you should still have $20,000–$30,000 in liquid savings afterward. Kevin and Lisa kept $23,000 in reserve; that discipline is what makes buying safe.
- You want to build equity and control your housing costs. A fixed 7.40% mortgage payment stays $2,160 for 30 years while rent rises 3% annually ($2,250 today becomes $3,024 in 10 years). After year 10, the buyer's monthly cost advantage grows every year as rent climbs and the mortgage stays flat.
- Tax benefits apply to your situation. If you itemize deductions and your combined mortgage interest (about $22,990 in year one on a $312,000 loan at 7.40%) plus property taxes exceed the $32,200 standard deduction for 2026 married filing jointly, the mortgage interest deduction could lower your effective borrowing cost. On this scenario, year-one interest plus $4,680 property tax totals about $27,670 — below the standard deduction, so many couples still take the standard amount. IRS Statistics of Income (Publication 4801, tax year 2023) show about 9.5% of returns filed Schedule A; verify your situation.
Sources IRS Rev. Proc. 2025-32 (tax year 2026 inflation adjustments), IRS SOI Publication 4801 (Rev. 6-2026), Schedule A filings tax year 2023, SEC, Beginners' Guide to Asset Allocation (stocks and long-term risk). Checked October 20, 2026. Standard deduction shown is $32,200 MFJ for tax year 2026.
Step-by-Step Decision Framework
Work through these five steps in order. Each one either qualifies you to buy or points you toward renting for now.
Confirm your timeline: how long will you stay?
If the answer is under 4 to 5 years, rent unless you have a strong reason unrelated to money (aging parents nearby, kids in a specific school district with no rental options). At 7.40% PMMS rates, break-even often requires at least 4.5 years in most markets. Write down a realistic year count — not "forever," but "until 2034 when our youngest starts college."
Calculate true monthly cost for both options
For buying, add P&I + property tax + insurance + maintenance (1–2% of home value/year). For renting, include renter's insurance (~$18/month). Compare the gap — if it exceeds 25% of your take-home pay, buying may strain your budget. On $8,100 take-home, a $737/month gap (Kevin and Lisa) is 9.1% — manageable. A $1,200 gap would be 14.8% — risky.
Verify you can afford the down payment plus reserves
You need 20% down ($73,000 on a $365,000 home), $8,000–$15,000 closing costs, and 3–6 months of expenses ($15,000–$30,000) remaining in savings after closing. Total required: roughly $96,000–$118,000 in accessible funds. If you have $75,000 total, you are not ready to buy a $365,000 home — Kevin and Lisa had just enough because their target price matched their savings.
Run the break-even calculation for your market
Plug your rent, target home price, down payment, rate, and expected appreciation into our Rent vs Buy Calculator. If break-even exceeds your planned stay by 2+ years, renting wins on math alone. Charlotte at roughly 2–3% annual appreciation broke even in about 4 years for Kevin and Lisa; a flat market at 1% would push that to 6+ years.
Factor in non-financial priorities, then decide
Stability for children, freedom from landlord rules, ability to renovate, and pride of ownership have real value — but assign them a dollar figure. If owning costs $737/month more and break-even is 4 years, you are paying $35,400 in premium over 4 years for intangibles. If that trade-off feels worth it and steps 1–4 check out, buy. If the math fails step 4, rent and revisit when rates drop further or your timeline lengthens.
Run Your Rent vs Buy Numbers
Every market, income, and timeline produces a different answer. Use our free calculators to compare your exact rent payment against the true cost of owning.
Frequently Asked Questions
Should I rent or buy a house in 2026?
As of mid-October 2026, Freddie Mac’s PMMS 30-year fixed rate averaged 7.40% (week of October 15). Renting often wins financially if you plan to move within 4 to 5 years. Buying makes sense when you will stay 6+ years, have stable income, and can cover a 20% down payment plus closing costs (typically 2–5% of the purchase price per the CFPB) without draining your emergency fund. Rates rose from 6.65% in August to 7.40% by mid-October, which widens the monthly cost gap versus renting. Run your exact numbers with a rent-vs-buy calculator before deciding.
How long do you need to stay to break even on buying vs renting?
At the October 15, 2026 PMMS average of 7.40% on a 30-year fixed, many scenarios break even in roughly 4.5 to 6 years — longer than when rates were near 6.5% in mid-2026. Closing costs of $8,000–$15,000, 1–2% annual maintenance, and the opportunity cost of your down payment all delay the point where buying costs less than renting. In high-cost cities like San Francisco or New York, break-even can still stretch to 7–9 years.
Is renting throwing money away?
No. Rent buys you housing and flexibility. On a $2,250/month lease, you pay $27,000 per year for shelter with zero maintenance bills, no property tax, and no $12,000 roof replacement risk. The money you keep out of a down payment ($78,000 on a $390,000 home) could stay in FDIC-insured savings (the FDIC national average savings rate was 0.38% as of October 2026) or, if invested for the long term, participate in historical stock-market returns that have varied widely year to year.
What hidden costs make buying more expensive than the mortgage payment?
Beyond principal and interest, homeowners pay property tax (2024 Census ACS data imply a national effective rate of about 0.89% of home value; local rates vary), insurance ($1,500–$2,600/year), maintenance and repairs (1–2% of home value annually), closing costs ($8,000–$15,000 upfront), and selling costs (5–6% agent commission when you move). On a $390,000 home at 7.40%, the true monthly cost is often $900–$1,100 higher than the mortgage payment alone.
Does buying always build more wealth than renting?
Not automatically. A renter who invests the down payment ($78,000) and monthly cost difference ($966/month in the $390,000 scenario below) at a hypothetical 7% long-term return — not a guarantee — could accumulate roughly $314,000 over 10 years. A buyer builds equity through paydown and appreciation, but pays about $466,000 in interest over 30 years at 7.40% on a $312,000 loan. Wealth building depends on how long you stay, local appreciation, and whether you actually invest the savings from renting.
Should I wait for mortgage rates to drop further before buying?
Timing the market is rarely wise. PMMS 30-year rates rose from 6.65% (August 20, 2026) to 7.40% (October 15, 2026), adding about $157/month in principal and interest on a $312,000 loan. Waiting for lower rates can coincide with higher prices: FHFA’s national house price index rose 2.6% year-over-year through July 2026 (release dated September 29, 2026). A $390,000 home appreciating at 2.6% adds about $10,140 in value in year one. Buy when you meet the 5-step framework criteria, not based on rate forecasts alone.
Related Guides
How Much House Can I Afford? Complete Guide by Income Level
Learn exactly how much home you can afford based on your salary, debts, and down payment. Includes income-based tables, a real case study, and the formulas lenders actually use.
15-Year vs 30-Year Mortgage: Which Saves You More Money?
Compare 15-year vs 30-year mortgages with real numbers on a $350K loan. See monthly payments, total interest, break-even analysis, and who should choose each term.