How to Use This Car Affordability Calculator
Enter your annual gross income, monthly take-home pay, and existing debt payments to establish your financial baseline. Add your planned down payment, trade-in value, expected interest rate, loan term, and estimated monthly insurance and fuel costs. The calculator instantly computes your maximum affordable car price using the 20/4/10 rule and shows whether your budget passes each criterion.
Results update in real time as you adjust any field. The top summary cards display your max affordable car price, recommended monthly loan payment, and your 10% gross income budget. Below that, an affordability rating color-codes whether your total car costs (payment plus insurance plus fuel) fall within 10%, 15%, or 20% of gross monthly income. Use the price comparison table to see how a $25,000 car compares to a $35,000 option at your specific loan terms. For detailed payment breakdowns on a specific vehicle price, try our Auto Loan Calculator.
The 20/4/10 Rule Explained
Financial advisors and consumer advocates widely recommend the 20/4/10 rule as a framework for car buying. Each number represents a specific limit designed to keep transportation costs from crowding out savings, housing, and other priorities.
- 20% down payment — Put at least 20% of the vehicle purchase price down at signing. On a $30,000 car, that means $6,000 upfront. A larger down payment reduces your loan balance, lowers monthly payments, and helps you avoid being upside-down (owing more than the car is worth) if you need to sell early.
- 4-year maximum loan term — Finance the vehicle for no more than 48 months. On a $21,750 loan (a $25,000 car with $5,000 down and 7% tax), 48 months at the Federal Reserve G.19 60-month bank average of 7.54% (August 2026) costs about $526 per month and $3,512 in interest. Stretching to 60 months drops the payment to $436 but adds $912 in total interest.
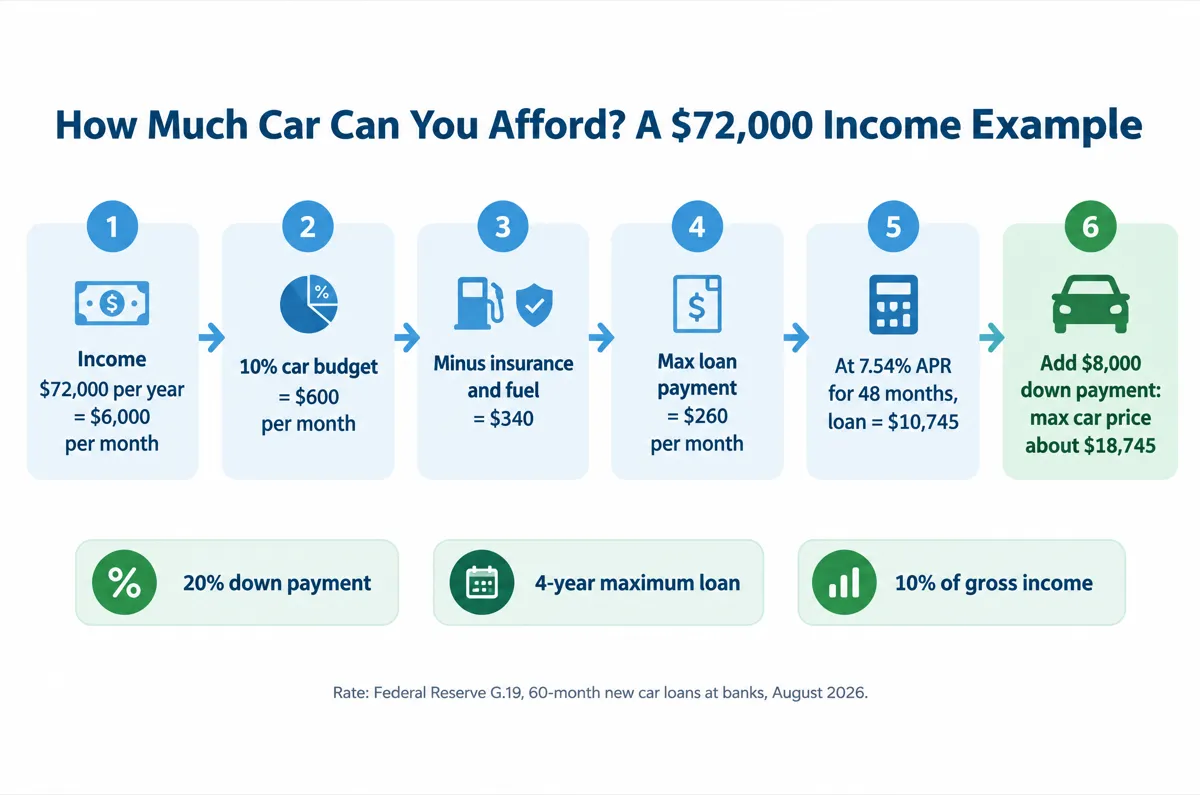
- 10% of gross income for all car costs — Your combined monthly loan payment, insurance, and fuel should not exceed 10% of gross monthly income. Someone earning $72,000 per year ($6,000/month gross) has a $600 monthly car budget. With $165 for insurance and $175 for fuel, the maximum loan payment is $260 per month.
The 10% rule uses gross income (before taxes), not take-home pay. If your gross monthly income is $5,417 ($65,000/year), your total car budget is $542 per month. After $150 for insurance and $150 for fuel, you can afford a loan payment of roughly $242 per month on a 60-month term at 7.54% APR — supporting a maximum car price near $17,050 with a $5,000 down payment in this calculator.
Sources Federal Reserve G.19 Consumer Credit (Aug. 2026, released Oct. 7, 2026), Kelley Blue Book / Cox Automotive — Sept. 2026 average transaction price ($50,562), Experian — Auto Loan Rates and Financing (Q2 2026). Checked October 2026.
Case Study: Sophia Buys Her First Car in Phoenix
Sophia is a 29-year-old data analyst living in Phoenix, Arizona. She earns $72,000 per year ($6,000/month gross, $4,600/month take-home after taxes and her 401(k) contribution). Her existing monthly debt payments total $380 — $280 for student loans and $100 in credit card minimums. She has saved $8,000 for a down payment and expects $0 trade-in value on her current vehicle.
Sophia estimates $165 per month for full-coverage insurance (Arizona averages $1,810/year for a 30-year-old driver) and $175 per month for fuel based on her 25-mile daily commute. She plans to finance at 6.5% APR over 48 months, following the 4-year recommendation.
| Input | Value |
|---|---|
| Annual Gross Income | $72,000 |
| Monthly Take-Home Pay | $4,600 |
| Existing Monthly Debts | $380 |
| Down Payment | $8,000 |
| Interest Rate / Term | 7.54% APR / 48 months |
| Insurance + Fuel | $340/month |
Using the 10% rule, Sophia's total car budget is $600 per month ($6,000 x 0.10). After subtracting $340 for insurance and fuel, her maximum loan payment is $260 per month. At 7.54% over 48 months, that supports a loan of about $10,745, plus her $8,000 down payment, for a maximum car price near $18,745. Her 48-month term passes the 4-year rule. Total monthly car costs of $600 equal exactly 10% of gross income, earning an "Excellent" affordability rating.
After car costs and existing debts, Sophia retains $3,620 per month from take-home pay ($4,600 - $600 - $380). She targets a $17,500 used Toyota Corolla, which produces a $260 monthly payment, $600 total monthly car costs (10.0% of gross income), and leaves her $3,620 for rent, groceries, and savings. For a broader view of her overall spending, she checks her numbers against the 50/30/20 Budget Calculator.
Car Affordability by Income Level
The table below shows recommended car budgets at common salary levels. Assumptions: 7.54% APR (Federal Reserve G.19 60-month bank average, August 2026), 48-month loan term, $150/month insurance, $150/month fuel, and a 20% down payment (max price = max loan ÷ 0.80). Actual affordability varies based on your debts, credit score, and local insurance rates.
| Annual Salary | Gross Monthly | 10% Car Budget | Max Loan Payment | Recommended Max Car Price |
|---|---|---|---|---|
| $40,000 | $3,333 | $333/mo | $33/mo | $1,700 |
| $55,000 | $4,583 | $458/mo | $158/mo | $8,200 |
| $70,000 | $5,833 | $583/mo | $283/mo | $14,600 |
| $85,000 | $7,083 | $708/mo | $408/mo | $21,100 |
| $100,000 | $8,333 | $833/mo | $533/mo | $27,600 |
| $120,000 | $10,000 | $1,000/mo | $700/mo | $36,200 |
Notice how insurance and fuel consume a fixed portion of the budget regardless of income. At $40,000/year, $300 in insurance and fuel leaves only $33 for the loan payment — which is why lower-income buyers often need larger down payments, shorter commutes, or used vehicles below Cox Automotive's $27,235 average used listing price (mid-October 2026). At $120,000/year, the same $300 in operating costs leaves $700 for the loan, supporting a car priced more than twenty times the $40,000 row above. Check your full debt picture with our Debt-to-Income Calculator before adding a car payment to your monthly obligations.
Tips for Getting the Best Deal
Get pre-approved before visiting dealerships. A pre-approval letter from your bank or credit union gives you a firm rate and budget ceiling. On a $21,750 loan over 48 months, the difference between 6.35% (Experian Q2 2026 new average) and 7.54% (G.19 bank average) is about $14 per month and $672 in total interest.
Compare new vs. certified pre-owned. Kelley Blue Book's September 2026 compact-car average transaction price was $27,977 versus a $50,562 industry average for all new vehicles. A 2-year-old certified Honda near $22,000 saves thousands upfront versus new and cuts the loan payment by roughly $100 per month at 7.54% over 48 months compared with financing $28,000.
Negotiate the out-the-door price, not the monthly payment. Dealers can extend loan terms or inflate trade-in values to hit a target monthly payment while increasing total cost. Focus on the total purchase price, interest rate, and loan term as separate line items. A $350/month payment over 72 months costs $25,200 total; the same payment over 48 months on a cheaper car costs $16,800.
Factor in total ownership costs beyond the sticker price. Registration fees, sales tax (which ranges from 0% in Oregon to over 9% in states like Tennessee), maintenance, and depreciation all affect your true cost. Budget an additional $50-$100 per month for maintenance on vehicles past 50,000 miles. For a deeper dive into car buying strategy, read our car affordability guide.
Frequently Asked Questions
Should I use gross or net income for the 10% rule?
Use gross income (before taxes and deductions). The 10% rule is designed as a conservative ceiling that accounts for the gap between gross and take-home pay. If you earn $80,000/year ($6,667/month gross, roughly $4,800 take-home), your car budget is $667/month based on gross income — not $480 based on net. Using gross income prevents overcommitting when taxes, health insurance, and retirement contributions consume 25-35% of your paycheck.
What if I cannot afford 20% down?
Many buyers start with less than 20% down, especially on first purchases. If you put 10% down on a $25,000 car ($2,500) instead of 20%, the tax-inclusive loan rises by about $2,000 — adding roughly $48 per month on a 48-month loan at 7.54% APR. The trade-off is higher monthly payments and greater risk of negative equity. Consider saving longer, buying below the $27,977 compact-car average, or targeting used inventory near $15,000–$20,000 where a $3,000–$4,000 down payment meets the 20% threshold.
Does the 10% rule include maintenance and repairs?
The traditional 20/4/10 rule covers loan payment, insurance, and fuel only. Maintenance is not included in the 10% calculation, which is why financial planners recommend treating the 10% figure as a ceiling rather than a target. Budget an additional 1-2% of the car's value per year for maintenance — roughly $25-$50 per month on a $20,000 vehicle. Older cars with 75,000+ miles may need $100-$150 per month for repairs and scheduled service.
How does my credit score affect affordability?
Credit score directly impacts your interest rate, which changes how much car your monthly payment can support. Experian's Q2 2026 averages show super-prime new borrowers at 4.41% APR versus deep-subprime at 16.11% on the same loan amount — a spread of hundreds of dollars per month. On a $22,000 loan over 48 months, a 3-point APR reduction saves about $700 in total interest. Check your credit report before shopping and consider delaying a purchase if you can improve your score by 30–50 points within six months.
Is leasing a better option if I cannot meet the 20/4/10 rule?
Leasing typically offers lower monthly payments — Edmunds' lease calculator guidance uses about 53% residual value on a 36-month term as a planning assumption, which often produces payments below a 7.54% purchase loan on the same MSRP. However, leases come with mileage limits (usually 10,000–12,000 miles per year), wear-and-tear charges, and no equity. Run both paths in our Lease vs Buy Car Calculator before deciding, and avoid leasing if you drive more than 15,000 miles per year.