How Dividends Work
A dividend is a portion of a company's earnings distributed to shareholders, typically on a quarterly basis. When a company earns profits beyond what it needs for reinvestment and operations, the board of directors can vote to return some of that cash to shareholders. Dividends are usually expressed as a dollar amount per share: if a company pays $2.00 annually and you own 100 shares, you receive $200 per year in dividend income.
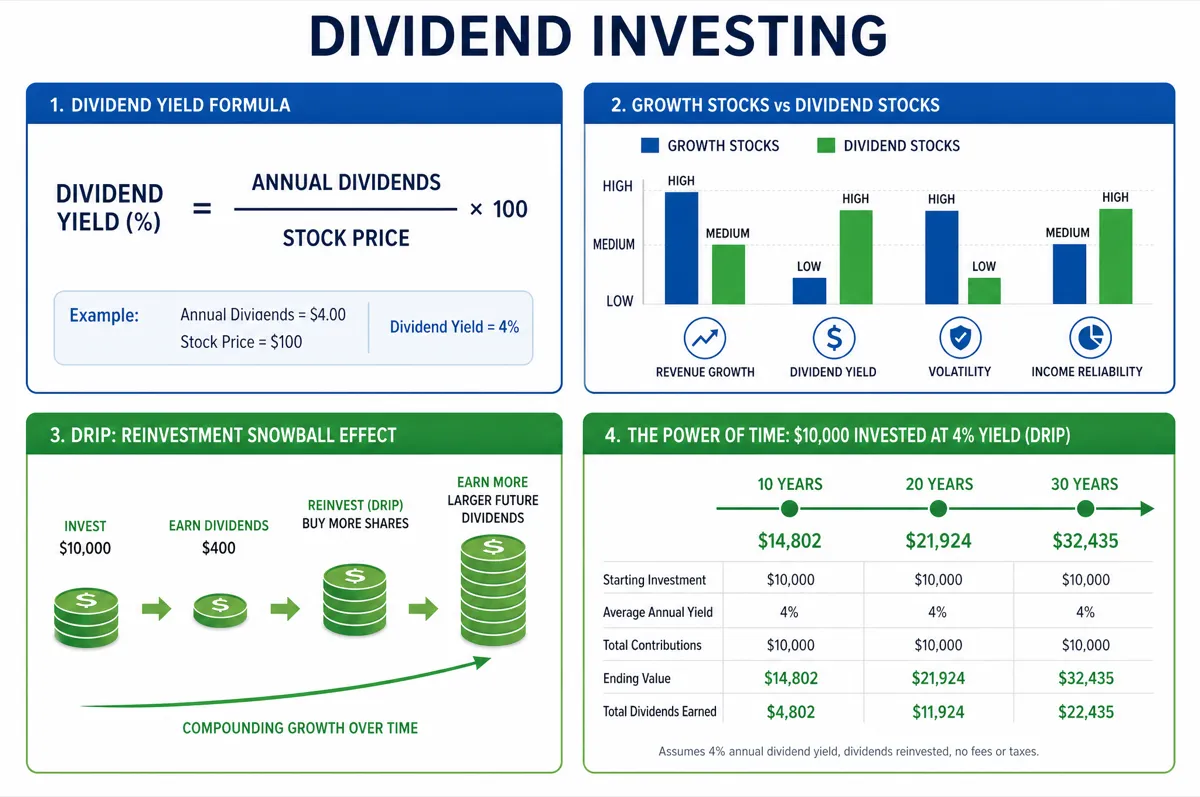
The dividend yield — calculated by dividing the annual dividend per share by the current share price — is the metric investors use to compare income across different stocks. A stock trading at $50 that pays $2.00 annually has a 4.0% yield. That same $2.00 dividend on a stock trading at $100 produces only a 2.0% yield. Yield fluctuates daily as the share price moves, which is why a rising stock price can actually reduce your yield even if dividends stay constant. Tracking your total returns over time with our Investment Return Calculator helps separate price appreciation from dividend income in your portfolio.
Dividend Yield vs. Dividend Growth
Investors broadly fall into two camps: those who prioritize high current yield and those who prioritize dividend growth. High-yield stocks (utilities, REITs, tobacco companies) often pay 5% to 8% but grow dividends slowly at 1% to 3% per year. Dividend growth stocks (technology, healthcare, consumer staples aristocrats) might yield only 1.5% to 3% initially but raise their dividends 8% to 15% annually.
The math reveals a critical crossover point. A stock yielding 2.0% with 10% annual dividend growth will surpass the income from a 5.0% yielder growing at 2% in approximately year 10. By year 20, the growth stock produces nearly three times the annual income. This is why many long-term investors prefer growth: the income starts smaller but compounds aggressively. The effect mirrors the principles behind compound interest, where time transforms modest growth rates into powerful wealth accumulation.
The Power of DRIP (Dividend Reinvestment)
A Dividend Reinvestment Plan (DRIP) automatically uses your dividend payments to purchase additional shares of the same stock. Instead of receiving $200 in cash, you receive 4 additional shares at $50 each. Those 4 new shares then generate their own dividends, which buy more shares, which generate more dividends — creating a compounding snowball effect.
DRIP is most powerful over long time horizons. Consider an investor who buys $10,000 worth of a stock yielding 3.5% with 6% annual dividend growth and 7% share price appreciation. On a hypothetical $10,000 stake with a 3.5% starting yield, 6% dividend growth, and 7% price growth, the calculator shows about $54,274 after 25 years without DRIP versus about $116,562 with DRIP — more than double the ending value from reinvesting rather than spending dividends (illustrative constants, not a single fund).
Source S&P DJI dividend contribution research (Feb. 2025 data). Checked October 2026.
Case Study: Marcus Builds a Dividend Income Stream
Marcus is 30 years old and wants to build a portfolio that generates $24,000 per year ($2,000 per month) in dividend income by age 55. He starts with $15,000 and can invest $400 per month. He builds a diversified portfolio of dividend growth stocks and ETFs with an average yield of 3.0%, average dividend growth of 7%, and average share price appreciation of 8% per year.
Using the calculator with $15,000 upfront, $400 per month, a 3.0% starting yield, 7% dividend growth, 8% price growth, and DRIP, year 1 ends near $21,624 in portfolio value with about $624 in dividends. By year 10 he reaches about $125,604 ($3,342 in annual dividends). Year 15 crosses $241,020 ($6,129 dividends). At year 25 the portfolio is about $745,640 throwing off $17,316 in annual dividends — below his $24,000 target on these constants, so he would nudge contributions, yield, or timeline rather than assume guaranteed market results.
Of the $745,640 at year 25, only $135,000 came from Marcus's contributions; the rest came from modeled price gains and reinvested dividends. Starting early and staying consistent let compounding do the heavy lifting. For a broader perspective on retirement income planning, explore our ROI Calculator to compare dividend investing against other income-generating strategies.
High Yield vs. Growth: 25-Year Comparison
| Metric | High Yield (5%, 2% Growth) | Dividend Growth (2.5%, 10% Growth) |
|---|---|---|
| Year 1 Income | $500 | $250 |
| Year 10 Income | $597 | $648 |
| Year 20 Income | $728 | $1,682 |
| Year 25 Income | $804 | $2,710 |
| Total Dividends (25 yr) | $16,406 | $22,159 |
| Crossover Point | Year 10 (growth income surpasses high yield) | |
This comparison assumes a $10,000 initial investment with no additional contributions and no DRIP. The dividend growth portfolio generates 35% more total income over 25 years despite starting at half the yield. With DRIP enabled, the gap widens further because growth stocks reinvest at a faster-accelerating rate.
Building a Dividend Portfolio: Practical Tips
- Diversify across sectors: Holding dividend stocks in utilities, healthcare, consumer staples, financials, and REITs protects you from sector-specific cuts. If one industry slashes dividends, others likely continue paying.
- Focus on payout ratio: A company paying 40% to 60% of earnings as dividends is sustainable. Above 80% signals the dividend may be at risk during a downturn. Below 30% suggests room for future increases.
- Use dividend ETFs for simplicity: Funds like VYM (Vanguard High Dividend Yield), SCHD (Schwab U.S. Dividend Equity), and DGRO (iShares Core Dividend Growth) provide instant diversification across 200+ dividend payers for expense ratios under 0.10%.
- Track yield on cost, not current yield: Yield on cost measures your dividend income relative to what you actually paid. A stock bought at $40 now paying $3.20 yields 8.0% on cost even if current yield is only 3.5%. This metric reveals the real power of holding quality dividend growers.
- Reinvest in tax-advantaged accounts: Hold dividend stocks in IRAs or 401(k)s when possible to avoid annual tax drag. Qualified dividends in taxable accounts are taxed at 0% to 20% depending on income, but tax deferral still accelerates compounding. Compare account options using our beginner investing guide.
Dividend Aristocrats and Kings
Dividend Aristocrats are S&P 500 companies that have raised their dividend for at least 25 consecutive years; the index listed 69 members after the January 2026 reconstitution (S&P Dow Jones Indices). Dividend Kings have done so for 50+ years. Names such as Johnson & Johnson, Procter & Gamble, Coca-Cola, and 3M have demonstrated resilience through recessions, market crashes, and industry disruptions. While past performance does not guarantee future results, a 25-year track record of increasing payouts is a strong signal of financial discipline and shareholder commitment.
Investors building a dividend income stream often anchor their portfolio with 5 to 10 Aristocrats or Kings, then supplement with higher-growth dividend payers for acceleration. This barbell approach balances reliability with growth potential. Read more about building a diversified foundation in our compound interest examples guide.
FAQ
How often are dividends paid?
Most U.S. companies pay dividends quarterly (four times per year). Some REITs and international stocks pay monthly. A few companies pay semi-annually or annually. You can build a monthly income stream by holding stocks with staggered payment schedules — for example, one stock paying in January/April/July/October and another paying in February/May/August/November.
What is a good dividend yield?
For U.S. large-cap stocks, 2.0% to 4.0% is typical for established dividend payers. Below 2.0% often indicates a growth company with a small payout. Above 6.0% may signal an unsustainable payout or a falling stock price (which inflates the yield calculation). The broad S&P 500 index yield was about 1.05% in October 2026 (Multpl), below the long-run historical average near 4% because index prices outran dividend growth.
Sources Multpl S&P 500 dividend yield (Oct. 20, 2026), S&P DJI Dividend Aristocrats research (2026 roster). Checked October 2026.
Are dividends taxed?
Qualified dividends (from stocks held more than 60 days) are taxed at long-term capital gains rates for tax year 2026: 0% up to about $49,450 for single filers (October 20, 2026 IRS brackets), 15% for most middle-income taxpayers, and 20% above the top threshold. Non-qualified (ordinary) dividends — common on many REIT payouts — are taxed at regular income rates. Holding dividend stocks in tax-advantaged accounts like IRAs eliminates annual tax drag entirely.
Source IRS Topic 409, Capital Gains and Losses. Checked October 2026.
Should I reinvest dividends or take cash?
If you are in the accumulation phase (building wealth for future goals), reinvesting via DRIP maximizes compounding and is almost always the better choice. If you are in the distribution phase (relying on portfolio income for living expenses), taking cash makes sense. The calculator above lets you model both scenarios to see the long-term impact.
What happens if a company cuts its dividend?
A dividend cut reduces your income from that holding and usually causes the stock price to drop 10% to 30% on the announcement. Diversification is your primary protection: if one of 20 holdings cuts its dividend, you lose roughly 5% of portfolio income rather than a catastrophic amount. Monitor payout ratios and earnings trends to identify at-risk dividends before cuts happen.