Guides / Loans & Mortgages
Amortization Schedule Explained: How Your Loan Payments Actually Work
Every month you make a mortgage or car payment, a hidden tug-of-war plays out between principal and interest. An amortization schedule reveals exactly where each dollar goes -- and why a $350,000 mortgage at 6.5% costs you $446,406 in interest alone over 30 years. This guide breaks down the amortization formula, walks through a real payment schedule month by month, and shows you concrete strategies to tilt the balance in your favor.
Last updated: October 2026
TL;DR - Quick Answer
- What it is: A table showing exactly how much of each loan payment goes to principal (reducing your balance) vs. interest (the lender's profit)
- Key insight: On a $350,000 mortgage at 6.5%, your first payment is $2,212 -- but only $316 reduces your balance. The other $1,896 (85.7%) is pure interest
- The shift: By payment 233 (year 19), the split flips -- more than half of each payment finally goes to principal
- Total cost: 360 payments of $2,212 = $796,406 total. You pay $446,406 in interest on a $350,000 loan
Generate your own schedule with our Amortization Calculator for instant results.
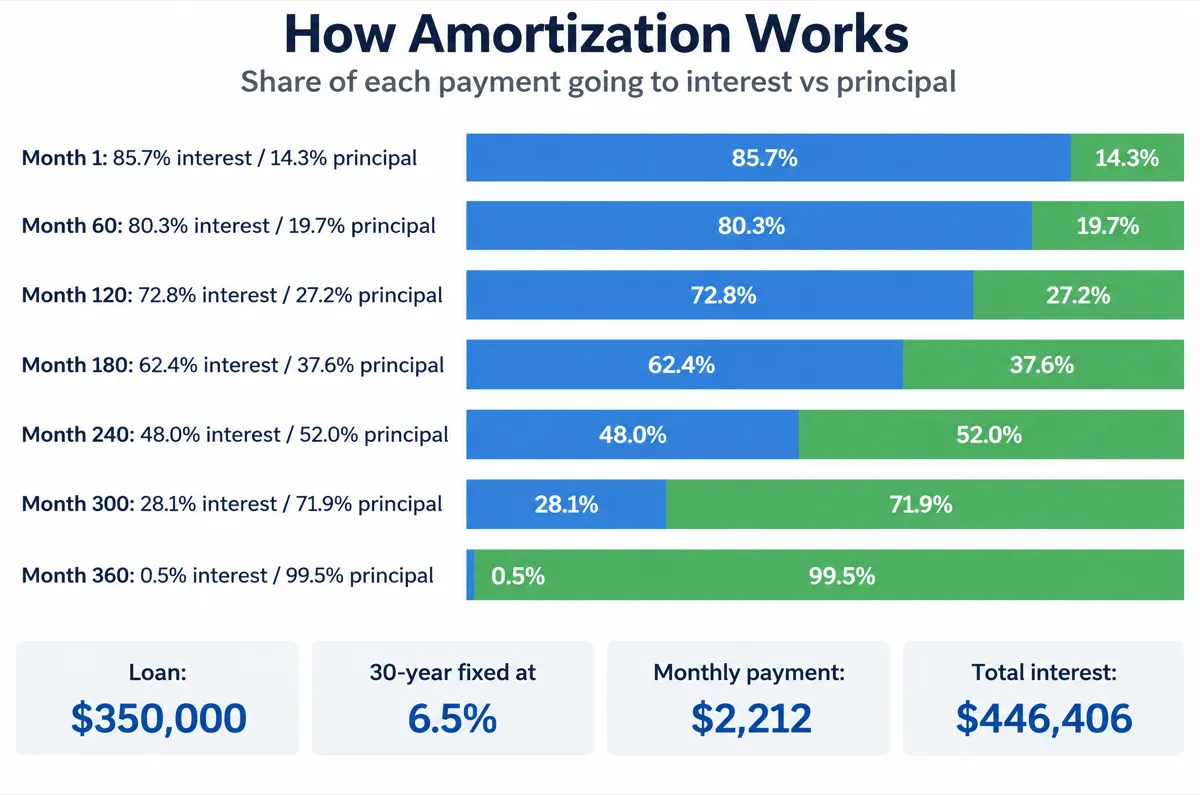
How an Amortization Schedule Works
An amortization schedule is a payment-by-payment roadmap for any installment loan -- mortgages, auto loans, personal loans, and student loans all use the same underlying math. The schedule shows three things for every payment: the interest charge, the principal reduction, and the remaining balance.
The core mechanic is simple: interest is always calculated on the current outstanding balance. On day one of a $350,000 mortgage at 6.5% APR, the monthly interest rate is 0.5417% (6.5% / 12). The first month's interest charge is $350,000 x 0.005417 = $1,895.83. Your fixed payment is $2,212.24, so only $316.41 goes toward reducing the principal. Your new balance drops to $349,683.59.
The next month, interest is calculated on $349,683.59 instead of $350,000. That saves you $1.71 in interest, meaning $318.12 goes to principal -- $1.71 more than last month. This snowball effect accelerates: by month 12, the principal portion has grown to $336 ($20 more than month 1). By month 120 (year 10), it reaches $602. By month 300 (year 25), it hits $1,591 -- about five times the initial principal payment.
The amortization formula that determines your fixed monthly payment is:
M = P x [r(1+r)^n] / [(1+r)^n - 1]
M = monthly payment, P = principal ($350,000), r = monthly rate (0.005417), n = total payments (360)
For our example: M = $350,000 x [0.005417 x (1.005417)^360] / [(1.005417)^360 - 1] = $2,212.24. This payment stays identical for all 360 months on a fixed-rate mortgage. What changes is the split: the interest portion starts at $1,896 and falls to $12 in the final month, while the principal portion starts at $316 and grows to $2,200.
Use our Amortization Calculator to generate a complete payment schedule for any loan amount, rate, and term. For comparing different loan options side by side, try the Mortgage Calculator.
Sample Amortization Schedule: $350,000 at 6.5% for 30 Years
Below is a snapshot of key months from a real amortization schedule. Notice how the interest-to-principal ratio flips dramatically over time:
| Payment | Principal | Interest | Total Payment | Remaining Balance | Principal % |
|---|---|---|---|---|---|
| 1 (Month 1) | $316 | $1,896 | $2,212 | $349,684 | 14.3% |
| 12 (Year 1) | $336 | $1,876 | $2,212 | $346,088 | 15.2% |
| 60 (Year 5) | $435 | $1,777 | $2,212 | $327,638 | 19.7% |
| 120 (Year 10) | $602 | $1,610 | $2,212 | $296,716 | 27.2% |
| 233 (Year 19) | $1,108 | $1,104 | $2,212 | $202,754 | 50.1% |
| 240 (Year 20) | $1,255 | $957 | $2,212 | $176,240 | 56.7% |
| 300 (Year 25) | $1,591 | $621 | $2,212 | $113,065 | 71.9% |
| 360 (Year 30) | $2,200 | $12 | $2,212 | $0 | 99.5% |
Highlighted row: payment 233 (year 19) is the crossover point where principal exceeds interest for the first time on this loan.
Table values recomputed from the standard fixed-rate amortization formula (October 2026 check); amounts rounded to the nearest dollar.
How Loan Term and Rate Affect Amortization
The loan term and interest rate dramatically change how amortization plays out. A shorter term means higher monthly payments but a faster crossover to principal-heavy payments -- and far less total interest paid:
| Loan Scenario | Monthly Payment | Total Interest | Total Cost | Crossover Month | Interest % of 1st Payment |
|---|---|---|---|---|---|
| $350K / 30-yr / 6.5% | $2,212 | $446,406 | $796,406 | Month 233 | 85.7% |
| $350K / 15-yr / 6.71% | $3,089 | $206,097 | $556,097 | Month 57 | 63.3% |
| $350K / 30-yr / 4.0% | $1,671 | $251,543 | $601,543 | Month 153 | 69.8% |
| $30K / 5-yr / 7.5% (auto) | $601 | $6,068 | $36,068 | Month 1 | 31.2% |
The difference is stark: a 15-year mortgage at 6.71% (the Freddie Mac PMMS 15-year average as of October 15, 2026) saves $240,309 in interest compared to the 30-year at 6.5% -- and the crossover point arrives in year 5 instead of year 19. The 5-year auto loan sends more to principal than interest from the first payment because the shorter term keeps each installment principal-heavy from the start.
Compare these scenarios yourself with our Mortgage Calculator or Auto Loan Calculator.
Sources Freddie Mac PMMS (15-year FRM 6.71%, week of Oct. 15, 2026), Freddie Mac PMMS archive (weekly 30- and 15-year averages, 2026). Checked October 2026. The 6.5% and 4.0% 30-year rows are illustrative fixed-rate examples; the 15-year row uses the published PMMS average for that week.
Case Study: Rachel Discovers Where Her Mortgage Payments Go
Rachel is a 32-year-old physical therapist earning $78,000 in Charlotte, NC. She recently bought a $320,000 home with 10% down ($32,000) and financed $288,000 at 6.75% over 30 years. Her monthly principal and interest payment is $1,868.
When Rachel looked at her first mortgage statement, she was surprised: of the $1,868 payment, only $248 went to principal. The remaining $1,620 -- 86.7% -- went straight to interest. After 12 months of payments totaling $22,416, she had only reduced her balance from $288,000 to $284,931. She paid $19,346 in interest and just $3,069 in principal during her entire first year.
Rachel decided to use two strategies to accelerate her amortization. First, she set up biweekly payments of $934 (half the monthly amount), which results in 26 half-payments -- the equivalent of 13 full payments per year instead of 12. Second, she directed her annual $3,200 tax refund as a lump-sum extra principal payment each spring.
The combined impact on her amortization schedule is dramatic:
- Standard schedule: 360 payments, $384,467 total interest, payoff in 2056
- With biweekly + annual lump sum: Equivalent of ~267 monthly payments, approximately $246,000 total interest, payoff in 2048
- Savings: $138,480 less interest, 8 years shorter loan
- Extra cost: One additional monthly payment per year ($1,868) plus $3,200 annual lump sum = $5,068/year in extra payments
Rachel's crossover point -- where principal exceeds interest in each payment -- moves from about month 238 (year 20) on the standard schedule to approximately month 144 (year 12) with her accelerated strategy. That means she starts building equity faster during the years when her home is most likely to appreciate.
Step-by-Step: How to Read and Use Your Amortization Schedule
- Get your schedule. Use our Amortization Calculator or request one from your lender. You need three inputs: loan amount, interest rate, and term length. The calculator generates every monthly payment with the principal/interest split.
- Find your crossover point. Scan the schedule for the month where the principal column first exceeds the interest column. On a 30-year mortgage at 6-7%, this typically falls between year 16 and year 20. Mark this date -- it is when your equity building truly accelerates.
- Calculate total interest cost. Add up the interest column for the full schedule. This is the true cost of borrowing. On a $350,000 loan at 6.5% for 30 years, you pay $446,406 in interest -- about 128% of the original loan amount.
- Model extra payments. Use the calculator to add a monthly extra payment ($100, $200, $500) and compare the new schedule to the original. Note three changes: shorter payoff date, lower total interest, and an earlier crossover point.
- Compare refinancing scenarios. If rates drop, generate a new amortization schedule at the lower rate. Compare total interest remaining on your current schedule vs. the new schedule, accounting for refinancing costs (typically 2–5% of the purchase price per the CFPB, excluding the down payment).
- Review annually. Pull your current amortization schedule each year. Confirm your balance matches the projected remaining balance. If you have made extra payments, the balance should be lower than the original schedule predicted, meaning you are ahead of schedule.
Source CFPB, closing costs typically 2–5% of purchase price (excluding down payment). Checked October 2026.
See Your Payment Breakdown
Generate a complete amortization schedule for your loan -- see every payment, the principal/interest split, and how extra payments change your timeline.
FAQ
What is an amortization schedule?
An amortization schedule is a table that shows every payment over the life of a loan, broken into two parts: principal (which reduces the balance you owe) and interest (the cost of borrowing). Each row represents one payment period -- typically monthly -- and shows how the split between principal and interest shifts over time. Early payments are mostly interest; later payments are mostly principal. The schedule also tracks your remaining balance after each payment.
Why do I pay more interest at the beginning of a loan?
Interest is calculated as a percentage of your outstanding balance. At the start of a 30-year mortgage, your balance is at its highest -- for example, $350,000. At 6.5% annual interest (0.5417% monthly), the first month's interest charge is $1,896. As you make payments and the balance drops, the interest portion shrinks and more of each payment goes to principal. By month 300, the balance might be $113,000, so the interest charge drops to about $620.
How is each monthly payment calculated in an amortization schedule?
The monthly payment uses the standard amortization formula: M = P x [r(1+r)^n] / [(1+r)^n - 1], where P is the loan principal, r is the monthly interest rate (annual rate divided by 12), and n is the total number of payments. For a $350,000 loan at 6.5% over 30 years: r = 0.065/12 = 0.005417, n = 360. The formula yields M = $2,212.24. This payment stays fixed for the entire loan term on a fixed-rate mortgage.
Does making extra payments change my amortization schedule?
Yes. Extra payments go entirely toward reducing the principal balance. This has two effects: it shortens the total loan term and reduces the total interest paid. For example, adding $200/month to a $350,000 mortgage at 6.5% over 30 years saves about $108,100 in interest and pays off the loan in roughly 24 years instead of 30. Even a single extra payment per year (13 payments instead of 12) can shave 4-5 years off a 30-year mortgage.
What is the difference between amortization and simple interest?
With amortized loans (mortgages, auto loans, personal loans), each fixed payment covers both interest and principal, and the loan is fully paid off at the end of the term. With simple interest loans, you pay interest only on the original principal amount -- the payment structure does not shift over time. Credit cards use a different model entirely: minimum payments are recalculated monthly based on the outstanding balance. Amortization is the most common structure for installment loans because it gives borrowers a predictable fixed payment.
Related Guides
15-Year vs 30-Year Mortgage: Which Saves You More Money?
Compare 15-year vs 30-year mortgages with real numbers on a $350K loan. See monthly payments, total interest, break-even analysis, and who should choose each term.
How Much House Can I Afford? Complete Guide by Income Level
Learn exactly how much home you can afford based on your salary, debts, and down payment. Includes income-based tables, a real case study, and the formulas lenders actually use.
Pay Off Mortgage Early vs Invest: The Math Behind the Decision
Should you pay off your mortgage early or invest the extra money? We run the real numbers at today's rates so you can see exactly which option builds more wealth.